
ACCT 210 Final, Fall 2001
American University of Beirut · Financial Accounting · 9 pages





More ACCT 210 files
- Homework Useful File · Fall 2018FileView
- Notes Accounting 210 Ch 13 · Fall 2018NotesView
- Notes Ch 11 · Fall 2018NotesView
- Project · Fall 2018ProjectView
- Useful File Notes · Fall 2018NotesView
- Notes Ch 9 · Fall 2018NotesView
- Notes Ch 10 · Fall 2018NotesView
- Useful File Useful File · Spring 2017FileView
Show the text of this final exam
Fane mgeee A mre nee = St TS
. :
pMETHCAN USIVTESILY
LIBRARY
oy CELT
' i}
American University of Berrut
School of Business
. ACCT 210
, ‘Final Exam
Fall 2001-2002
Feb 6, 2002
Instructor:____ 7 =
Time: 2 Hours
The exain contains 6 questions, make sure you answer them all,
show all supporting computations!
Good Luck!
| > Amen actnaanewenen
S pie ~ -
peu UNIVERSIT'
LIBGARY
OF Coit
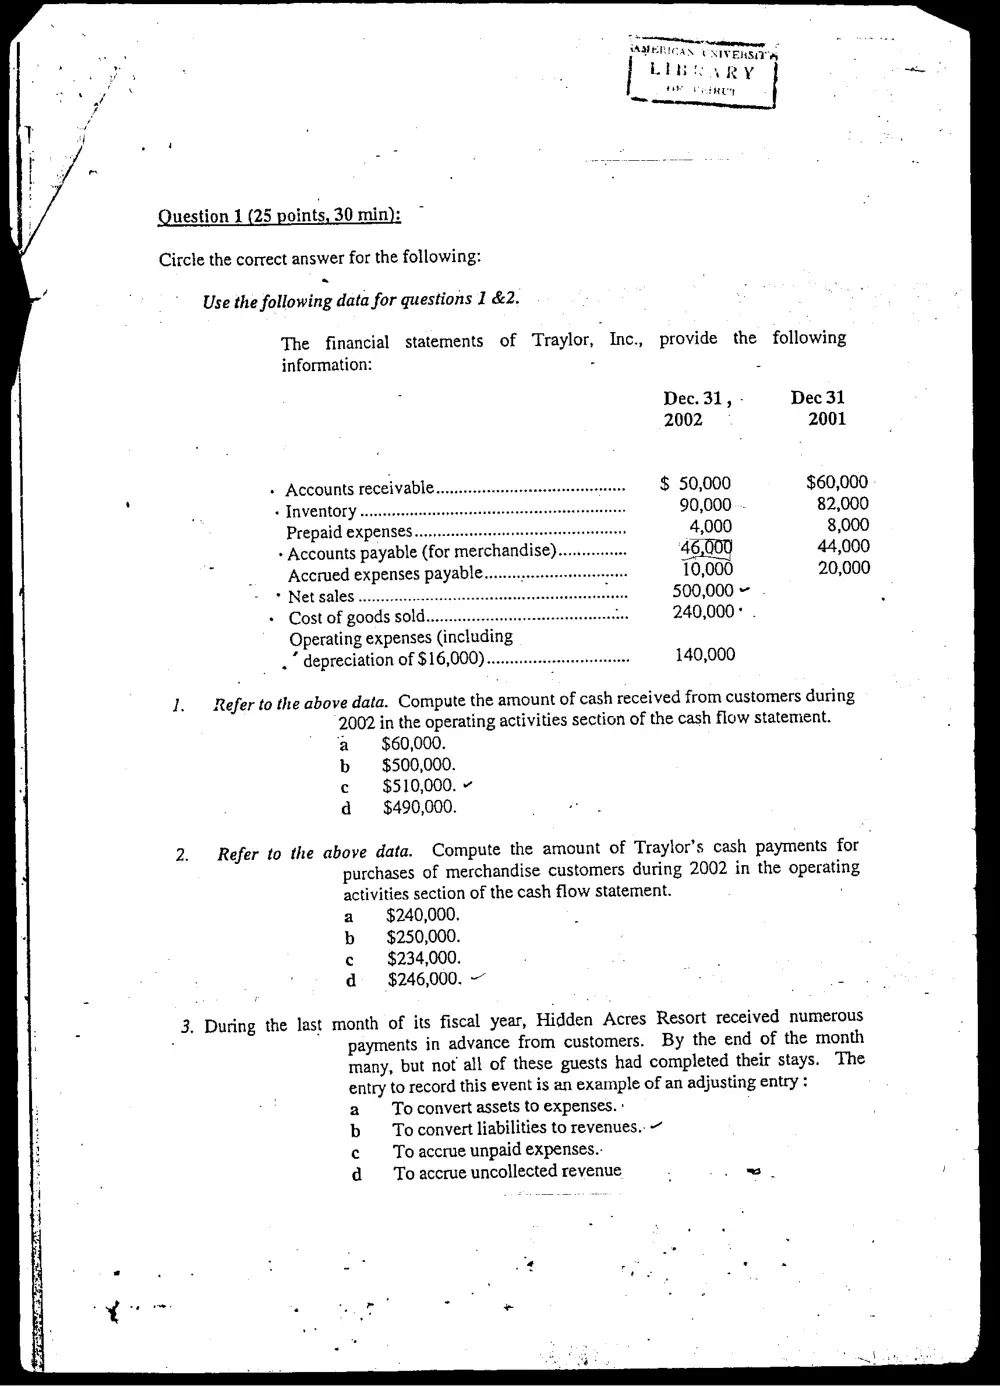
Question 1 (25 points, 30min): ~
Circle the correct answer for the following:
.
Use the following data for questions 1 &2.
The financial statements of Traylor, Inc., provide the following
information:
Dec. 31, - Dec 31
2002 2001
- Accounts receivable a. $ 50,000 $60,000
+ Inventory see 90,000 -.- 82,000
Prepaid expenses 4,000 8,000
+ Accounts payable (for merchandise) 46,000 44,000
Accrued expenses payable : 10,000 20,000
+ Net sales - 500,000~ .
+ Cost of goods sold.... wie 240,000° .
Operating expenses (including
.” depreciation of $16,000)..... sessaees 140,000
Refer to the above data. Compute the amount of cash received from customers during
2002 in the operating activities section of the cash flow statement.
‘a ~—- $60,000.
b $500,000.
c $510,000. ~
d $490,000.
2. Refer to the above data. Compute the amount of Traylor’s cash payments for
purchases of merchandise customers during 2002 in the operating
activities section of the cash flow statement.
a $240,000.
b = $250,000.
c $234,000.
d- $246,000.
3. During the last month of its fiscal year, Hidden Acres Resort received numerous
: payments in advance from customers. By the end of the month
many, but not all of these guests had completed their stays. The
entry to record this event is an example of an adjusting entry :
a _—s Tocconvert assets to expenses. ° ;
b To convert liabilities to revenues. ~
ce To accrue unpaid expenses..
dad‘ To accrue uncollected revenue
4, Chelsea Corporation’s financial statements for the current year include the following:
rp y' 8
Income from continuing operations $520,000
Cash dividends paid to preferred stockholders... . 102,000
Gain from discontinued operations (net of TAXES) cccssrevseeeees 310,000
Cumulative effect of accounting change (reduction _’
\ in net income, net of tax benefit) .... 220,000
j . Extraordinary loss (net of tax benefit)... 85,000
On the basis of this information, net income for the current year is:
a ‘$717,000. © .
b $513,000.
\ c $965,000.
y d $525,000.
iy 5. Leisure Attire ‘Corporation discontinued Princess Fashions, its entire line of children’s
¢
clothing, in November of 2001. Prior to the disposal, Princess
\ Fashions generated a loss of $300,000 (net of tax) for the period from
January through the sale date. Because of the value of the real estate
and machinery, there was a gain of $750,000 (net of tax) on the
actual sale. How should this situation be reported in the financial
statements of Leisure Attire for 2001? :
j a $450,000 included | in the 2001 income statement as an.
extraordinary item. :
: b $300,000 loss included in income from operations and a
’ ) $750,000 gain reported in the “discontinued. operations”
ha . section of the income statement.
c $450,000 adjustment to beginning retained earnings in the
statement of retained earnings.
Yr. d $450,000 gain in the “discontinued operations” section of the
: a income statement. ; :
6. On January 1, 2001, Slim Corporation had 120,000 shares of $2 par value common stock
: outstanding. On April 1, 2001, Slim issued an additional 10,000
shares in exchange for a building. What is the weighted average
number of shares to be used in the computation of basic EPS for the
par oumnrae
year 20017?
a 120,000.
b = 127,500.
t ce 130,000.
d 130,000 plus the number of shares of convedible preferred ,
stock outstanding. : .
Tr All
cP “AF TFET TH
. . eetiee cnet ou ee - > JAMERIOWN UMW ERGT
- _ ; | LIBRARY
ok OF BOIRUT
ce
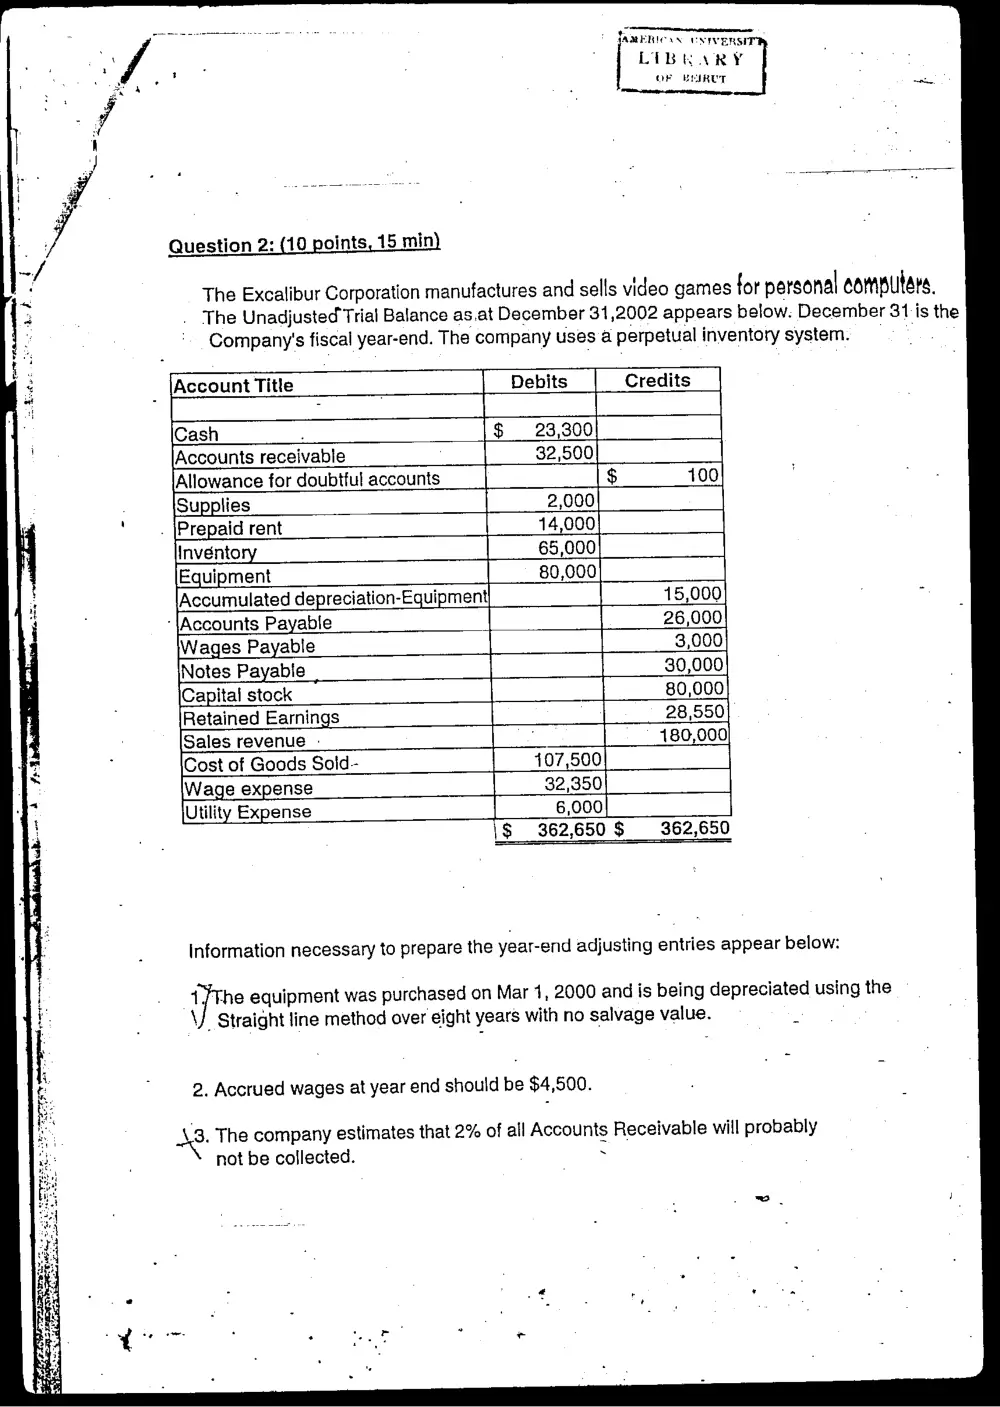
Question 2: (10 points, 15 min)
The Excalibur Corporation manufactures and sells video games for personal computars.
The Unadjusted Trial Balance as.at December 31,2002 appears below: December 31 is the
Company's fiscal year-end. The company uses a perpetual inventory system.
Account Title Debits Credits
Cash . $ 23,300
Accounts receivable 32,500
Allowance for doubtful accounts $ 100
. Supplies 2,000
‘. |Prepaid rent 14,000
Inventory 65,000
Equipment 80,000
Accumulated depreciation-Equipment 15,000 ; -
‘Accounts Payable 26,000
Wages Payable 3,000
|Notes Payable __ 30,000
Capital stock 80,000
Retained Earnings 28,550
Sales revenue - ‘ 180,000
Cost of Goods Sold- 107,500
Wage expense 32,350
Utility Expense 6,000
$ 362,650 $ 362,650
Information necessary to prepare the year-end adjusting entries appear below:
(7tme equipment was purchased on Mar 4, 2000 and is being depreciated using the
Straight line method over eight years with no salvage value.
2. Accrued wages at year end should be $4,500.
\.3. The company estimates that 2% of all Accounts Receivable will probably
~ not be collected. +
[Ae ent ee
AMERICAN UNTVERSIT
Libe \RY
E vey
~~
«
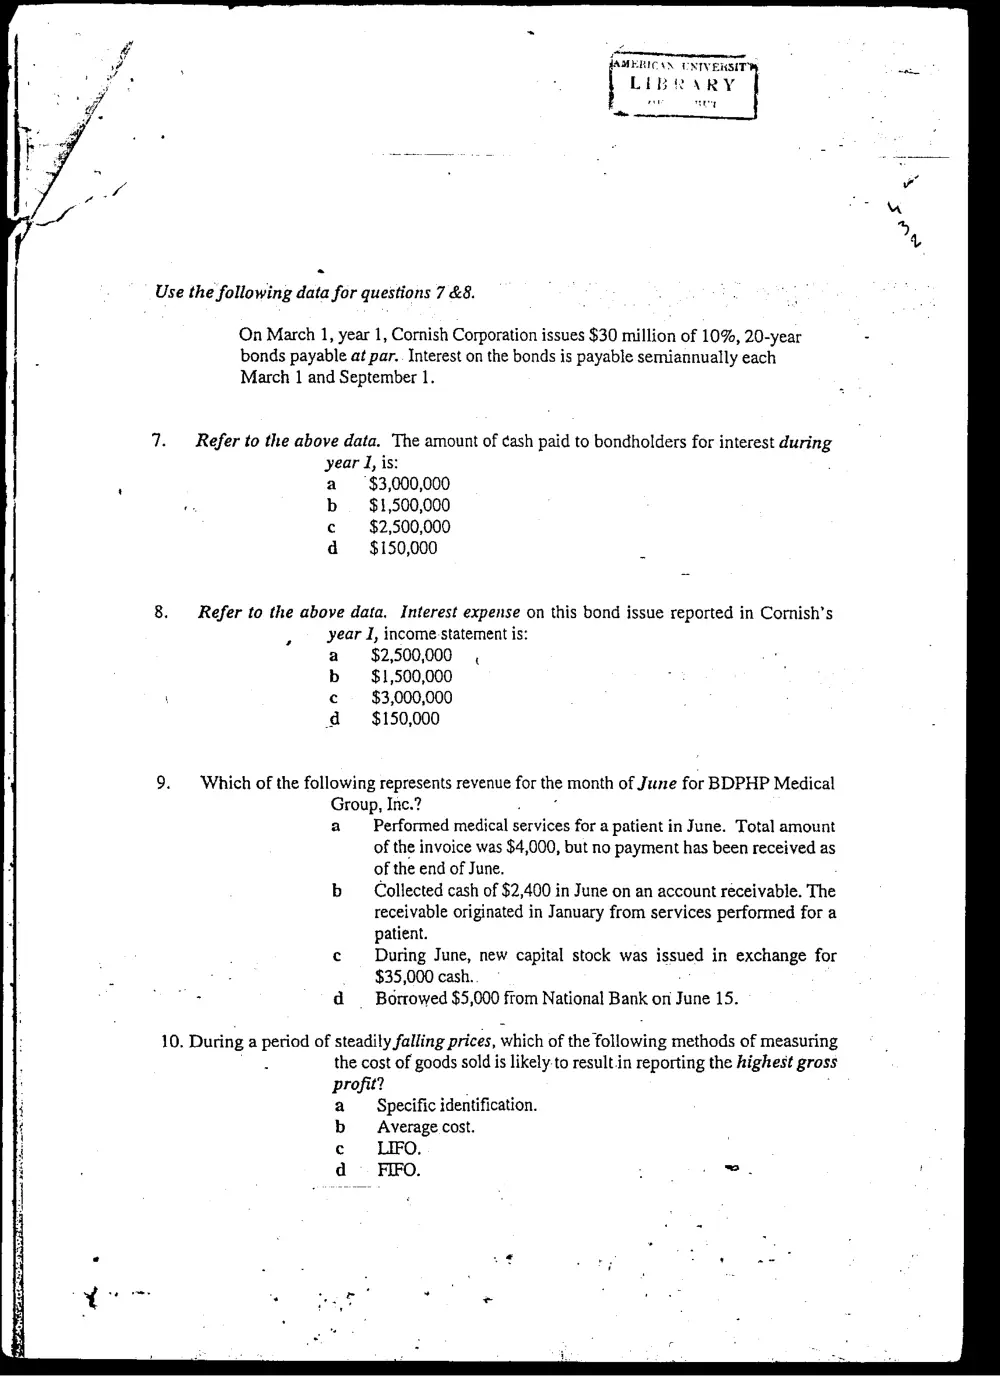
Use the following data for questions 7 &8.
On March 1, year 1, Cornish Corporation issues $30 million of 10%, 20-year
bonds payable at par.. Interest on the bonds is payable semiannually each
March 1 and September 1.
Refer to the above data. The amount of ¢ash paid to bondholders for interest during
year I, is:
a $3,000,000
b $1,500,000
¢ $2,500,000
d = $150,000
Refer to the above data. Interest expense on this bond issue reported in Cornish’s
year I, income-statement is:
a $2,500,000,
$1,500,000
b
¢ . $3,000,000
d = $150,000
Which of the following represents revenue for the month of June for BDPHP Medical
Group, Inc.? .
a __ Performed medical services for a patient in June. Total amount
of the invoice was $4,000, but no payment has been received as
of the end of June.
Collected cash of $2,400 in June on an account receivable. The
receivable originated in January from services performed for a
patient.
c During June, new capital stock was issued i in exchange for
_ $35,000 cash..
d _ Borrowed $5,000 from National Bank on June 15.
10. During a period of steadily falling prices, which of the following methods of measuring
the cost of goods sold is likely-to result in reporting the highest gross
profit?
Specific identification.
Average cost.
LIFO.
FIFO.
Instructions:
Prepare the closing entries at Dec 31, 2002
General Journal
Descriptions
Ma we. oldlare. Je Lit ceue. Seay (oeht }
—DWe_ ooh MK
Gel sen Cee acres
BS a
vA ef Ain Sie
seul! ;
: ; Ve Coe. Seas / creel E/
© Gael Gleh — daha cob) ellag om ffl Prone cag
———
. © peu! Fe bhuw fo
“4 Fe, “we JP Sue Hem rere acesih
LeMay UNTWEnai? Wo. ee
LIBRarRy
OF tetkug
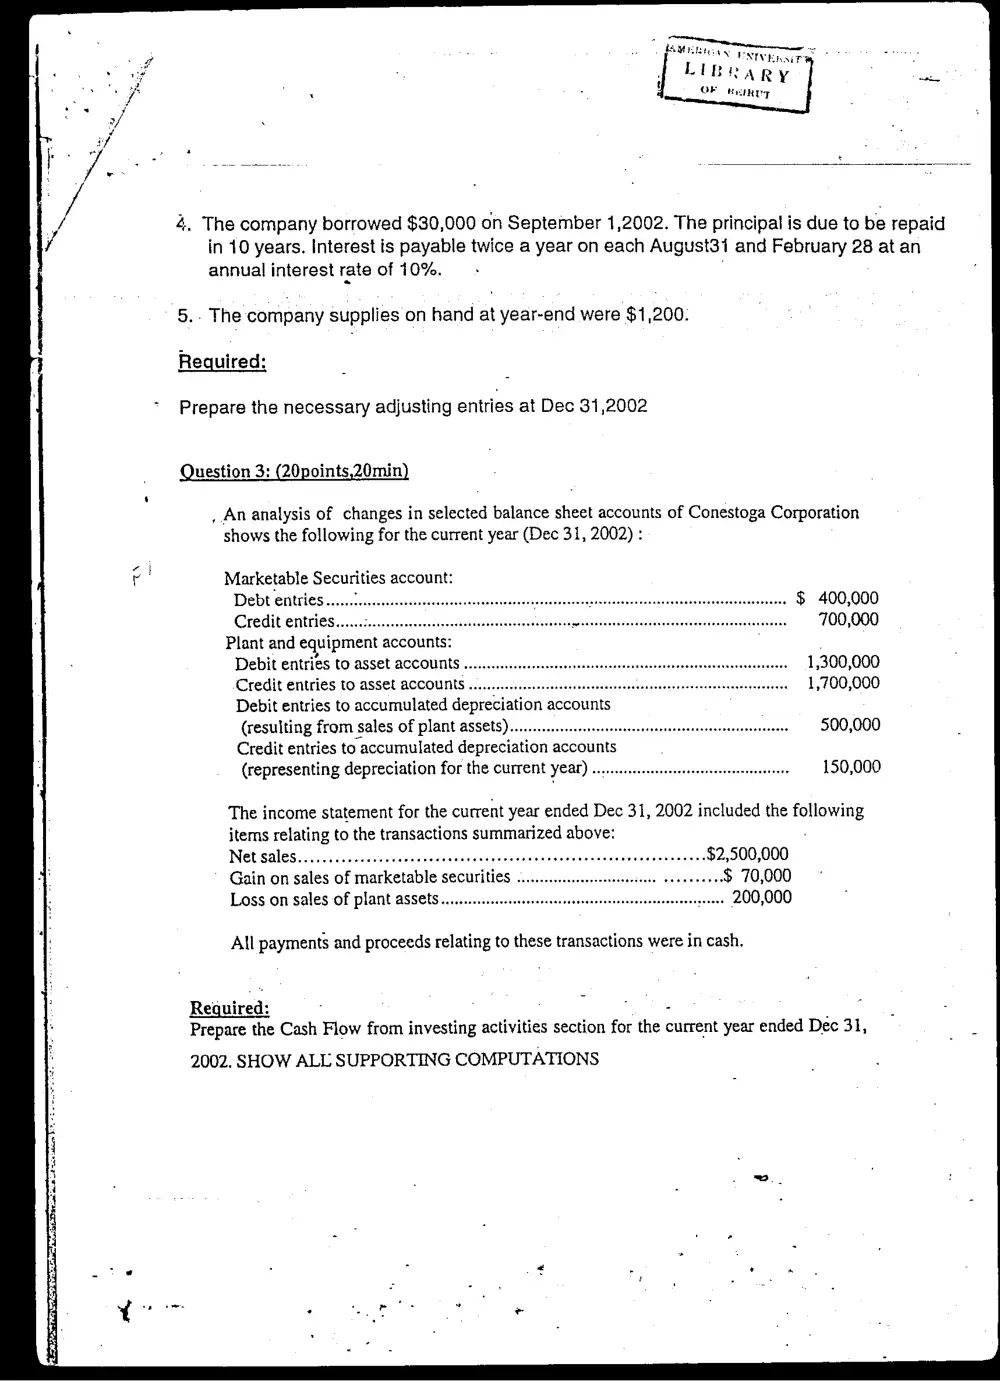
4. The company borrowed $30,000 on September 1,2002. The principal is due to be repaid
in 10 years. Interest is payable twice a year on each August31 and February 28 at an
annual interest rate of 10%. ‘
5.. The company supplies on hand at year-end were $1,200.
Required:
> Prepare the necessary adjusting entries at Dec 31,2002
Question 3: (20points,20min)
_ An analysis of changes in selected balance sheet accounts of Conestoga Corporation
shows the following for the current year (Dec 31, 2002) :
Marketable Securities account:
Debt entries......: $ 400,000
Credit entries......: .» 700,000
Plant and equipment accounts: /
Debit entries to asset accounts 1,300,000
Credit entries to asset accounts .. 1,700,000
Debit entries to accumulated depreciation accounts
(resulting from sales of plant assets) 500,000
Credit entries to accumulated depreciation accounts
(representing depreciation for the current year) .... 150,000
The income statement for the current year ended Dec 31, 2002 included the following
items relating to the transactions summarized above:
Net sales $2,500,000
Gain on sales of marketable securities vo 70,000
Loss on sales of plant assets sees 200,000
All payments and proceeds relating to these transactions were in cash.
Required: : ; ; : co ;
Prepare the Cash Flow from investing activities section for the current year ended Dec 31,
2002, SHOW ALL SUPPORTING COMPUTATIONS
eet
5
{
Question 4: (15points, 20 min)
_ The stockholders’ equity section of the balance sheet of McLintock Corporation (with
certain details omitted) appears below:
Stockholders’ equity:
6% cumulative preferred stock, $100 par, callable at $110,
200,000 shares authorized, 7? shares issued... sesesecssecseseesteeseaseess $12, 000,000
Common stock, $10 par, 500,000 shares authorized, os
77 shares issued 00.0... eeessesesessseeseeeees doteesescsvadersseneseeasaecnenecsaesesssaeaeeeeacans 3,500,000
‘ Additional paid-in capital: _ ‘
Preferred stock... “ 196,000
Common stock ... . 14,700,000
Total paid-in capital ....
Retained earnings
Total stockholders’ equity........... ecetcteeiet essssnesscessnsesessssossveeh . $34,000,000
Note : there was one year’s dividends in arrears
Required:
1. What is the total amount of legal capital?
2. Determine the number of shares of common stock issued .
3. Determine the number of shares of preferred stock issued
4. What is the total amount of annual preferred stockholders dividends?
5. What is the average issue price of a share of common stock?
6. Calculate the book value per common share.
Question 5: (15points, 15min)
On November 30, 2001, Sterling Transport signed a 5—year installment note in the
amount of $50,000 in conjunction with the purchase of a motor coach. This note is
payable in equal monthly installments of $1,112, which include interest computed at
an annual rate of 12%. The first monthly payment is made on December 31, 2001.
This note is fully amortizing over 60 months.
$30,396,000,
_3,604,000 -
ae:
f .
; [ee |
| . _ JAMERICNN CNTVERSITY . , .
‘ gt _ LIBiVRY ; “=
| i . vf OF +. RUT . :
| |
; Required:
1,Prepare the journal entry on Nov 30, 2001 to record the purchase of the Motor Coach.
2.Prepare an amortization table for the first two payments. ;
3.Prepare the necessary journal entry to record the payment on Dec 31, 2001. °
j 4. With respect to this note, determine the amount of interest expense that should be
i reported in Sterling’s 2001 income statement? -
| 5.Determine the amount of the total liability for this note payable in Sterling's Balance
sheet at Dec 31, 2001? .
| 6. Determine the total interest over the life of the loan.
| 7 Question 6: (15 points, 20 min)
| At December 31, 2001 Mayson Corporation owned the following investments in the
capital stock of publicly held corporations (all classified as available for sale
| securities): .
Cost Market Value
New Technology, Inc.( 4500 shares : .
' Cost $70per share; Market value, $83)
i $315,000 _ $373,500
Bowers, Inc. ( 2250 shares: cost, $100 per 225,000 209,250
Share; market value, 93) ; $540,000 - $582,750
i The following transactions occurred during 2002:
1, On June 4, 2002 Mayson sold 1000 shares of New Technology at a price of
$75 per share,
. 2. On September 30 2002 Mayson sold 250 shares of Bowers at a price of $94 per
P P P
| 7 share. .
The market value per share of New Technology, Inc. and Bowers, Inc. at Dec
31, 2002 was $78 & $95 respectively.
_ Required: . ; ; . —
- 1. Illustrate the presentation of Marketable Securities and the Unrealized Holding
\ Gain or Loss in Mayson’s Balance Sheet at Dec 31, 2001. .
‘. 2. Prepare the journal entries to record the sale of June 4, 2002 and September 30,
2002 .
"3. Prior to Mark to Market adjustment at the end of 2002, determine the
unadjusted balance in the marketable securities controlling account and the
Unrealized Holding Gain ( or Loss) on investment -Assume that no unrealized
gains or losses have been recognized since last year. .
4,” Prepare the Mark to Market adjusting entry at Dec 31, 2002: Show supporting
a” schedule of Marketable Securities and all computation, . _™é