
ACCT 210 Homework Chapter 2, Fall 2011
American University of Beirut · Financial Accounting · 2 pages

More ACCT 210 files
- Drop Quiz Chapter 7 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 11 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 13 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 2 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 3 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 4 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 5 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 6 Quiz Questions · Summer 2017ChapterView
Show the text of this chapter
© The McGraw-Hill Companies, Inc., 2012
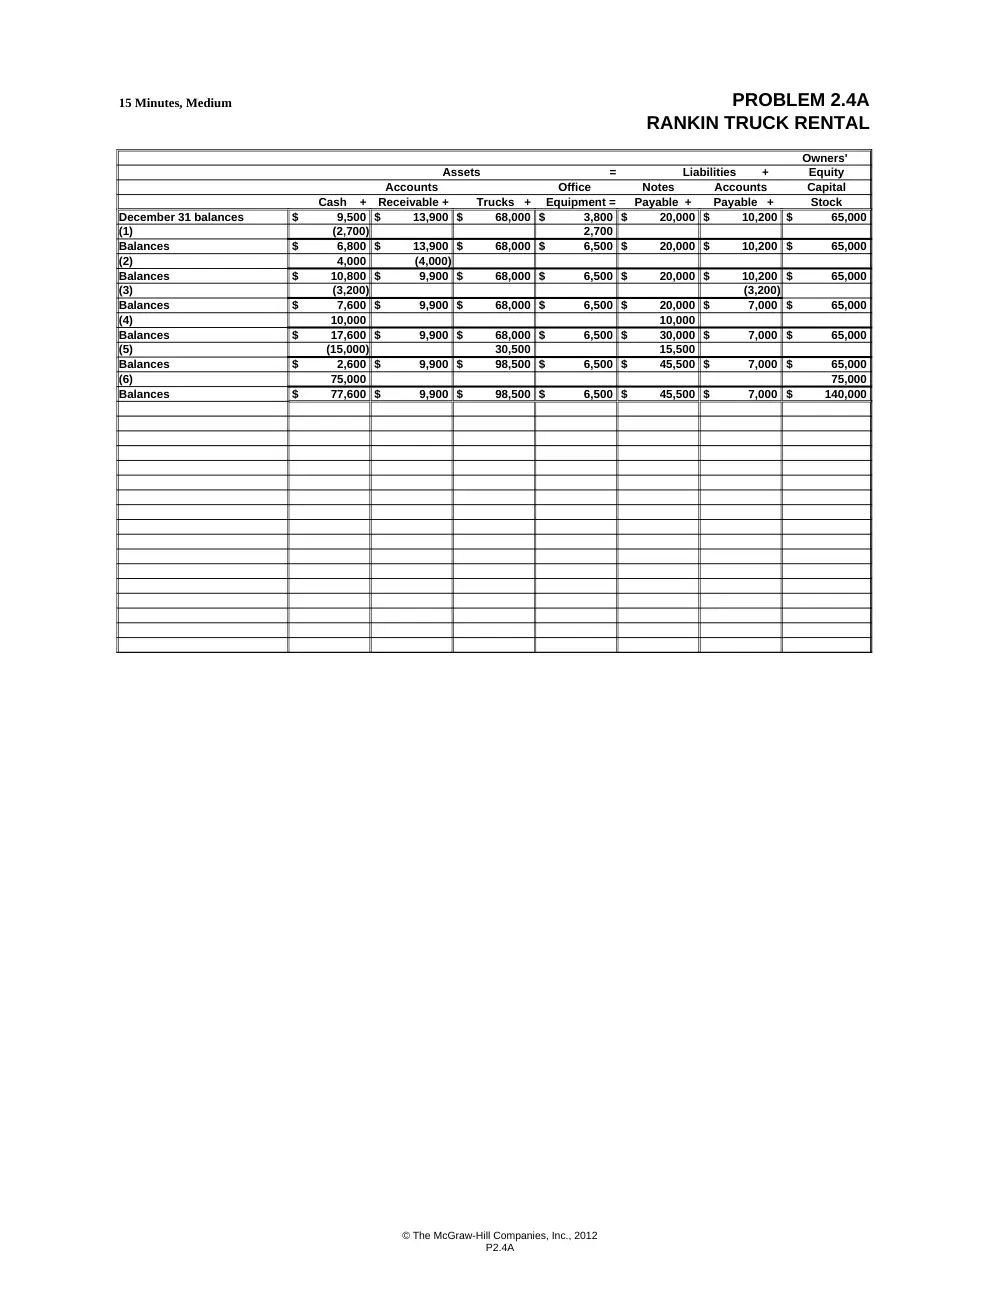
P2.4A
15 Minutes, Medium
PROBLEM 2.4A
RANKIN TRUCK RENTAL
Owners'
Assets
= Liabilities +
Equity
Accounts
Office
Notes
Accounts
Capital
Cash + Receivable + Trucks + Equipment = Payable + Payable +
Stock
December 31 balances
$ 9,500 $ 13,900 $ 68,000 $ 3,800 $ 20,000 $ 10,200 $ 65,000
(1)
(2,700)
2,700
Balances
$ 6,800 $ 13,900 $ 68,000 $ 6,500 $ 20,000 $ 10,200 $ 65,000
(2)
4,000 (4,000)
Balances
$ 10,800 $ 9,900 $ 68,000 $ 6,500 $ 20,000 $ 10,200 $ 65,000
(3)
(3,200)
(3,200)
Balances
$ 7,600 $ 9,900 $ 68,000 $ 6,500 $ 20,000 $ 7,000 $ 65,000
(4)
10,000
10,000
Balances
$ 17,600 $ 9,900 $ 68,000 $ 6,500 $ 30,000 $ 7,000 $ 65,000
(5)
(15,000)
30,500
15,500
Balances
$ 2,600 $ 9,900 $ 98,500 $ 6,500 $ 45,500 $ 7,000 $ 65,000
(6)
75,000
75,000
Balances
$ 77,600 $ 9,900 $ 98,500 $ 6,500 $ 45,500 $ 7,000 $ 140,000
© The McGraw-Hill Companies, Inc., 2012
P2.10A
30 Minutes, Strong
PROBLEM 2.10A
a.
BIG SCREEN SCRIPTS
BIG SCREEN SCRIPTS
Balance Sheet
November 30, 2011
Assets
Liabilities & Owner's Equity
Cash
$ 3,940
Liabilities:
Notes receivable
2,200
Notes payable
$ 73,500
Accounts receivable
2,450
Accounts payable
32,700
Land
39,000
Total liabilities
$ 106,200
Building
54,320
Owner's equity:
Office furniture*
12,825
Capital stock
5,000
Retained earnings *
3,535
Total
$ 114,735
Total
$ 114,735
* $8,850 + $6,500 - $2,525.
* Total assets ($114,735), Less (Total Liabilities, $106,200, + Capital Stock, $5,000)
b. (1)
(2)
(3)
(4)
(5)
(6)
(7)
The cash in Pippin’s personal savings account is not an asset of the business entity Big Screen
Scripts and should not appear in the balance sheet of the business. The money on deposit in the
business bank account ($3,400) and in the company safe ($540) constitute cash owned by the
business. Thus, the cash owned by the business at November 30 is $3,940.
The years-old IOU does not qualify as a business asset for two reasons. First, it does not belong
to the business entity. Second, it appears to be uncollectible. A receivable that cannot be
collected is not viewed as an asset, as it represents no future economic benefit.
The total amount to be included in “Office furniture” for the rug is $9,400, the total cost,
regardless of whether this amount was paid in cash. Consequently, “Office furniture” should be
increased by $6,500. The $6,500 liability arising from the purchase of the rug came into
existence prior to the balance sheet date and must be added to the "Notes payable" amount.
The computer is no longer owned by Big Screen Scripts and therefore cannot be included in the
assets. To do so would cause an overstatement of both assets and owner's equity. The “Office
furniture” amount must be reduced by $2,525.
The $22,400 described as “Other assets” is not an asset, because there is no valid legal claim or
any reasonable expectation of recovering the income taxes paid. Also, the payment of federal
income taxes by Pippin was not a business transaction by Big Screen Scripts. If a refund were
obtained from the government, it would come to Pippin personally, not to the business entity.
The proper valuation for the land is its historical cost of $39,000, the amount established by the
transaction in which the land was purchased. Although the land may have a current fair value in
excess of its cost, the offer by the friend to buy the land if Pippin would move the building
appears to be mere conversation rather than solid, verifiable evidence of the fair value of the
land. The "cost principle," although less than perfect, produces far more reliable financial
statements than would result if the owners could "pull figures out of the air" in recording asset
values.
The accounts payable should be limited to the debts of the business, $32,700, and should not
include Pippin’s personal liabilities.