
ACCT 210 Homework Chapter 3, Fall 2011
American University of Beirut · Financial Accounting · 13 pages


Showing the first 10 of 13 pages. Download the PDF to see all of it.
More ACCT 210 files
- Drop Quiz Chapter 7 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 11 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 13 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 2 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 3 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 4 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 5 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 6 Quiz Questions · Summer 2017ChapterView
Show the text of this chapter
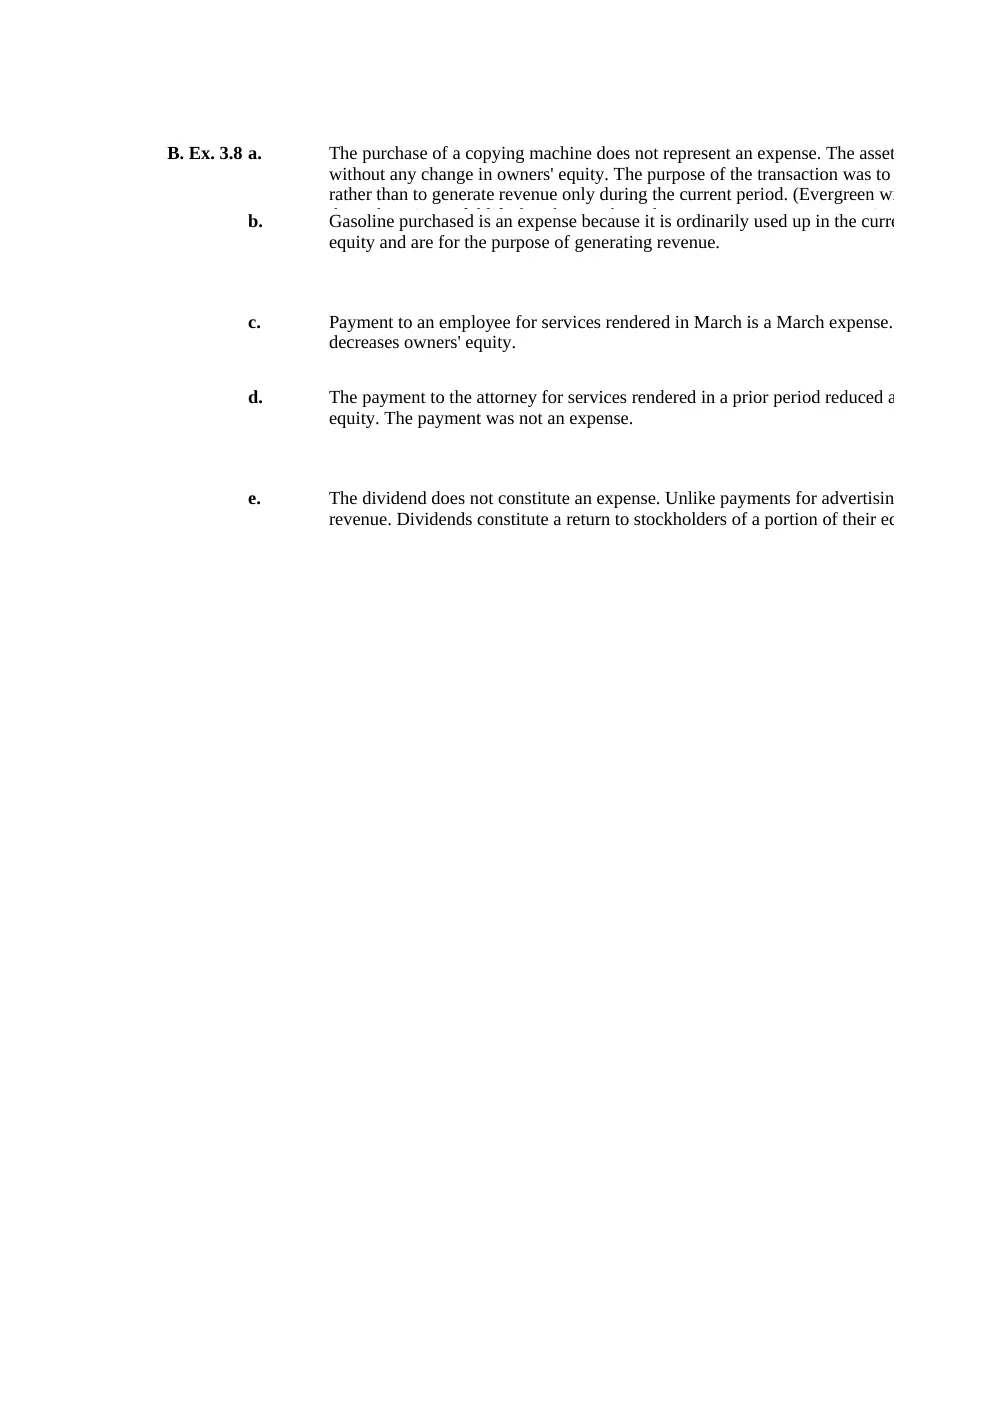
B. Ex. 3.8 a.
b.
c.
d.
e.
The purchase of a copying machine does not represent an expense. The asset Cash is excha
without any change in owners' equity. The purpose of the transaction was to obtain the use
rather than to generate revenue only during the current period. (Evergreen will recognize de
throughout its useful life, but the purchase does not represent an expense in March. Deprec
Gasoline purchased is an expense because it is ordinarily used up in the current period. The
equity and are for the purpose of generating revenue.
Payment to an employee for services rendered in March is a March expense. Such a payme
decreases owners' equity.
The payment to the attorney for services rendered in a prior period reduced an existing liab
equity. The payment was not an expense.
The dividend does not constitute an expense. Unlike payments for advertising, rent, and sup
revenue. Dividends constitute a return to stockholders of a portion of their equity in the bus
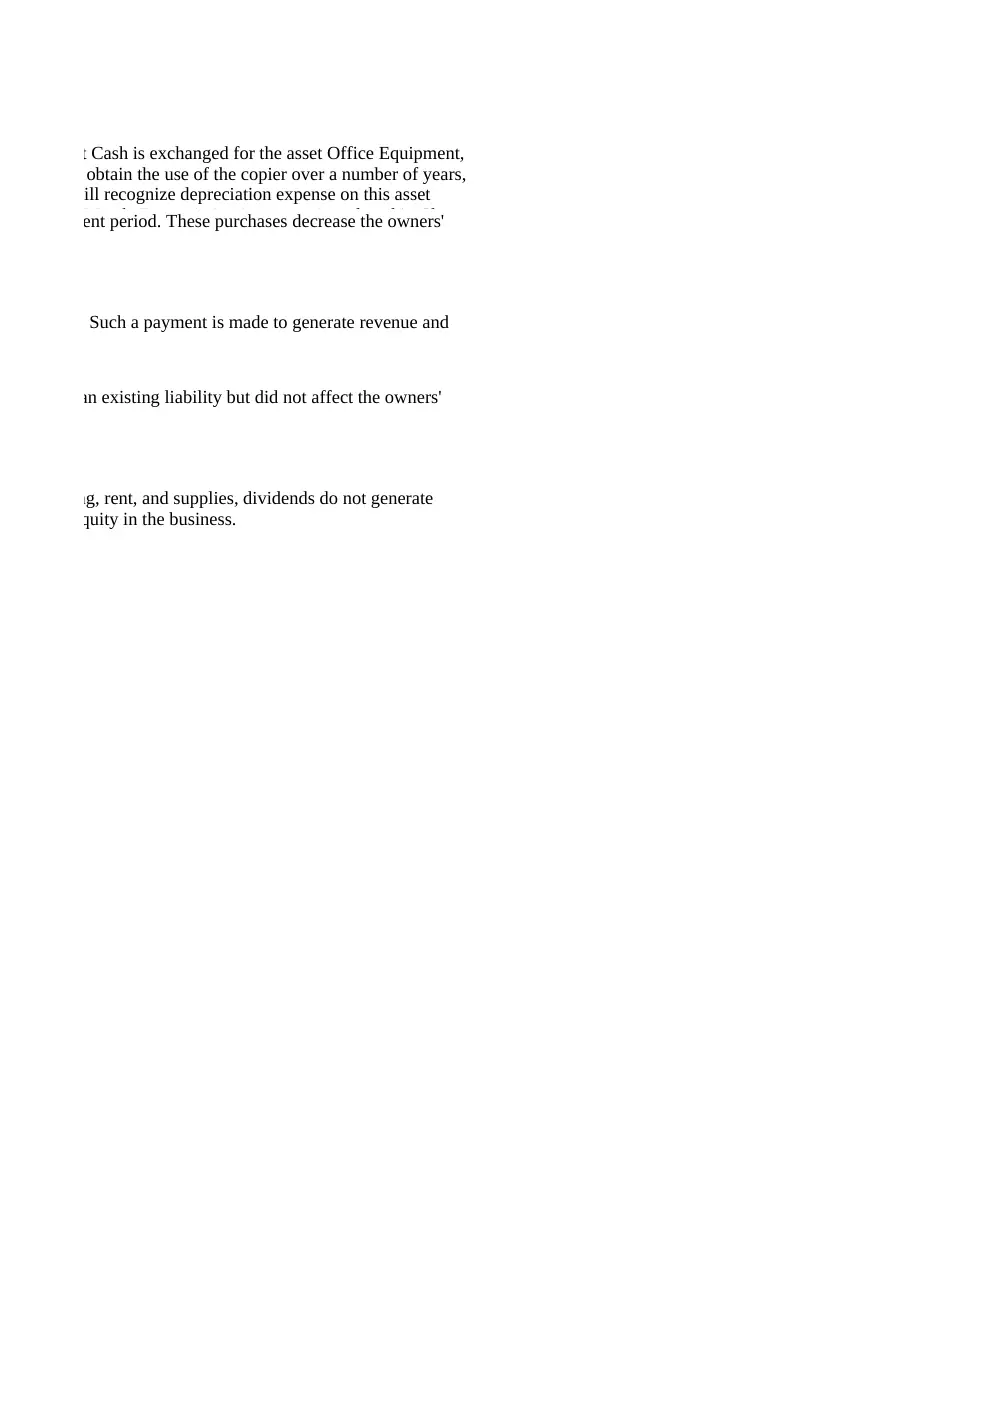
e. The asset Cash is exchanged for the asset Office Equipment,
ction was to obtain the use of the copier over a number of years,
Evergreen will recognize depreciation expense on this asset
expense in March. Depreciation issues are introduced in Chapter
p in the current period. These purchases decrease the owners'
ch expense. Such a payment is made to generate revenue and
od reduced an existing liability but did not affect the owners'
or advertising, rent, and supplies, dividends do not generate
n of their equity in the business.
B. Ex. 3.9
Revenue is recognized when it is earned, not necessarily when cash is received. Thus, the a
$800,000 in its October income statement (of which $500,000 was collected in September a
October).
ash is received. Thus, the airline will recognize revenue of
as collected in September and $300,000 was collected in
B.
Ex.
3.10
Expenses are recognized when they are incurred, not necessarily when cash is paid. Thus, t
of $24,000 in its May income statement (of which $15,000 was paid in May and $9,000 wa
when cash is paid. Thus, the company will report salary expense
paid in May and $9,000 was paid in June).
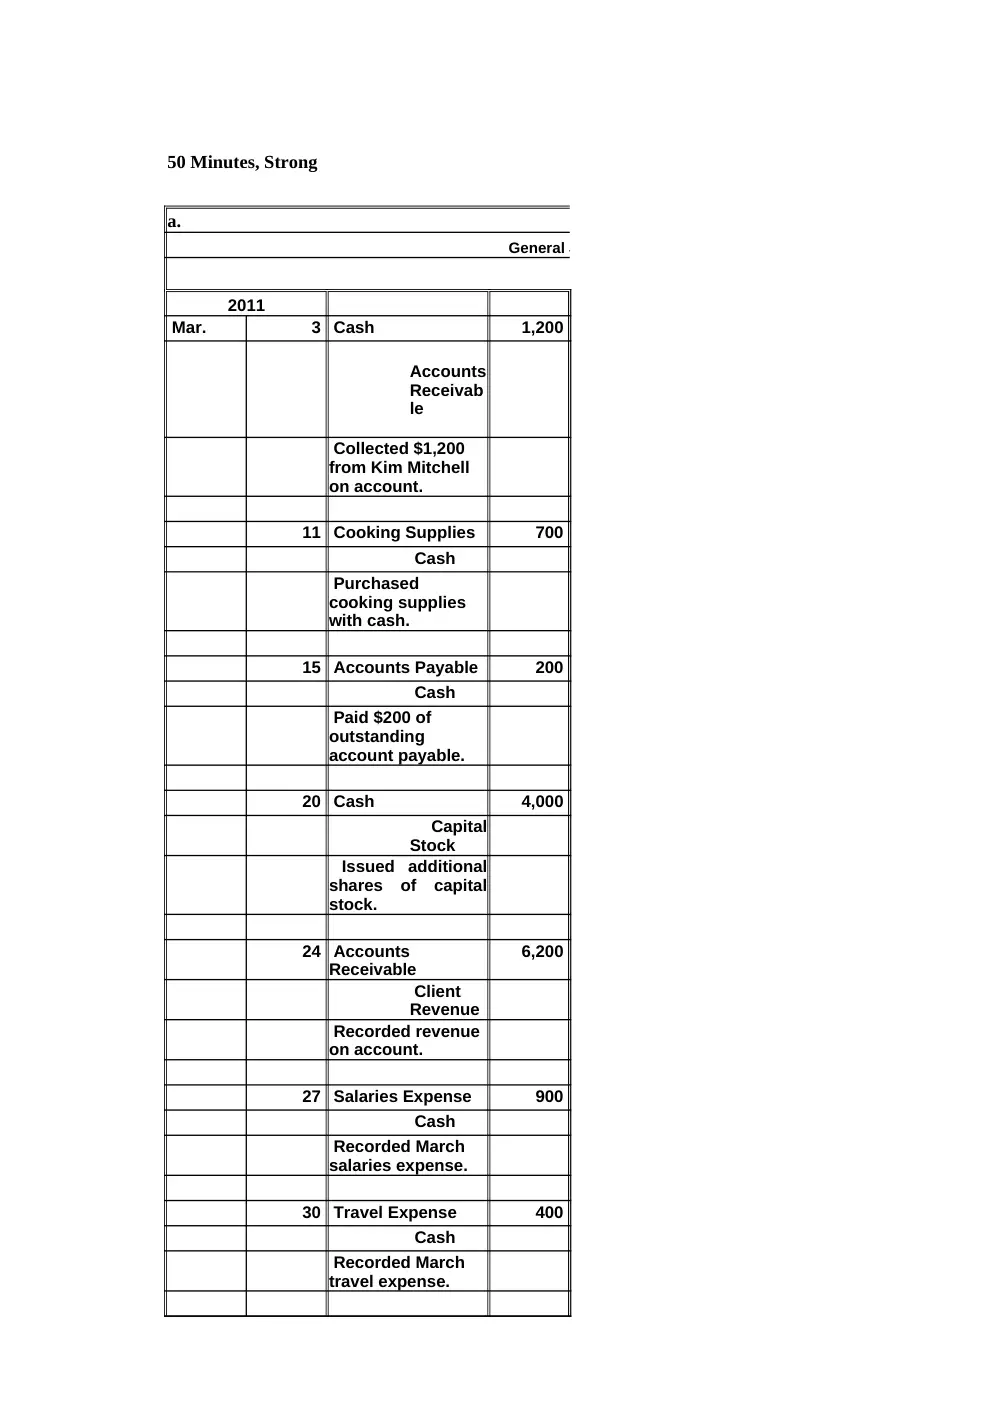
50 Minutes, Strong
PROBLEM 3.7B
AHUNA, INC.
a.
General Journal
2011
Mar.
3 Cash
1,200
11 Cooking Supplies
700
Cash
15 Accounts Payable 200
Cash
20 Cash
4,000
24
6,200
27 Salaries Expense
900
Cash
30 Travel Expense
400
Cash
Accounts
Receivab
le
Collected $1,200
from Kim Mitchell
on account.
Purchased
cooking supplies
with cash.
Paid $200 of
outstanding
account payable.
Capital
Stock
Issued additional
shares of capital
stock.
Accounts
Receivable
Client
Revenue
Recorded revenue
on account.
Recorded March
salaries expense.
Recorded March
travel expense.
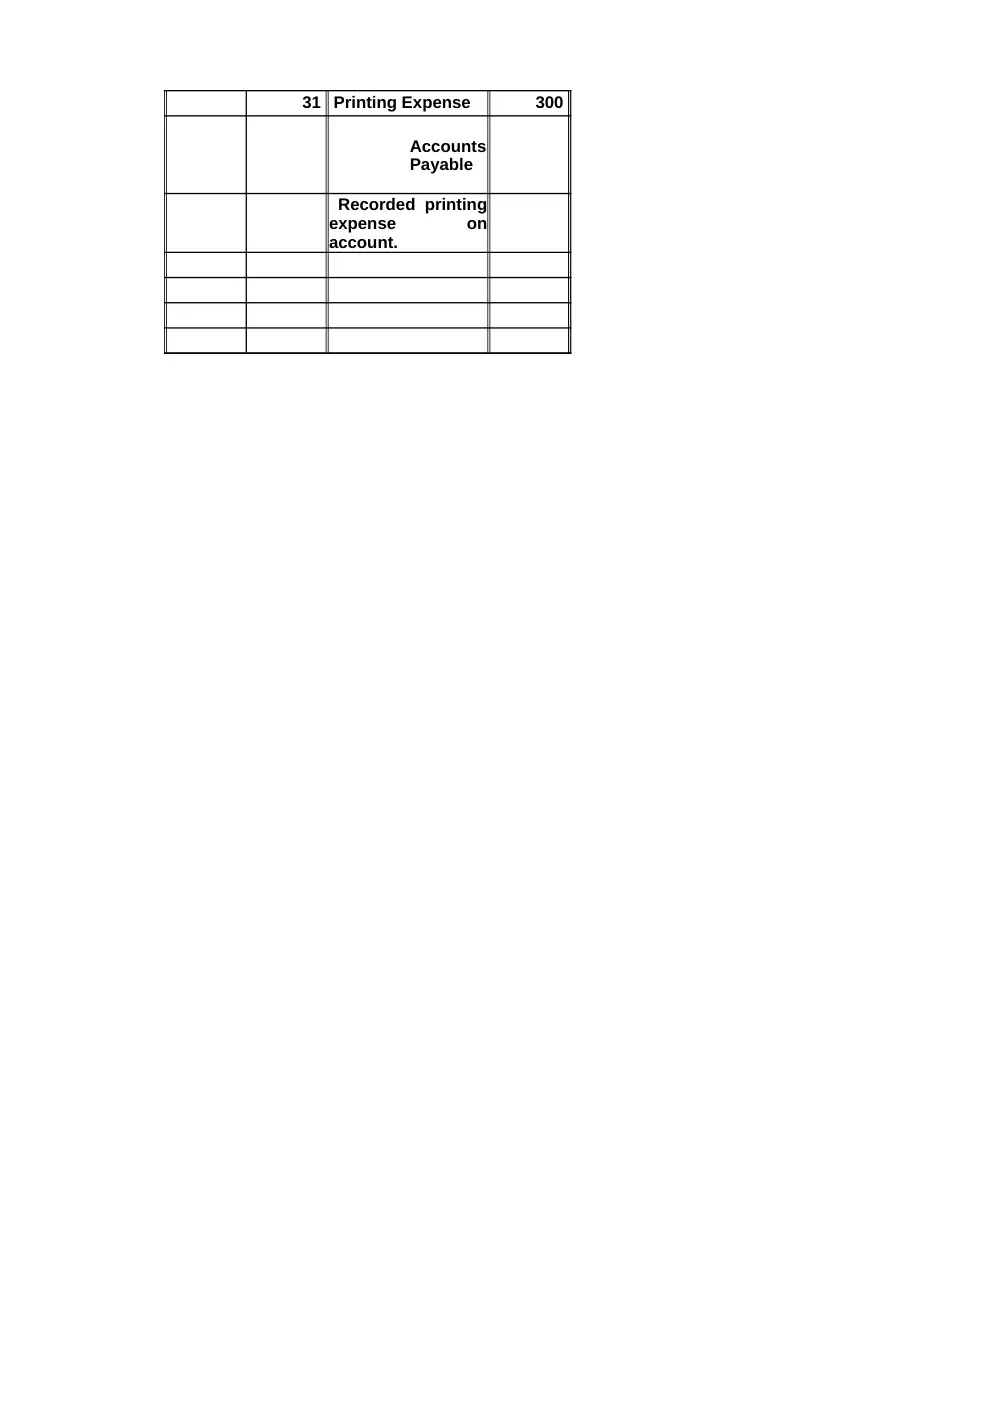
31 Printing Expense
300
Accounts
Payable
Recorded printing
expense
on
account.
PROBLEM 3.7B
AHUNA, INC.
General Journal
1,200
700
200
4,000
6,200
900
400
300
PROBLEM 3.
AHUNA, INC. (continue
Cash
Accounts Receivable
5,700
Mar. 11
700
1,800
Mar. 3
1,200
Mar. 15
200
Mar. 24
6,200
Mar. 20
4,000
Mar. 27
900
Mar. 30
400
8,700
6,800
Cooking Supplies
Accounts Payable
800
Mar. 15
200
Mar. 11
700
1,500
Dividends Payable
Dividends
500
500
Mar. 31 ba
500
500
Capital Stock
Retained Earnings
6,000
Mar. 20
4,000
Mar. 31 ba
10,000
Client Revenue
Salaries Expense
5,800
Mar. 1 bal
3,100
Mar. 24
6,200
Mar. 27
900
Mar. 31 ba
12,000
Mar. 31 ba
4,000
Travel Expense
Printing Expense
Mar. 1. bal
1,500
Mar. 1 bal
600
Mar. 30
400
Mar. 31
300
Mar. 31 ba
1,900
Mar. 31 ba
900
Mar. 1
bal.
Mar. 1
bal.
Mar. 31
bal.
Mar. 31
bal.
Mar. 1
bal.
Mar. 31
bal.
Mar. 1
bal.
Mar. 1
bal.
Mar. 31
bal.
Mar. 1
bal.
Mar. 1
bal.
PROBLEM 3.7B
NA, INC. (continued)
ounts Receivable
Mar. 3
1,200
counts Payable
Mar. 1 bal
300
Mar. 31
300
Mar. 31 ba
400
Dividends
ained Earnings
Mar. 1 bal
1,400
Mar. 31 ba
1,400
laries Expense
inting Expense
PROBLEM 3.7B
AHUNA, INC. (concluded)
c.
AHUNA, INC.
Trial Balance
March 31, 2011
Cash
$ 8,700
Accounts receivable
6,800
Cooking supplies
1,500
Accounts payable
$ 400
Dividends payable
500
Dividends
500
Capital stock
10,000
Retained earnings
1,400
Client revenue
12,000
Salaries expense
4,000
Travel expense
1,900
Printing expense
900
$ 24,300 $ 24,300
d.
The company has not paid the dividends it previously declared as evidenced by
the $500 dividends payable liability in the trial balance.