
ACCT 210 Homework Chapter 4, Fall 2011
American University of Beirut · Financial Accounting · 19 pages



Showing the first 10 of 19 pages. Download the PDF to see all of it.
More ACCT 210 files
- Drop Quiz Chapter 7 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 11 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 13 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 2 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 3 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 4 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 5 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 6 Quiz Questions · Summer 2017ChapterView
Show the text of this chapter
30 Minutes, Medium
PROB
MARVELO
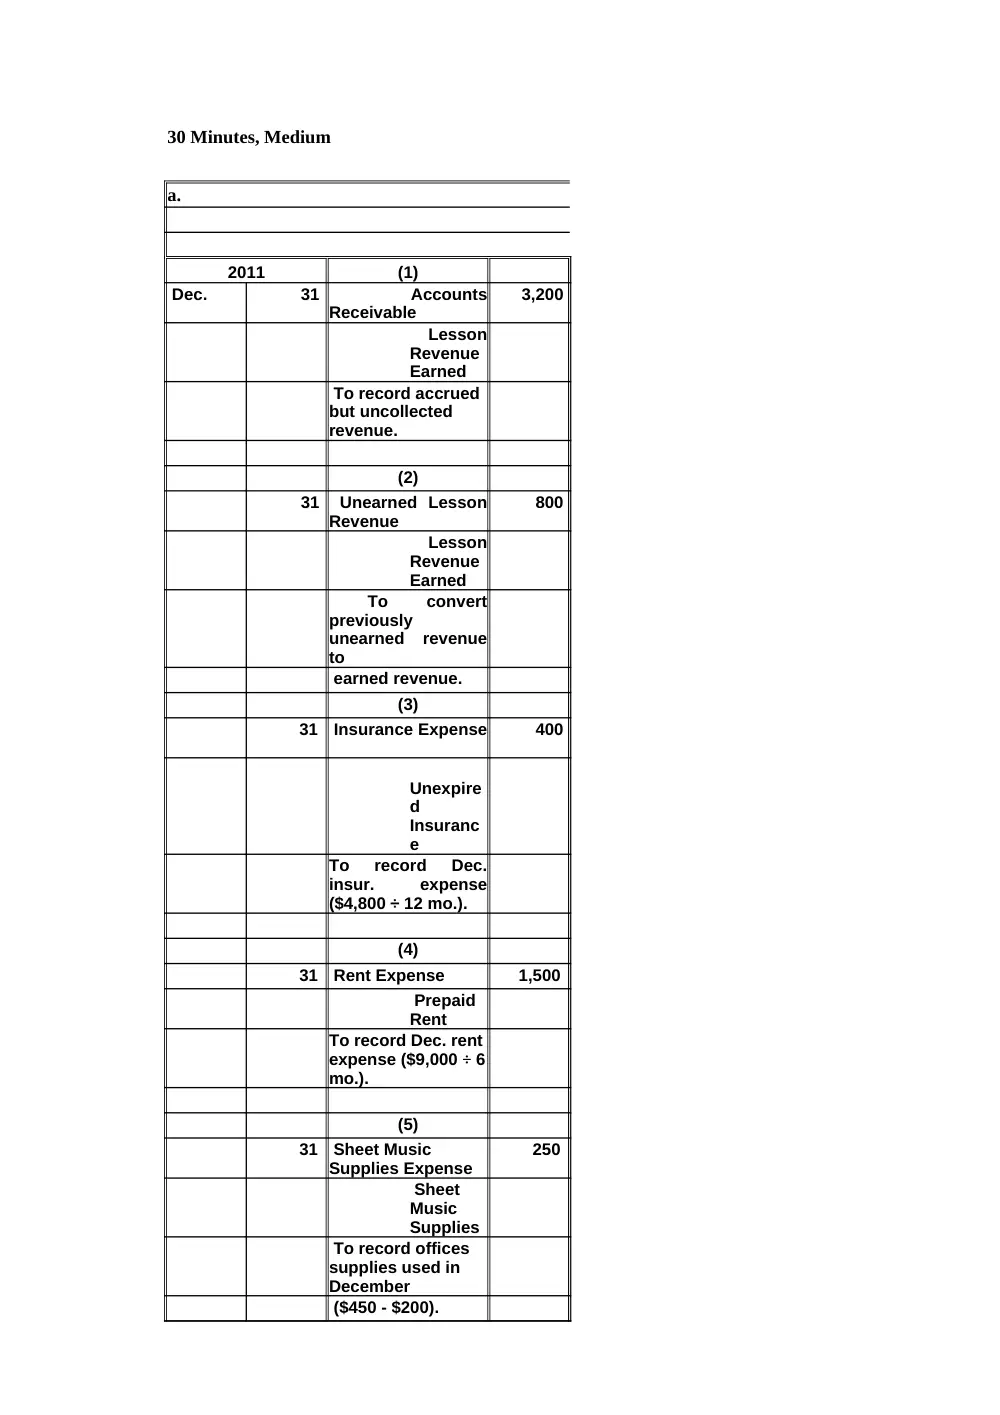
a.
General Journal
(Adjusting Entries)
2011
(1)
Dec.
31
3,200
(2)
31
800
earned revenue.
(3)
31
400
(4)
31 Rent Expense
1,500
(5)
31
250
($450 - $200).
Accounts
Receivable
Lesson
Revenue
Earned
To record accrued
but uncollected
revenue.
Unearned Lesson
Revenue
Lesson
Revenue
Earned
To
convert
previously
unearned
revenue
to
Insurance Expense
Unexpire
d
Insuranc
e
To
record
Dec.
insur.
expense
($4,800 ÷ 12 mo.).
Prepaid
Rent
To record Dec. rent
expense ($9,000 ÷ 6
mo.).
Sheet Music
Supplies Expense
Sheet
Music
Supplies
To record offices
supplies used in
December
(6)
31
3,000
(7)
31 Interest Expense
25
(8)
31 Salaries Expense
3,500
(9)
31
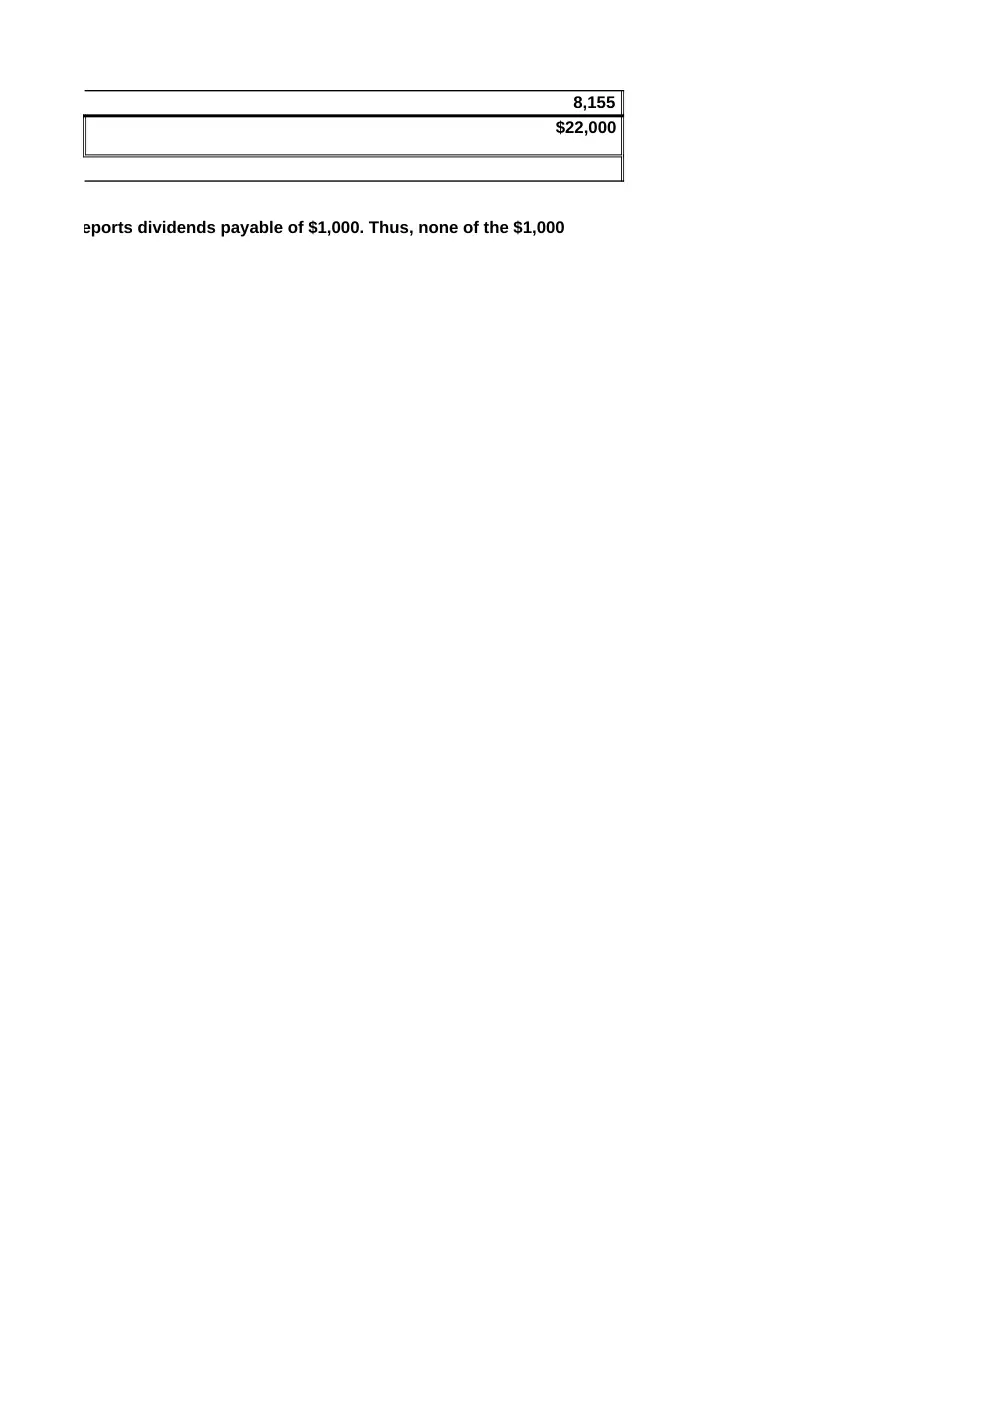
8,155
Depreciation
Expense: Music
Equipment
Accum.
Depreciat
ion:
Music
Equipme
nt
To record
December
depreciation
expense
($180,000 ÷ 60 mo.).
Interest
Payable
To record interest
accrued in
December
($5,000 x 6% x
1/12).
Salaries
Payable
To record accrued
salaries expense in
December.
Income Taxes
Expense
Income
Taxes
Payable
To record income
taxes accrued in
December.
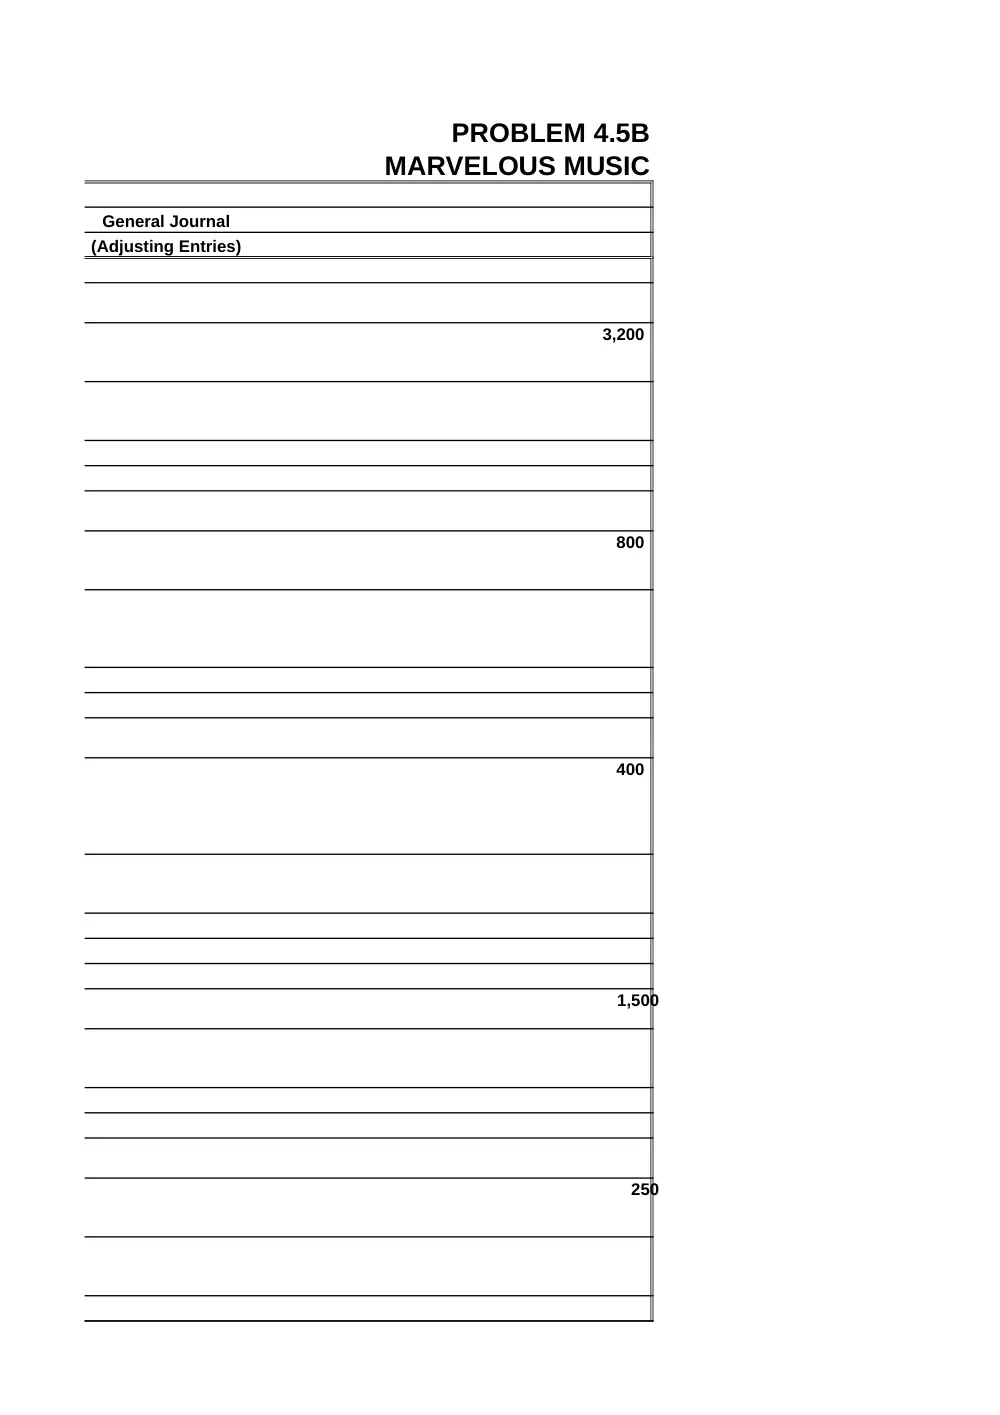
PROBLEM 4.5B
MARVELOUS MUSIC
General Journal
(Adjusting Entries)
3,200
800
400
1,500
250
3,000
25
3,500
8,155
PROBL
MARVELOUS MUSIC (con
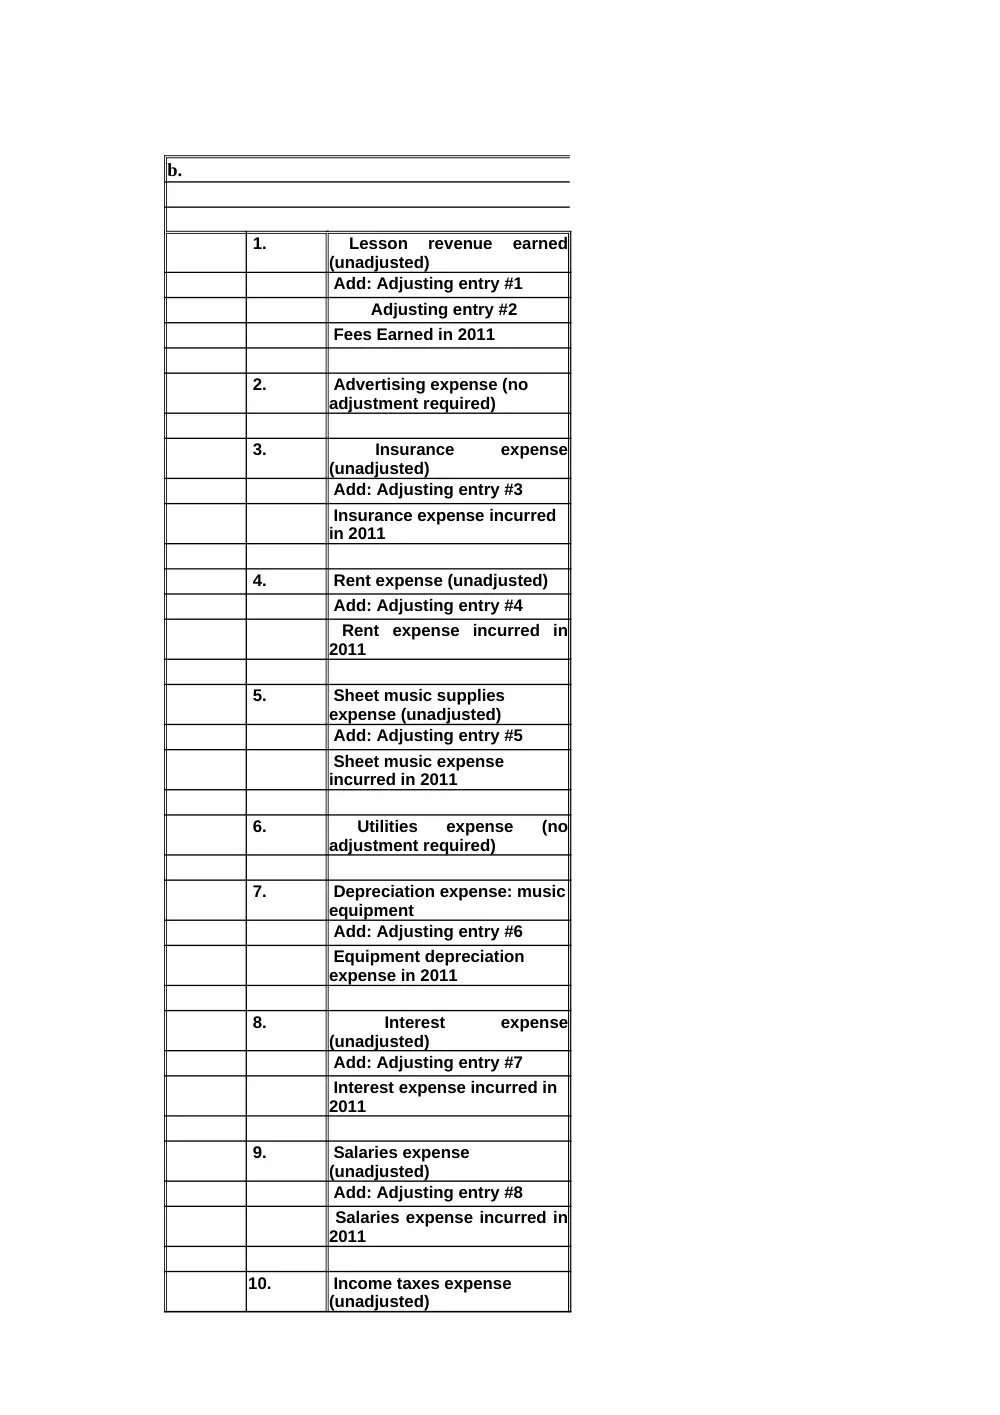
b.
1.
Add: Adjusting entry #1
Adjusting entry #2
Fees Earned in 2011
2.
3.
Add: Adjusting entry #3
4.
Rent expense (unadjusted)
Add: Adjusting entry #4
5.
Add: Adjusting entry #5
6.
7.
Add: Adjusting entry #6
8.
Add: Adjusting entry #7
9.
Add: Adjusting entry #8
10.
Lesson
revenue
earned
(unadjusted)
Advertising expense (no
adjustment required)
Insurance
expense
(unadjusted)
Insurance expense incurred
in 2011
Rent expense incurred in
2011
Sheet music supplies
expense (unadjusted)
Sheet music expense
incurred in 2011
Utilities
expense
(no
adjustment required)
Depreciation expense: music
equipment
Equipment depreciation
expense in 2011
Interest
expense
(unadjusted)
Interest expense incurred in
2011
Salaries expense
(unadjusted)
Salaries expense incurred in
2011
Income taxes expense
(unadjusted)
Add: Adjusting entry #9
c.
Income taxes expense
incurred in 2011
The unadjusted trial balance reports dividends payable of $1,000. Thus, none of the $
dividend has been paid.
PROBLEM 4.5B
MARVELOUS MUSIC (concluded)
$ 154,375
3,200
800
$ 158,375
$ 7,400
$ 4,400
400
$ 4,800
$ 16,500
1,500
$ 18,000
$ 780
250
$ 1,030
$ 5,000
$ 33,000
3,000
$ 36,000
$ 25
25
$ 50
$ 27,500
3,500
$ 31,000
$ 13,845
8,155
$22,000
l balance reports dividends payable of $1,000. Thus, none of the $1,000
paid.
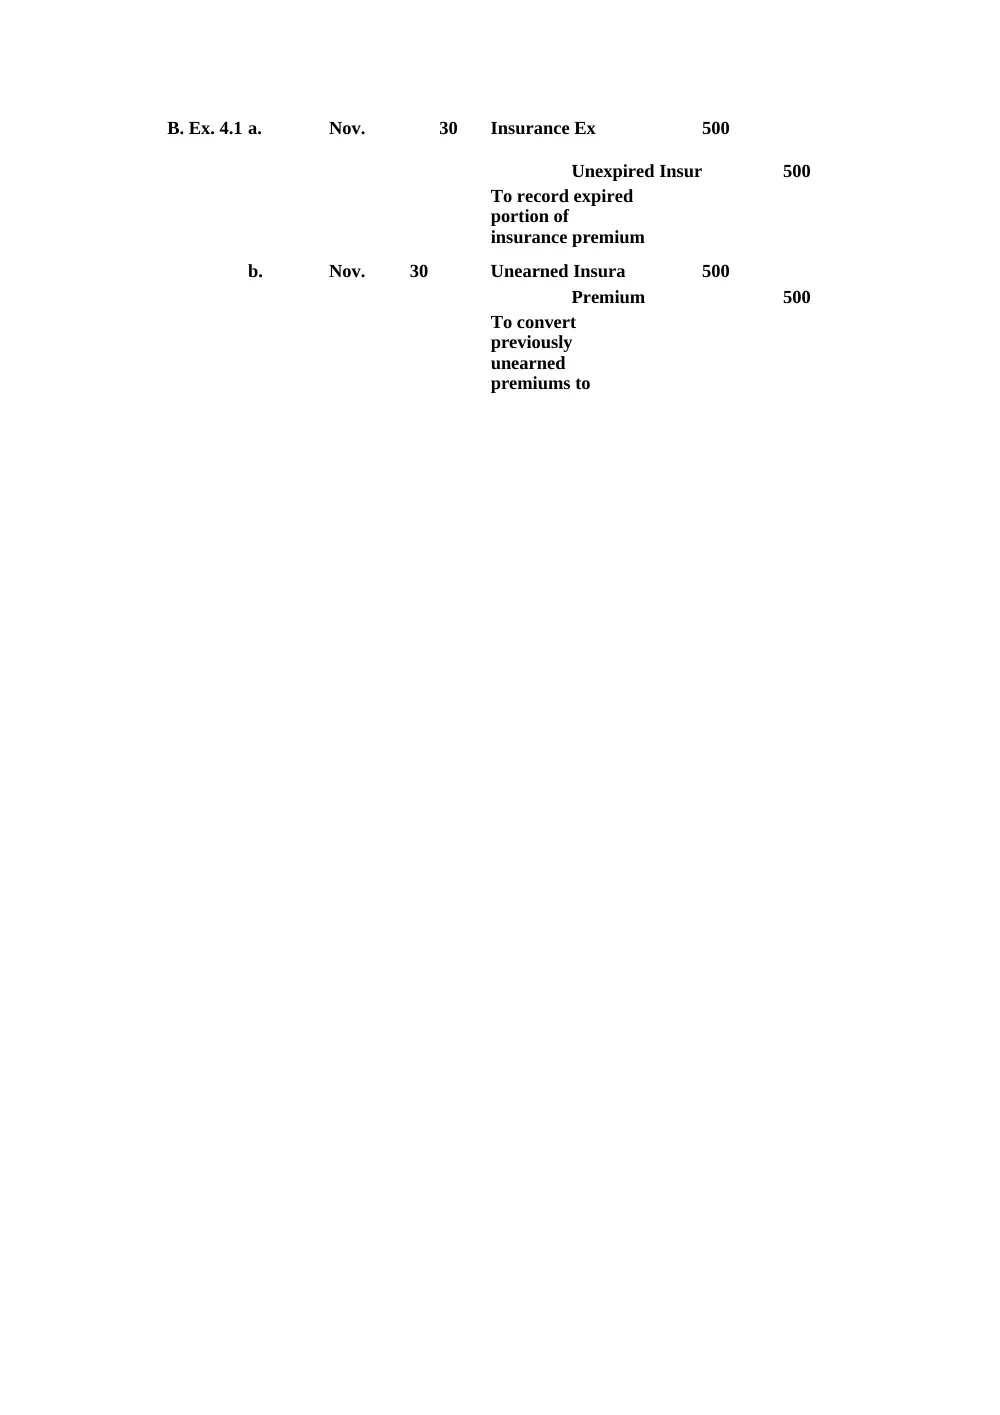
B. Ex. 4.1 a.
Nov.
30
Insurance Ex
500
Unexpired Insur
500
b.
Nov.
30
Unearned Insura
500
Premium
500
To record expired
portion of
insurance premium
To convert
previously
unearned
premiums to
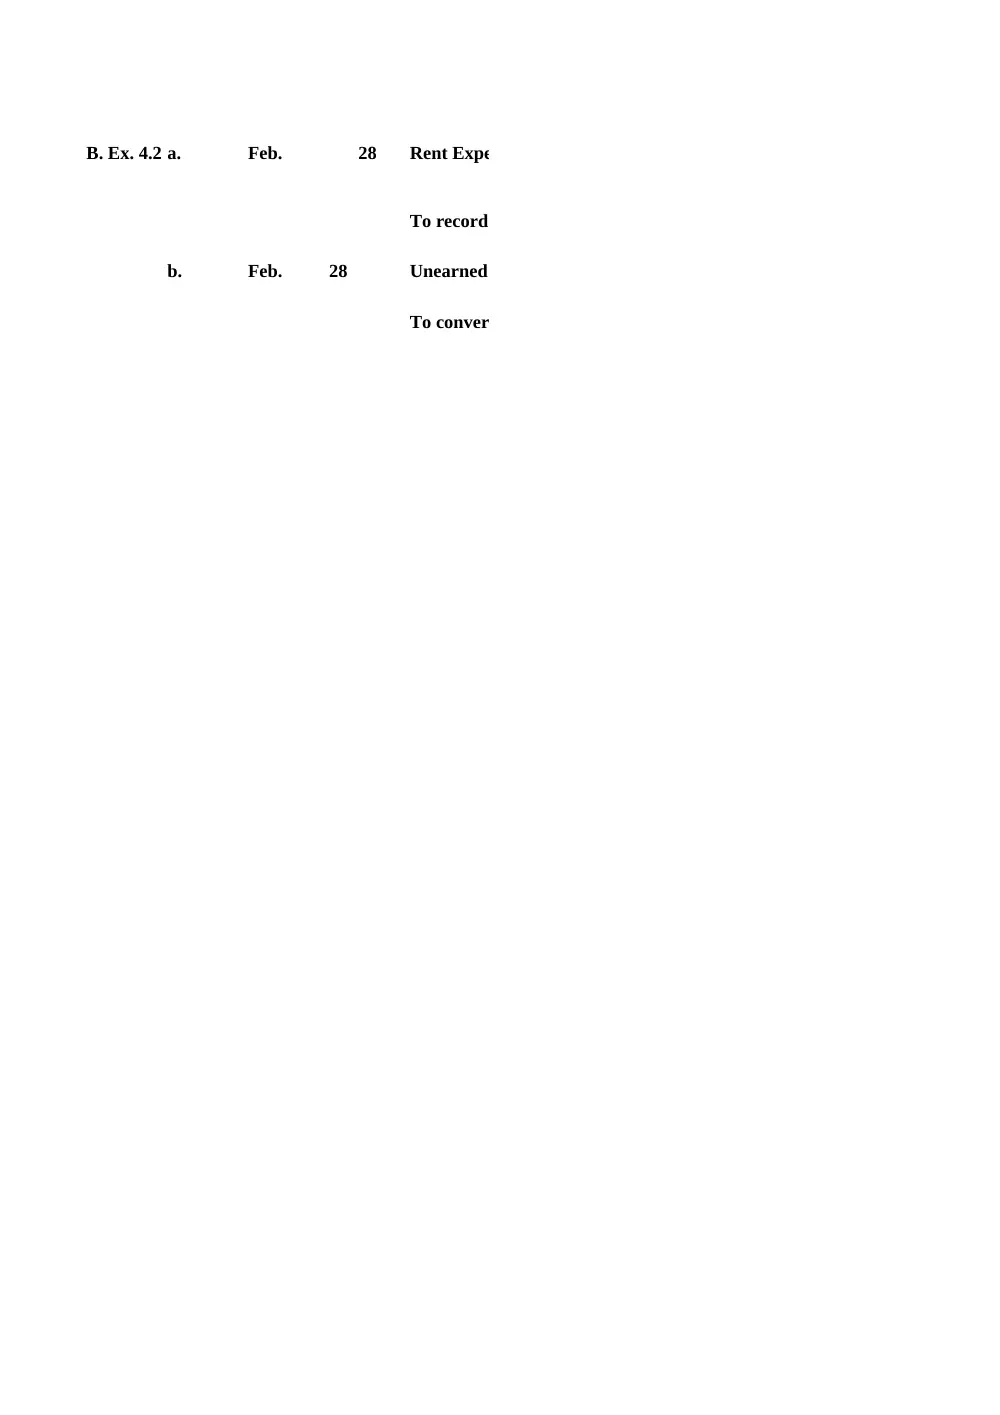
B. Ex. 4.2 a.
Feb.
28
Rent Expense …………………………………………………
To record February rent of $175.
b.
Feb.
28
Unearned Rent Revenue……………………………………………..
To convert previously unearned rent revenue to earned revenue.
Rent Expense …………………………………………………
175
Prepaid Rent ………………………………………………
175
To record February rent of $175.
Unearned Rent Revenue……………………………………………..
175
Rent Revenue Earned …………………………………………
175
To convert previously unearned rent revenue to earned revenue.
B. Ex. 4.3
Mar.
31
Office Suppli
1,100
Office
1,100
To record March
office supplies
expense ($900 +
B. Ex. 4.4 a.
Dec.
31
Depreciation Expense: Equipment…………………………….
To record December depreciation expense $72,000 ÷ 8 years x 1/1
b.
The equipment's accumulated depreciation reported in the balance sheet on Dec
2011, is $54,000 ($72,000 ÷ 8-year life x 6 years of depreciation = $54,000).
Depreciation Expense: Equipment…………………………….
750
Accumulated Depreciation: Equipment …………………………
750
To record December depreciation expense $72,000 ÷ 8 years x 1/12 = $750).
ccumulated depreciation reported in the balance sheet on December 31,
2,000 ÷ 8-year life x 6 years of depreciation = $54,000).
B. Ex. 4.5
Accounts Receivable
3,340
Client Service
Account Hours Rate A
#4067
10 $85 $ 850
#3940
14 $75 1,050
#1852
To record earned but unbilled
and unrecorded client service
revenue:
Billable
16 $90 1,440
$ 3,340
3,340
a.
b.
c.
Two ways in which the concept of materiality may save time and effort for accountant
1.
2.
B.
Ex.
4.10
Materiality refers to the relative importance of an item. An item is material if knowledg
reasonably influence the decisions of users of financial statements. If an item is immat
definition it is not relevant to decision makers.
Accountants must account for material items in the manner required by generally acc
accounting principles. However, immaterial items may be accounted for in the most co
economical manner.
Whether a specific dollar amount is “material” depends upon the (1) size of the amoun
of the item. In evaluating the size of a dollar amount, accountants consider the amoun
the size of the organization.
Based solely upon a dollar amount, $2,500 is not material in relation to the financial st
large, publicly owned corporation. For a small business however, this amount could b
In addition to considering the size of a dollar amount, accountants must also consider
item. The nature of an item may make the item “material” to users of the financial sta
regardless of its dollar amount. Examples might include bribes paid to government off
company assets, or other illegal acts committed by management.
In summary, one cannot say whether $2,500 is a material amount. The answer depend
related circumstances.
Adjusting entries may be based upon estimated amounts if there is little or
that the use of an estimate will result in material error. For example, an adj
reflect the amount of supplies used may be based on an estimate of the cost
remaining on hand.
Adjusting entries need not be made to accrue immaterial amounts of unreco
or unrecorded revenue. For example, no adjusting entries normally are mad
utility expense payable at year-end.
ity may save time and effort for accountants are:
e of an item. An item is material if knowledge of it might
of financial statements. If an item is immaterial, by
ers.
ms in the manner required by generally accepted
al items may be accounted for in the most convenient and
rial” depends upon the (1) size of the amount and (2) nature
ar amount, accountants consider the amount in relation to
is not material in relation to the financial statements of a
mall business however, this amount could be material.
ar amount, accountants must also consider the nature of the
item “material” to users of the financial statements
might include bribes paid to government officials, theft of
itted by management.
0 is a material amount. The answer depends upon the
upon estimated amounts if there is little or no possibility
esult in material error. For example, an adjusting entry to
ed may be based on an estimate of the cost of supplies
ade to accrue immaterial amounts of unrecorded expenses
mple, no adjusting entries normally are made to record
nd.
Ex. 4.9
a.
May
1
Cash ………………
300,000
Notes Payable
300,000
May
31
Interest Expe
3,000
Interes
3,000
b.
May
1
Prepaid Ren
180,000
Cash
180,000
Paid rent for six months at $30,000 per month.
May
31
Rent Expense
30,000
Prepai
30,000
To record rent expense for the
c.
May
2
Cash ……………
910,000
Unearned
910,000
May
31
Unearned Admis
260,000
Admissi
260,000
d.
May
4
No entry required.
Obtained a three-
month loan from
National Bank at
To record interest
expense for May on
note
payable to National
Sold season tickets
to the 70-day racing
season.
To record
admissions revenue
from the 20
racing days in May