
ACCT 210 Homework Chapter 7, Fall 2011
American University of Beirut · Financial Accounting · 10 pages


More ACCT 210 files
- Drop Quiz Chapter 7 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 11 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 13 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 2 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 3 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 4 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 5 Quiz Questions · Summer 2017ChapterView
- Drop Quiz Chapter 6 Quiz Questions · Summer 2017ChapterView
Show the text of this chapter
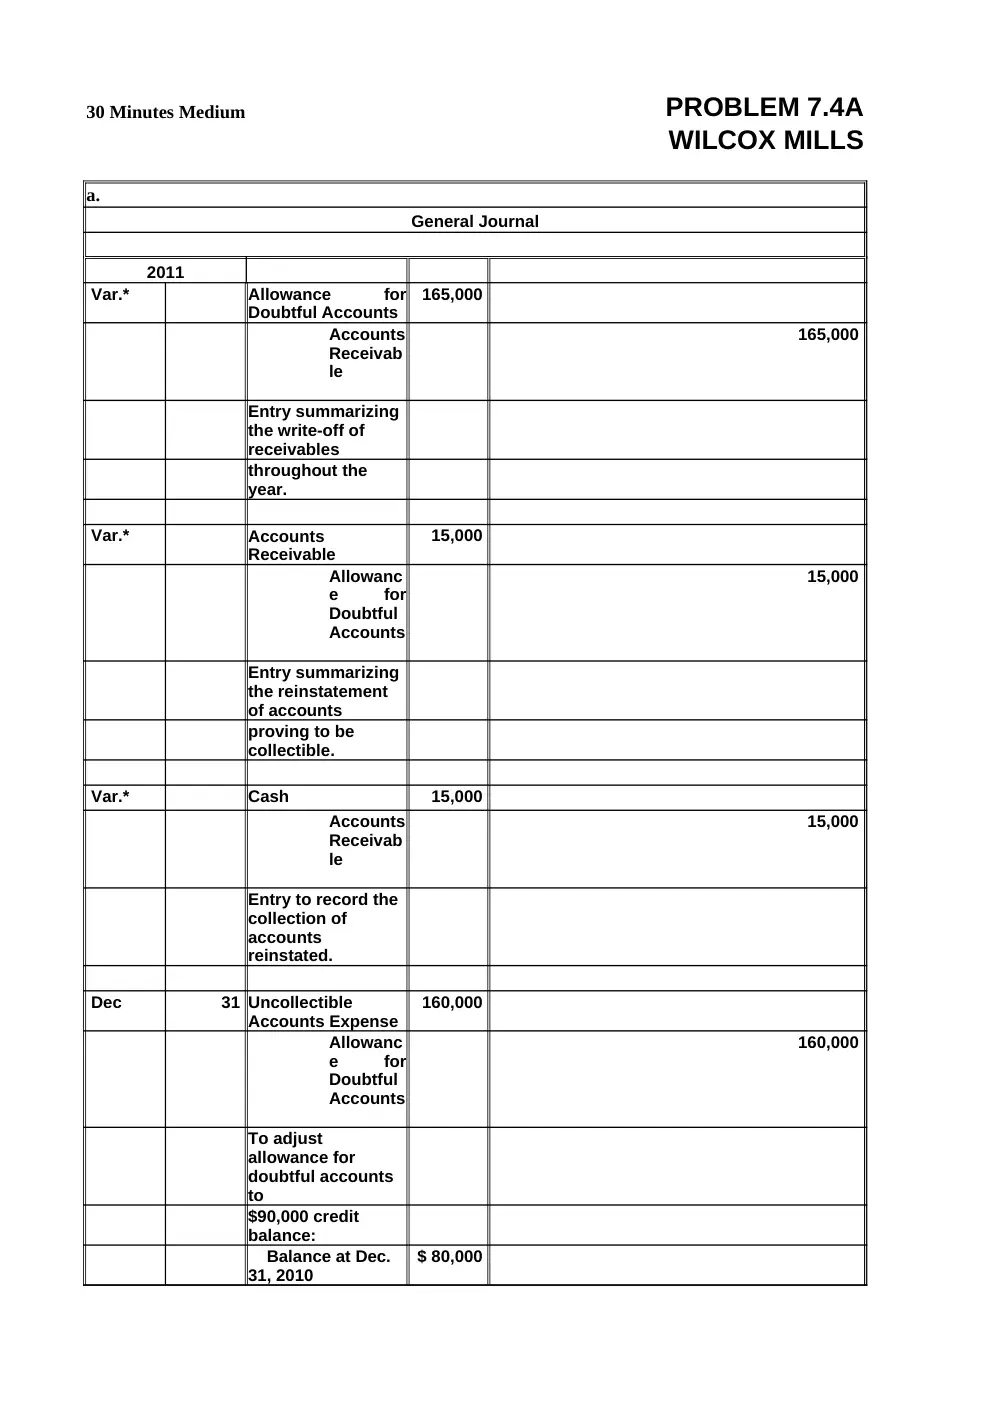
30 Minutes Medium
PROBLEM 7.4A
WILCOX MILLS
a.
General Journal
2011
Var.*
165,000
165,000
Var.*
15,000
15,000
Var.*
Cash
15,000
15,000
Dec
31
160,000
160,000
$ 80,000
Allowance
for
Doubtful Accounts
Accounts
Receivab
le
Entry summarizing
the write-off of
receivables
throughout the
year.
Accounts
Receivable
Allowanc
e
for
Doubtful
Accounts
Entry summarizing
the reinstatement
of accounts
proving to be
collectible.
Accounts
Receivab
le
Entry to record the
collection of
accounts
reinstated.
Uncollectible
Accounts Expense
Allowanc
e
for
Doubtful
Accounts
To adjust
allowance for
doubtful accounts
to
$90,000 credit
balance:
Balance at Dec.
31, 2010
(165,000)
15,000
(70,000)
90,000
###
*The first three entries summarize entries occurring at various dates throughout 2011.
b.
Less: Write-offs
during 2011
Add: Accounts
reinstated
Unadjusted
balance (debit
balance)
Desired balance
(credit)
Required
adjustment
($70,000 + $90,000)
A case can probably be made that the allowance is unreasonably low. The amount of the
allowance at the end of 2010 was $80,000, but $165,000 were written off during the
following year which may imply that the allowance should have been higher. A counter
argument, which may justify the $80,000 balance, is that the allowance at the end of a
year is not necessarily intended to provide for all accounts that will be written off during
the coming year. Rather, it represents only the portion of the receivables existing at
year-end estimated to be uncollectible.
As Wilcox Mills sells on 30-day terms, it should turn over its receivables about 12 times
each year. Thus, the year-end receivables should equal only about 1/12 of a year’s credit
sales, and the balance in the allowance should provide for about 1/12 of the accounts
written off during the year.
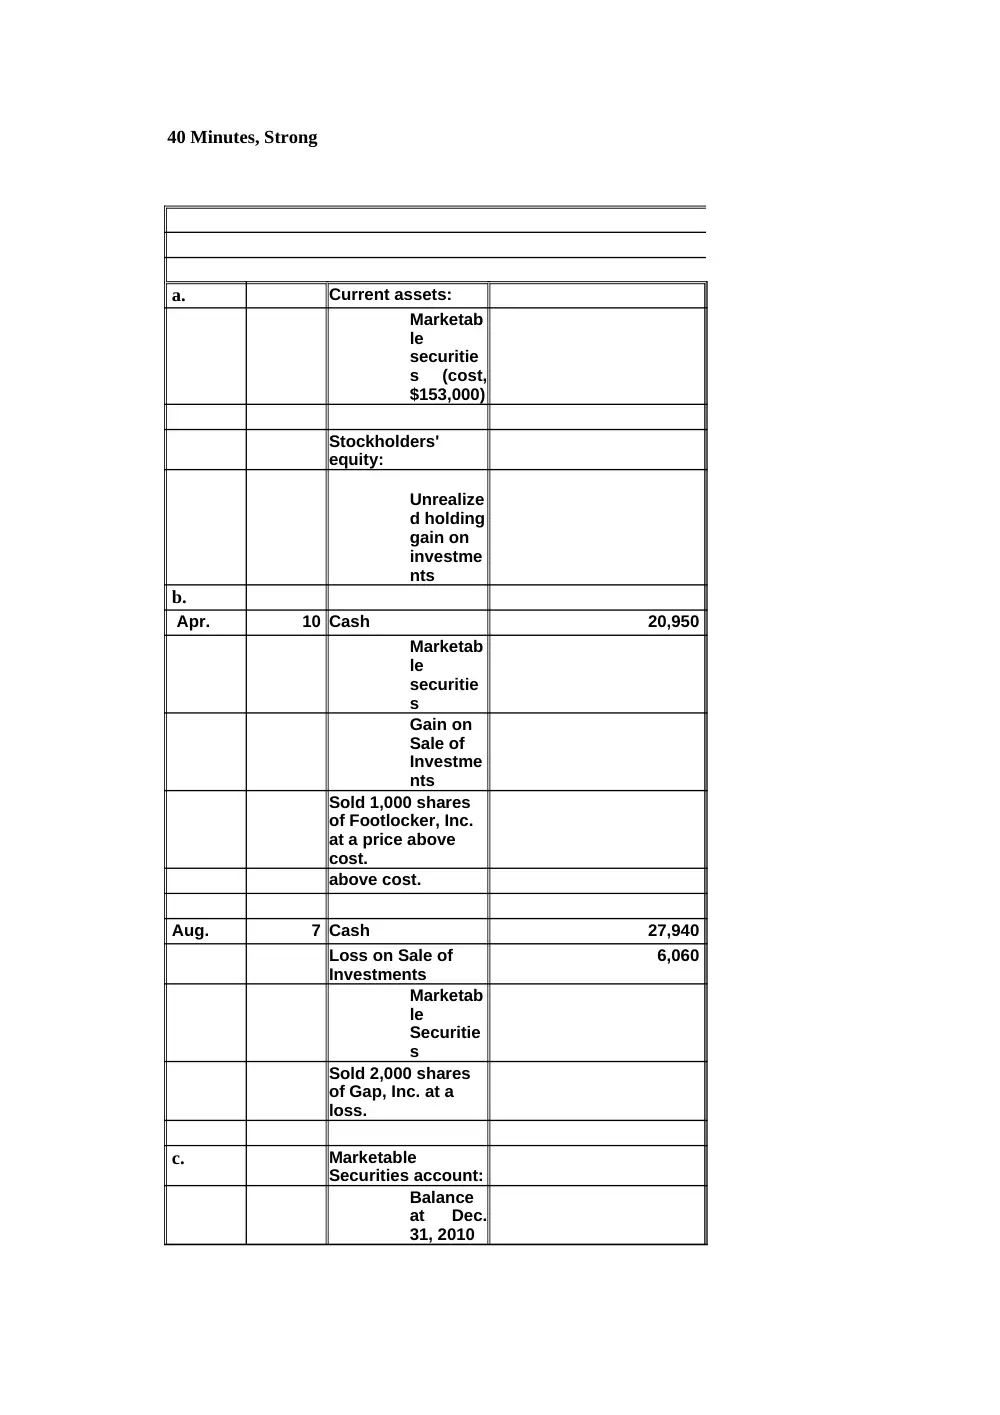
40 Minutes, Strong
WESTON MANU
a.
Current assets:
b.
Apr.
10 Cash
20,950
above cost.
Aug.
7 Cash
27,940
6,060
c.
Marketab
le
securitie
s
(cost,
$153,000)
Stockholders'
equity:
Unrealize
d holding
gain on
investme
nts
Marketab
le
securitie
s
Gain on
Sale of
Investme
nts
Sold 1,000 shares
of Footlocker, Inc.
at a price above
cost.
Loss on Sale of
Investments
Marketab
le
Securitie
s
Sold 2,000 shares
of Gap, Inc. at a
loss.
Marketable
Securities account:
Balance
at
Dec.
31, 2010
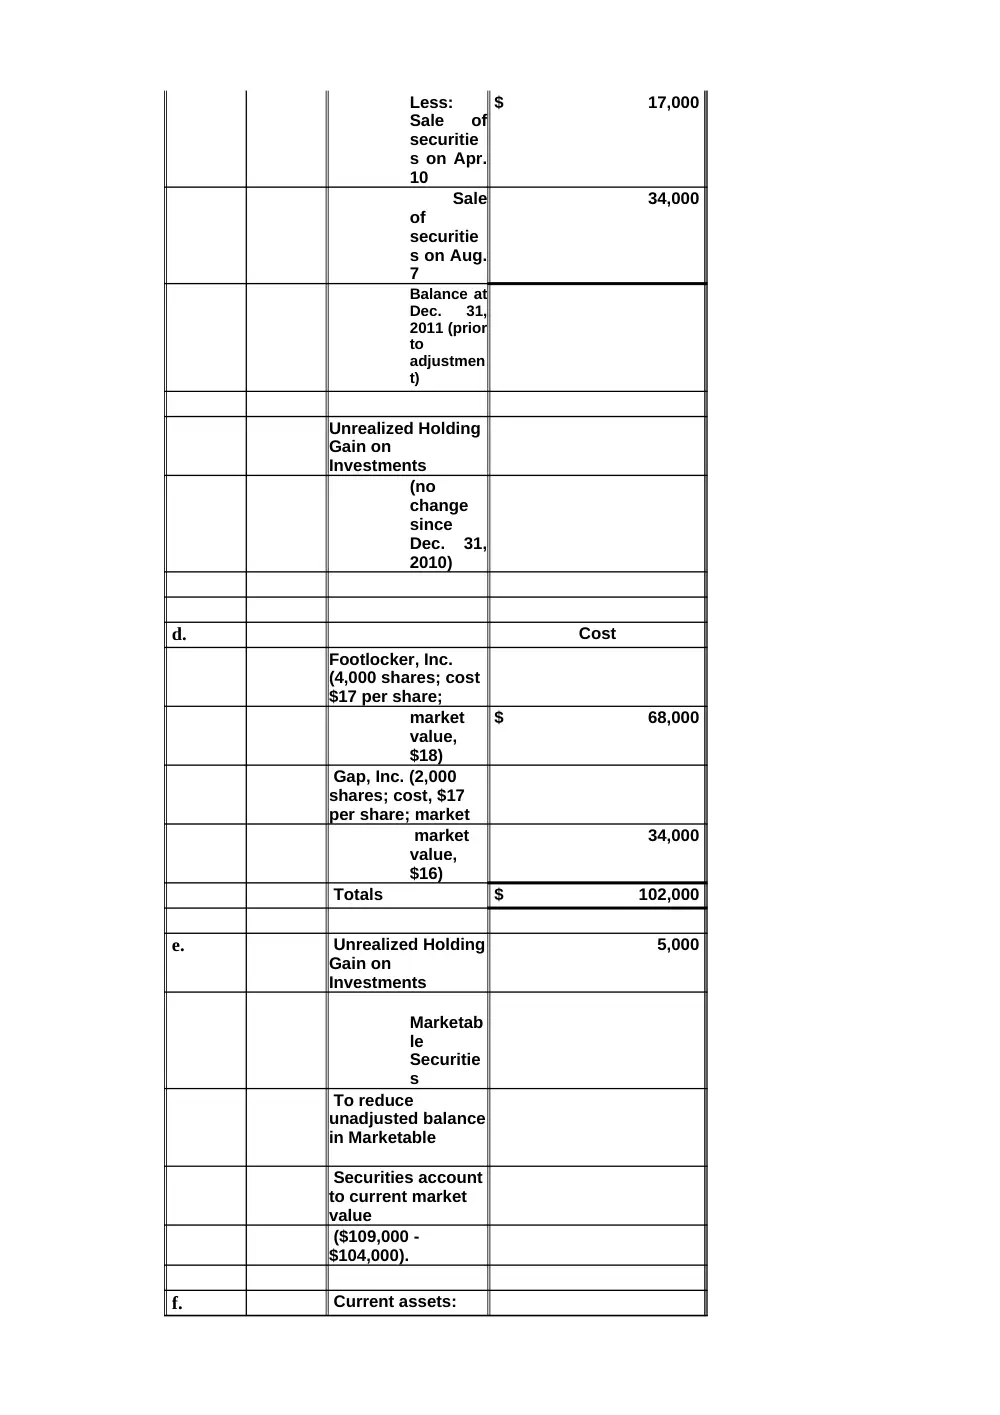
$ 17,000
34,000
d.
Cost
$ 68,000
34,000
Totals
$ 102,000
e.
5,000
f.
Current assets:
Less:
Sale
of
securitie
s on Apr.
10
Sale
of
securitie
s on Aug.
7
Balance at
Dec.
31,
2011 (prior
to
adjustmen
t)
Unrealized Holding
Gain on
Investments
(no
change
since
Dec.
31,
2010)
Footlocker, Inc.
(4,000 shares; cost
$17 per share;
market
value,
$18)
Gap, Inc. (2,000
shares; cost, $17
per share; market
market
value,
$16)
Unrealized Holding
Gain on
Investments
Marketab
le
Securitie
s
To reduce
unadjusted balance
in Marketable
Securities account
to current market
value
($109,000 -
$104,000).
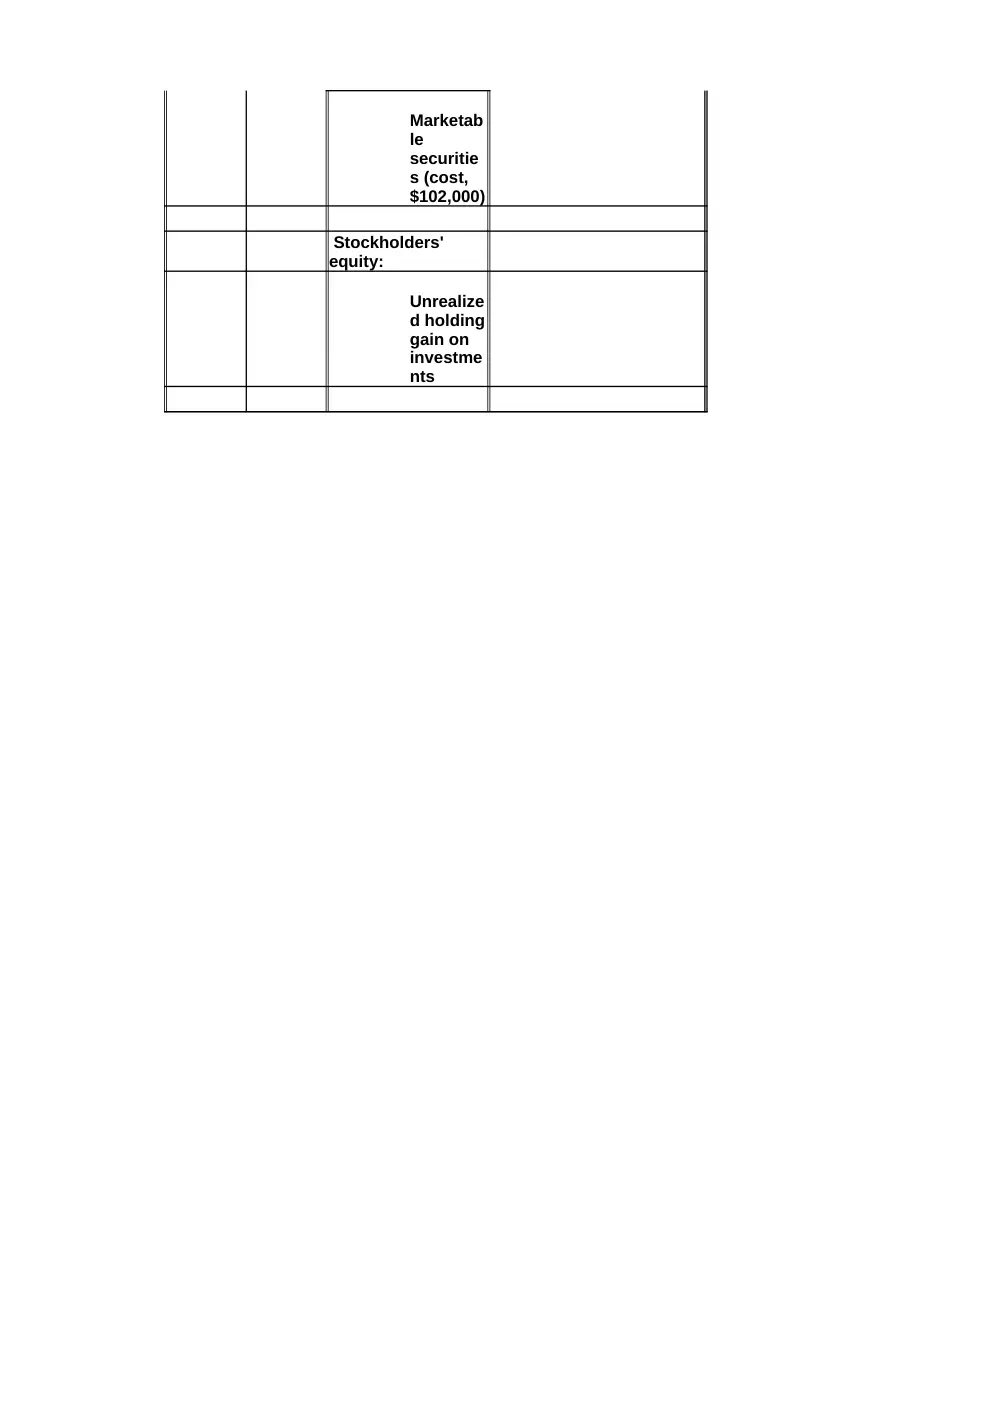
Marketab
le
securitie
s (cost,
$102,000)
Stockholders'
equity:
Unrealize
d holding
gain on
investme
nts
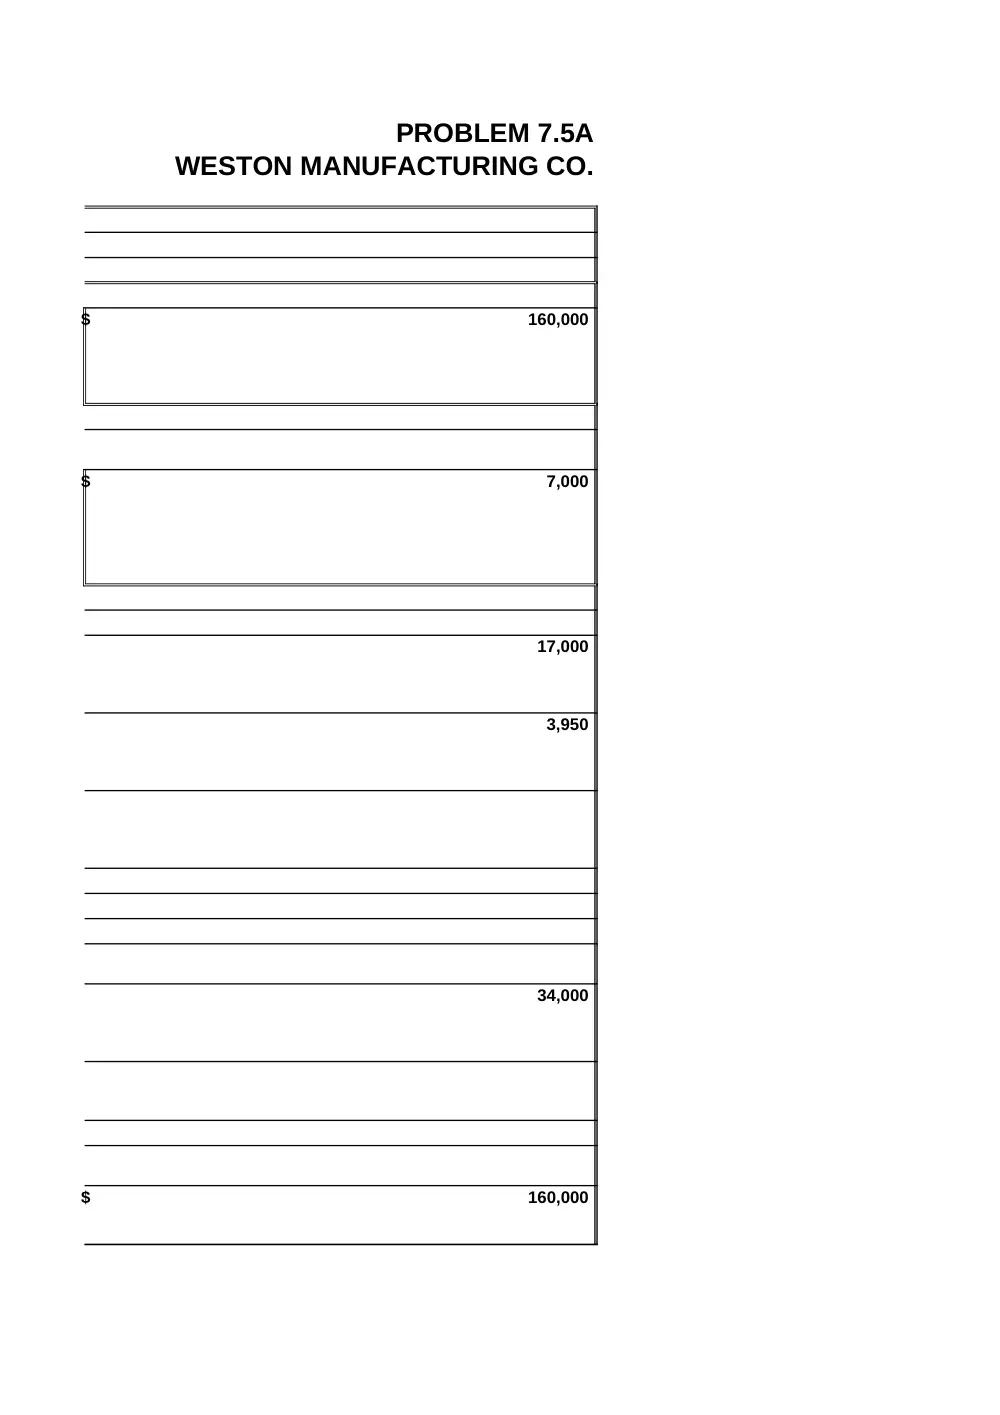
PROBLEM 7.5A
WESTON MANUFACTURING CO.
$ 160,000
$ 7,000
17,000
3,950
34,000
$ 160,000
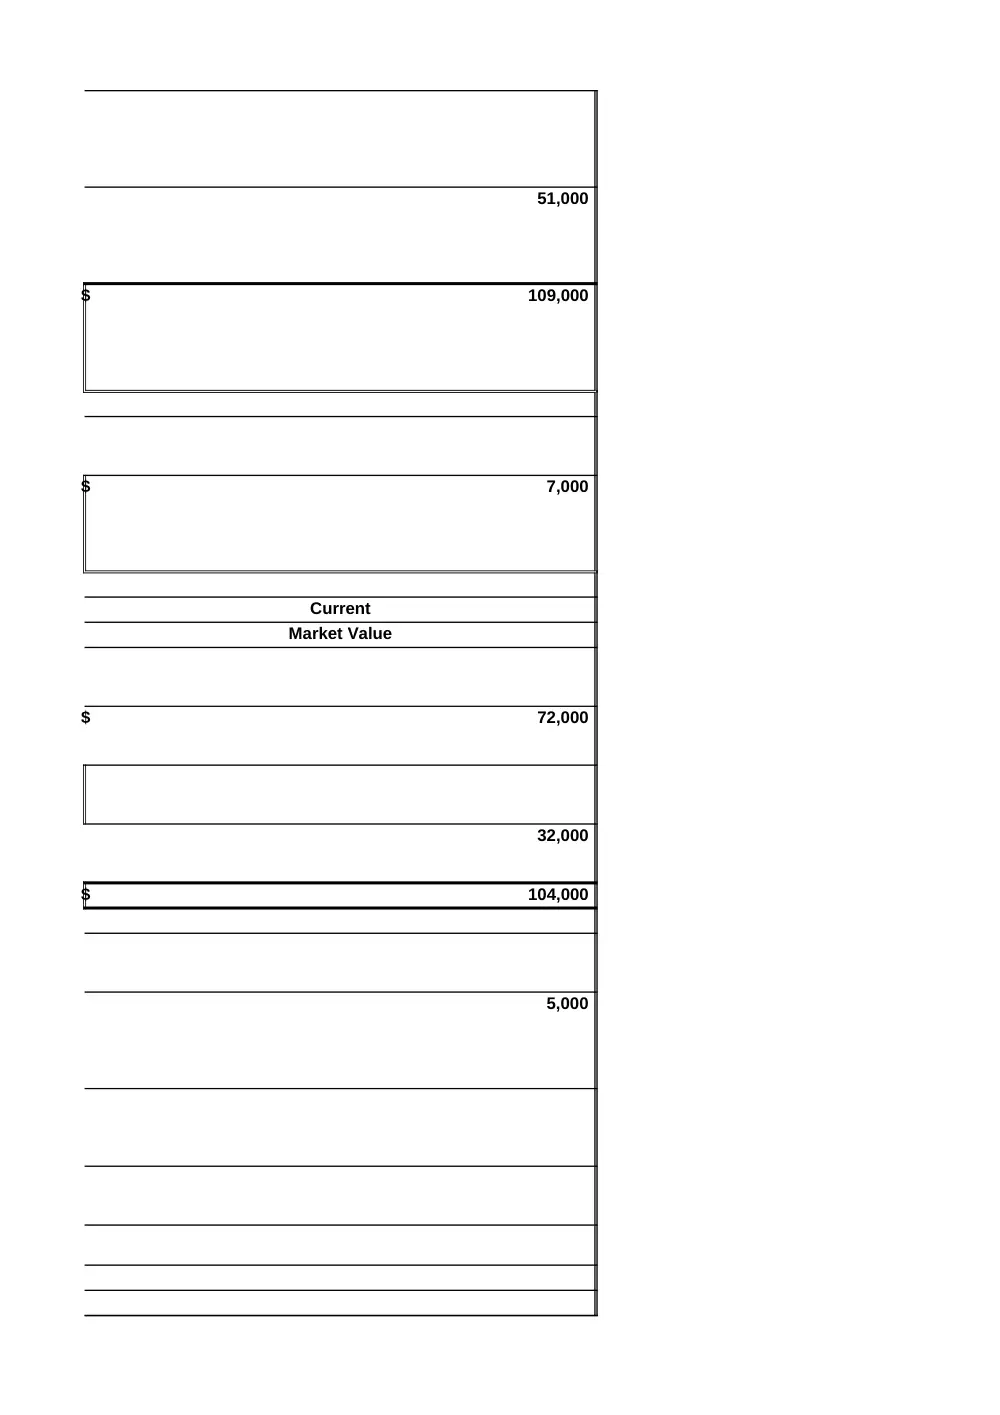
51,000
$ 109,000
$ 7,000
Current
Market Value
$ 72,000
32,000
$ 104,000
5,000
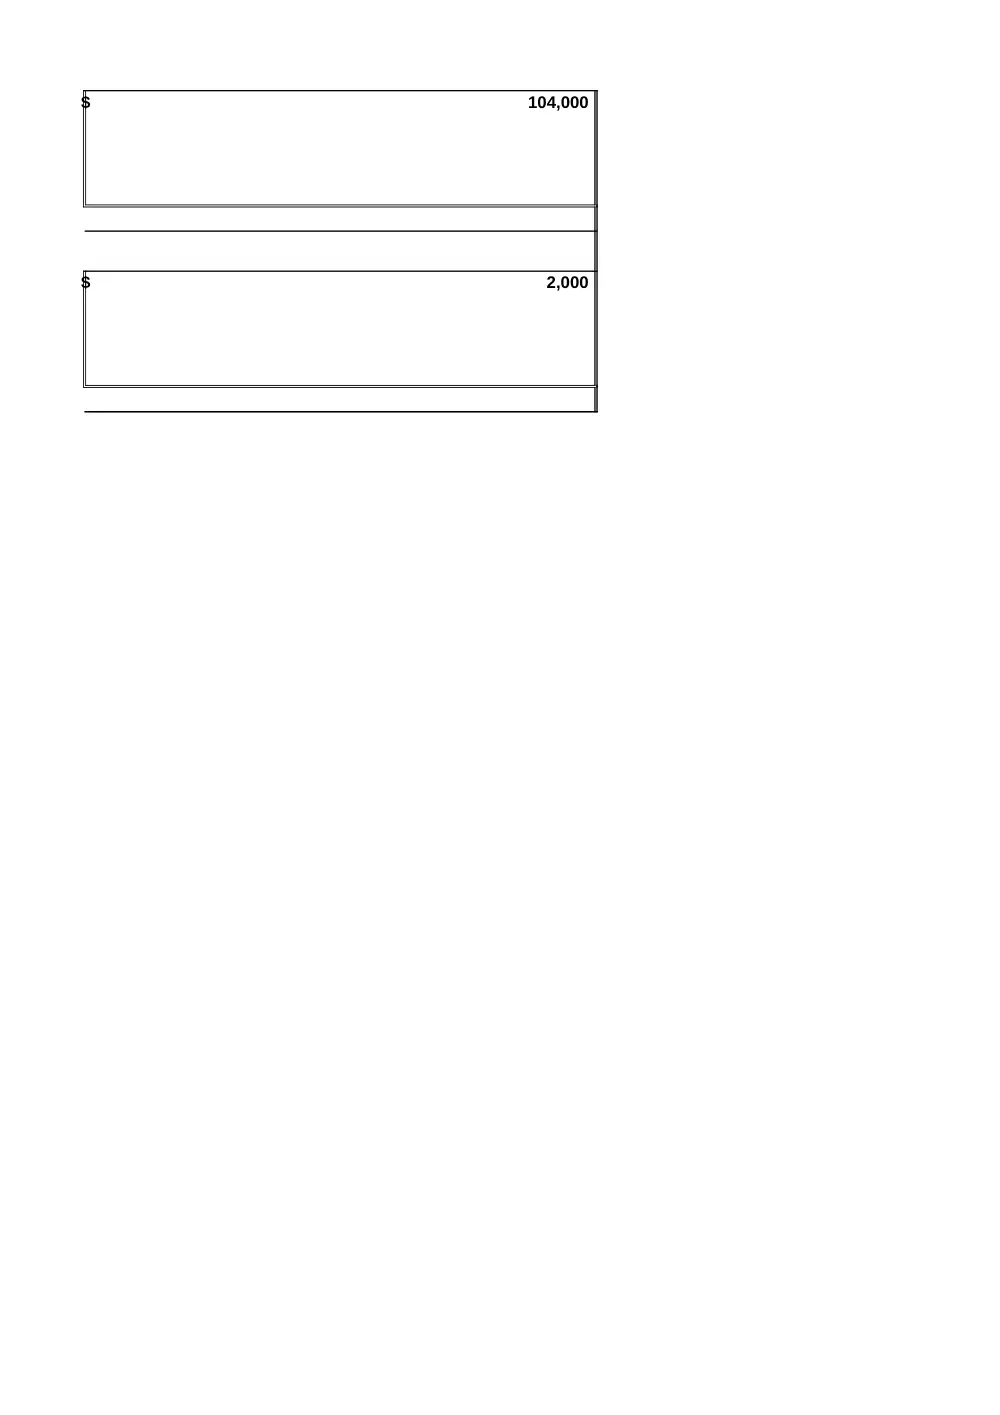
$ 104,000
$ 2,000
PROBLEM
WESTON MANUFACTURING CO. (concl
g.
Nonoperating items:
Computation:
Realized gain
$ 3,950
Less: realized loss
6,060
Net realized loss
$ (2,110)
h.
Loss on sales of
investments
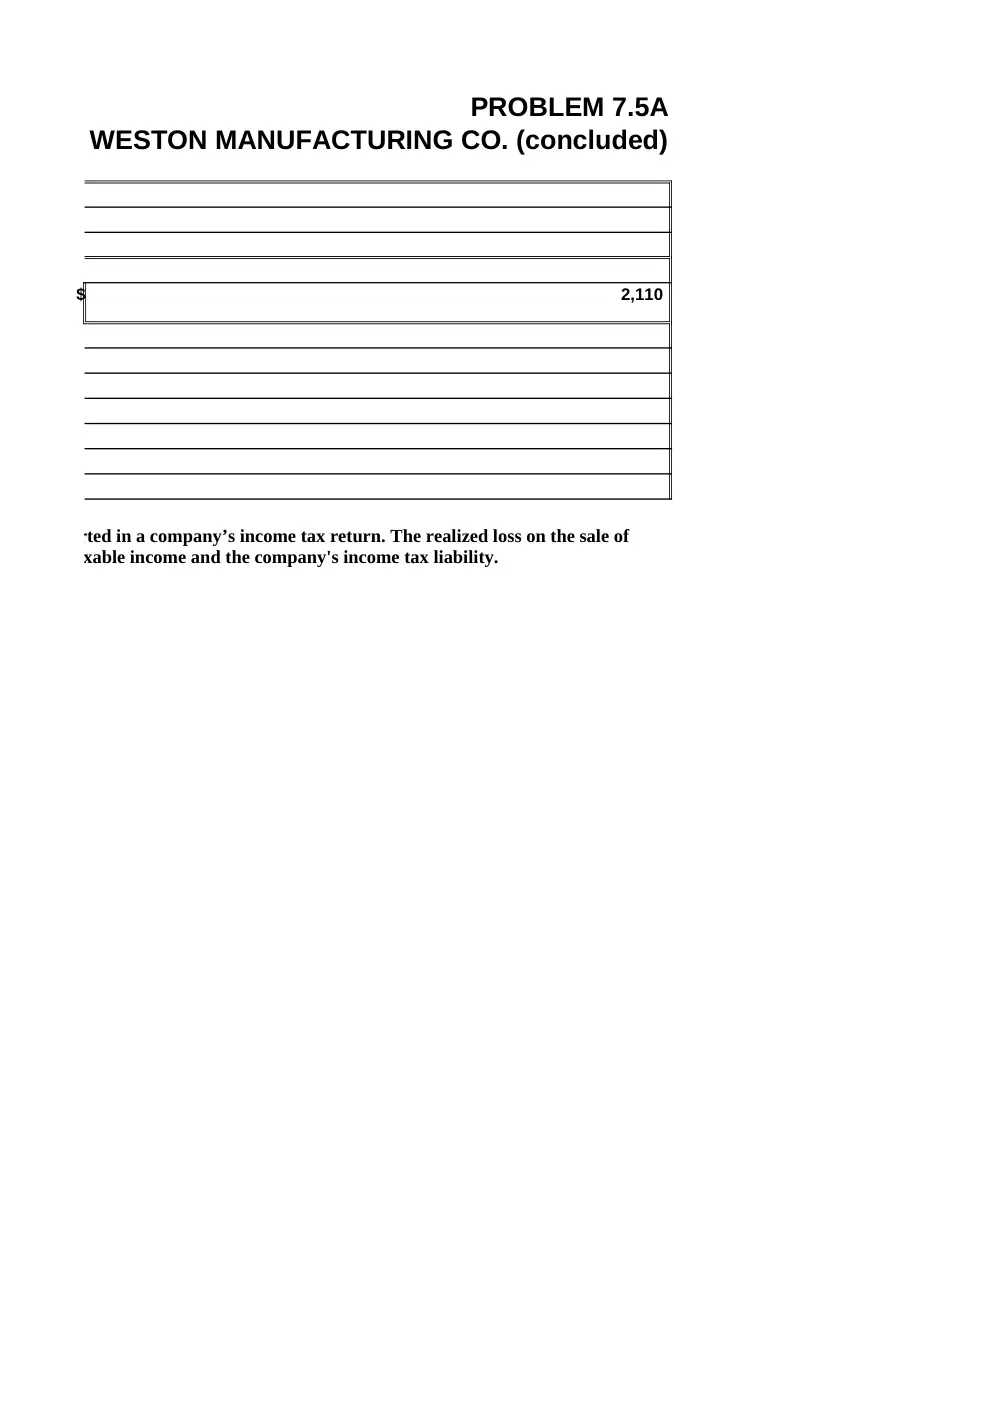
Unrealized gains and losses are not reported in a company’s income tax return. The realized loss on the sa
marketable securities will reduce both taxable income and the company's income tax liability.
PROBLEM 7.5A
WESTON MANUFACTURING CO. (concluded)
$ 2,110
e not reported in a company’s income tax return. The realized loss on the sale of
uce both taxable income and the company's income tax liability.