
ACCT 210 Problems, Fall 2009
American University of Beirut · Financial Accounting · 6 pages

More ACCT 210 files
- Problems 4 · Fall 2015ProblemsView
- Problems Solution Manual All Be,e and Problem ACCT 210 · Fall 2014Problems · with solutionView
- Problems PPE · Fall 2014ProblemsView
- Homework Useful File · Fall 2018FileView
- Notes Accounting 210 Ch 13 · Fall 2018NotesView
- Notes Ch 11 · Fall 2018NotesView
- Notes Ch 9 · Fall 2018NotesView
- Notes Ch 10 · Fall 2018NotesView
Show the text of this problems
45 Minutes, Strong
BLEM 13.6A
RY TECHNOLOGIES
a.
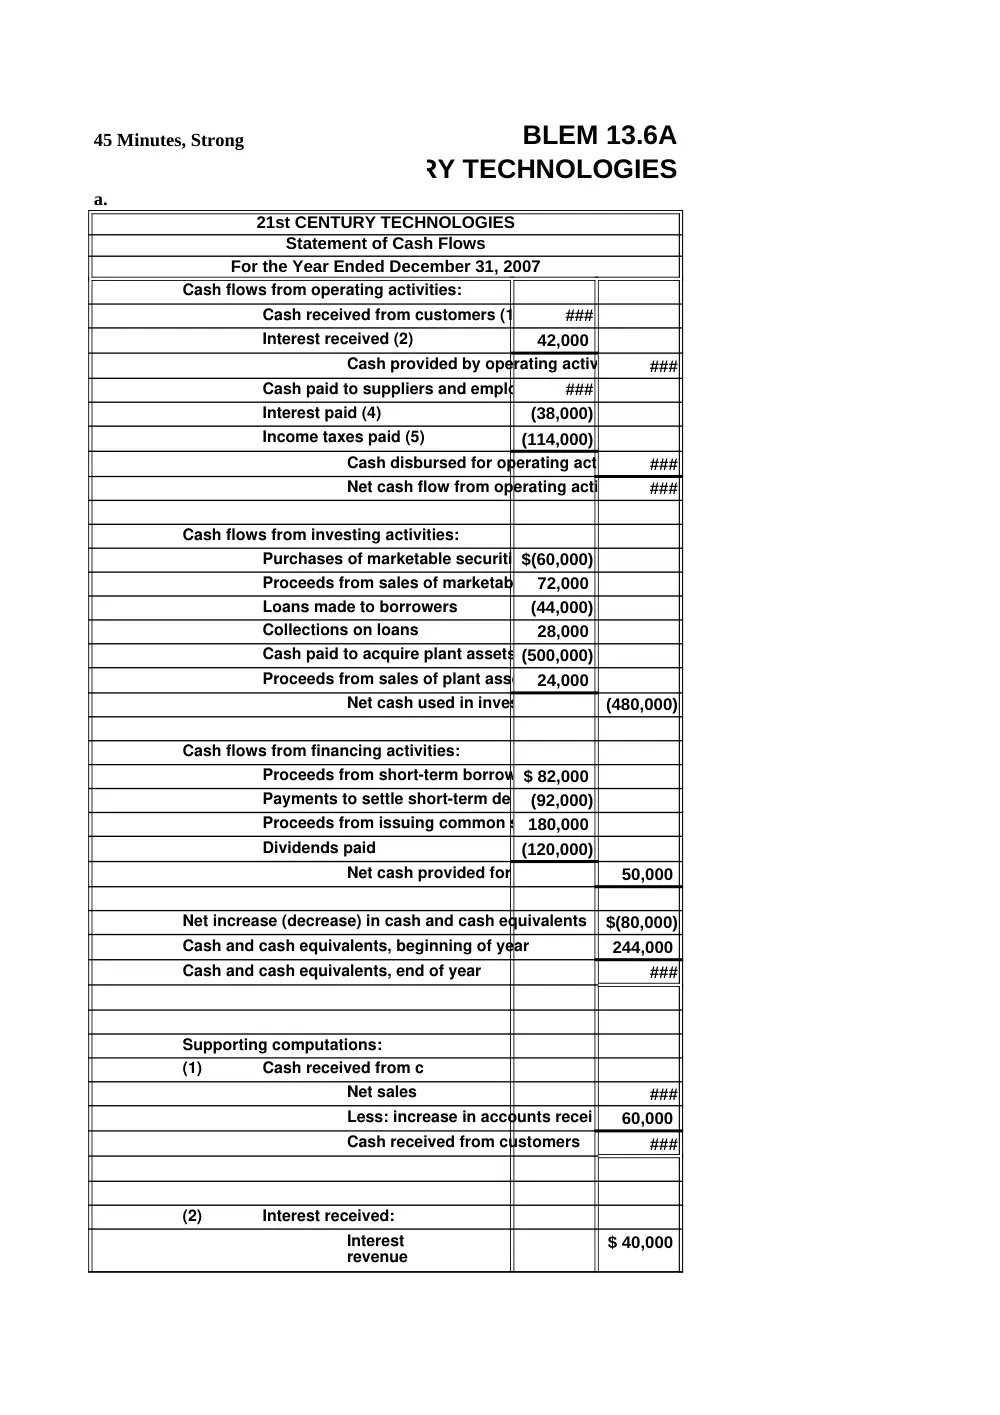
21st CENTURY TECHNOLOGIES
Statement of Cash Flows
For the Year Ended December 31, 2007
Cash flows from operating activities:
Cash received from customers (1
###
Interest received (2)
42,000
Cash provided by operating activi
###
Cash paid to suppliers and emplo
###
Interest paid (4)
(38,000)
Income taxes paid (5)
(114,000)
Cash disbursed for operating acti
###
Net cash flow from operating acti
###
Cash flows from investing activities:
Purchases of marketable securiti $(60,000)
Proceeds from sales of marketable 72,000
Loans made to borrowers
(44,000)
Collections on loans
28,000
Cash paid to acquire plant assets (500,000)
Proceeds from sales of plant asse 24,000
Net cash used in invest
(480,000)
Cash flows from financing activities:
Proceeds from short-term borrow $ 82,000
Payments to settle short-term de (92,000)
Proceeds from issuing common s 180,000
Dividends paid
(120,000)
Net cash provided for
50,000
Net increase (decrease) in cash and cash equivalents
$(80,000)
Cash and cash equivalents, beginning of year
244,000
Cash and cash equivalents, end of year
###
Supporting computations:
(1)
Cash received from c
Net sales
###
Less: increase in accounts recei 60,000
Cash received from customers
###
(2)
Interest received:
$ 40,000
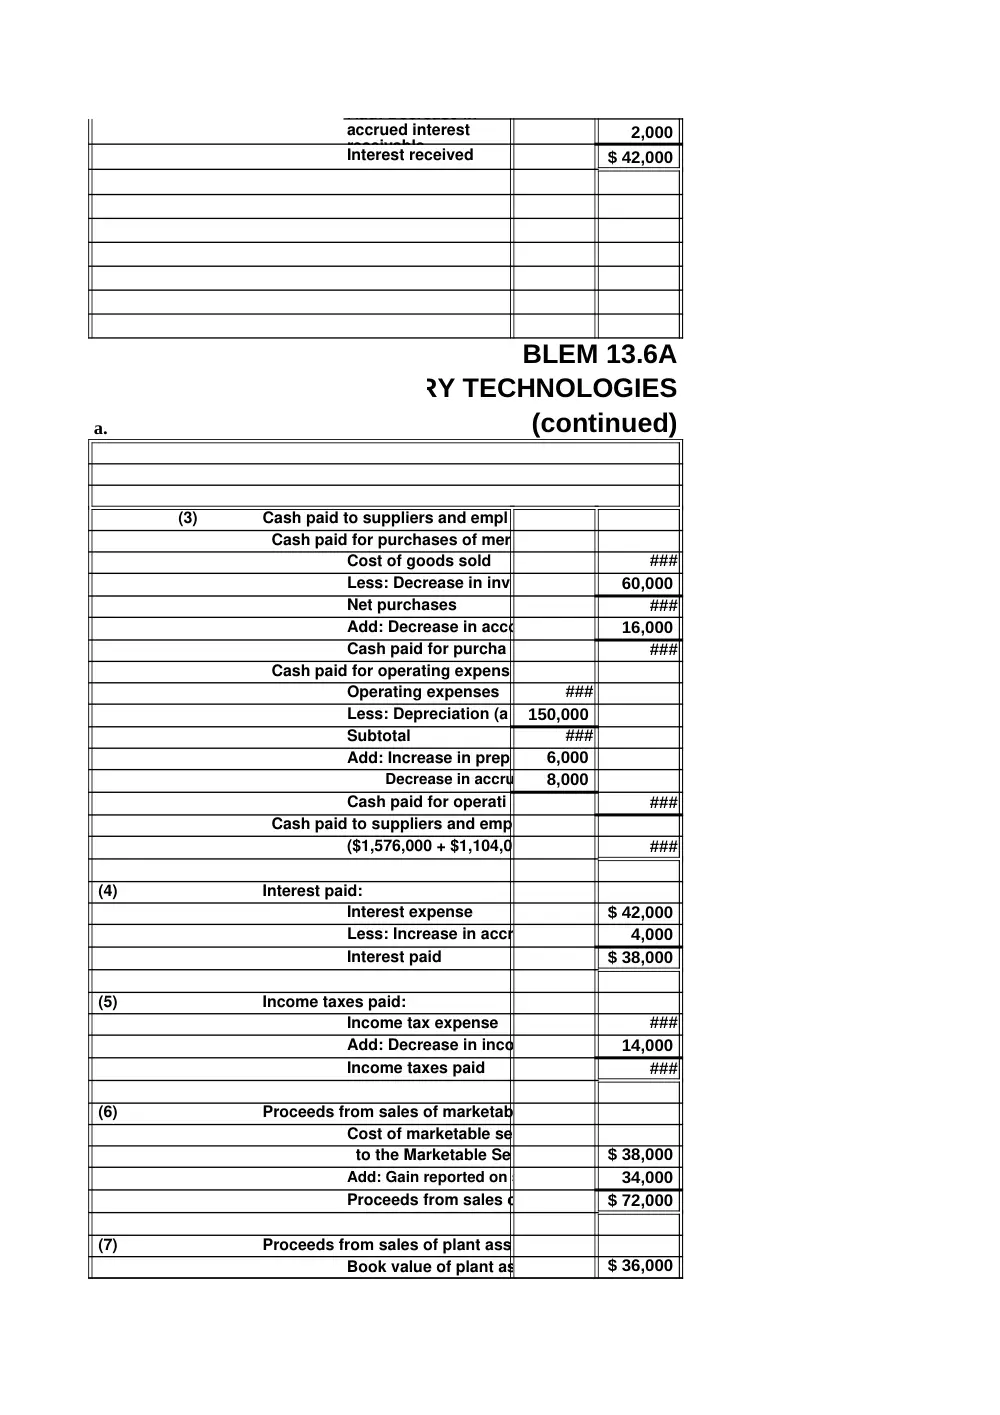
Interest
revenue
2,000
Interest received
$ 42,000
BLEM 13.6A
RY TECHNOLOGIES
a.
(continued)
(3)
Cash paid to suppliers and empl
Cash paid for purchases of mer
Cost of goods sold
###
Less: Decrease in inv
60,000
Net purchases
###
Add: Decrease in acco
16,000
Cash paid for purcha
###
Cash paid for operating expens
Operating expenses
###
Less: Depreciation (a 150,000
Subtotal
###
Add: Increase in prep 6,000
8,000
Cash paid for operati
###
Cash paid to suppliers and emp
($1,576,000 + $1,104,0
###
(4)
Interest paid:
Interest expense
$ 42,000
Less: Increase in accr
4,000
Interest paid
$ 38,000
(5)
Income taxes paid:
Income tax expense
###
Add: Decrease in inco
14,000
Income taxes paid
###
(6)
Proceeds from sales of marketabl
Cost of marketable sec
to the Marketable Se
$ 38,000
Add: Gain reported on s
34,000
Proceeds from sales o
$ 72,000
(7)
Proceeds from sales of plant ass
$ 36,000
Add: Decrease in
accrued interest
receivable
Add: Decrease in accrued liab. for operating expenses
Book value of plant assets sold (paragraph
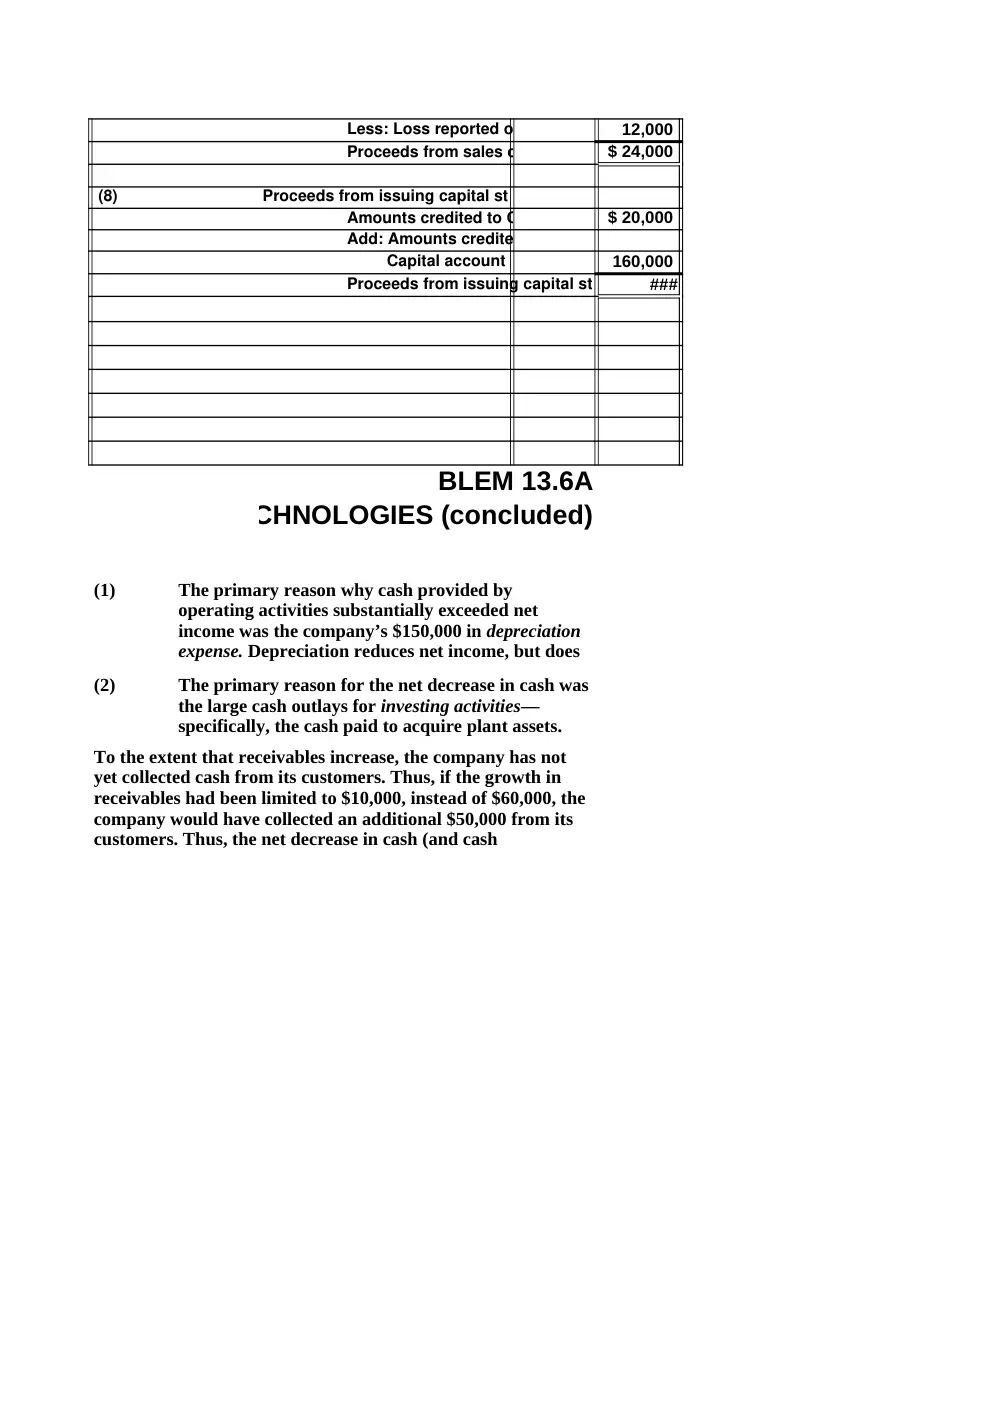
Less: Loss reported on
12,000
Proceeds from sales o
$ 24,000
(8)
Proceeds from issuing capital st
Amounts credited to C
$ 20,000
Add: Amounts credited
Capital account
160,000
Proceeds from issuing capital st
###
BLEM 13.6A
CHNOLOGIES (concluded)
(1)
(2)
The primary reason why cash provided by
operating activities substantially exceeded net
income was the company’s $150,000 in depreciation
expense. Depreciation reduces net income, but does
The primary reason for the net decrease in cash was
the large cash outlays for investing activities—
specifically, the cash paid to acquire plant assets.
To the extent that receivables increase, the company has not
yet collected cash from its customers. Thus, if the growth in
receivables had been limited to $10,000, instead of $60,000, the
company would have collected an additional $50,000 from its
customers. Thus, the net decrease in cash (and cash
60 Minutes, Strong
PROBLEM 13.7A
SATELLITE 201
a.
SATELLITE 2010
Worksheet for a Statement of Cash Flows
For the Year Ended December 31, 2007
Balance sheet effects:
Effect of Transactions
Beginning
Debit
Credit
Balance
Changes
Changes
Assets
Cash and cash equivalents
80,000
(x)
Accounts receivable
100,000
(3)
750,000
Plant and equipment (net of
accumulated depreciation)
600,000
(6)
###
(2)
Totals
780,000
Liabilities & Owners' Equity
Notes payable (short-term)
0
(7)
Accounts payable
30,000
(4)
Accrued expenses payable
45,000
(5)
13,000
Notes payable (long-term)
390,000
(6)
Capital stock (no par)
200,000
(8)
Retained earnings
115,000
(1)
Totals
=SUM(f10.f 780,000
###
Cash effects:
Sources
Uses
Operating activities:
Net income
(1)
440,000
Depreciation expense
(2)
147,000
Increase in accounts receivable
(3)
Increase in accounts payable
(4)
33,000
Decrease in accrued
expenses payable
(5)
Investing activities:
Cash paid for plant assets
(6)
Financing activities:
Short-term borrowing
(7)
###
Issuance of capital stock
(8)
500,000
Subtotals
###
Net decrease in cash
(x)
43,000
Totals
###
BLEM 13.7A
TELLITE 2010 (continued)
b.
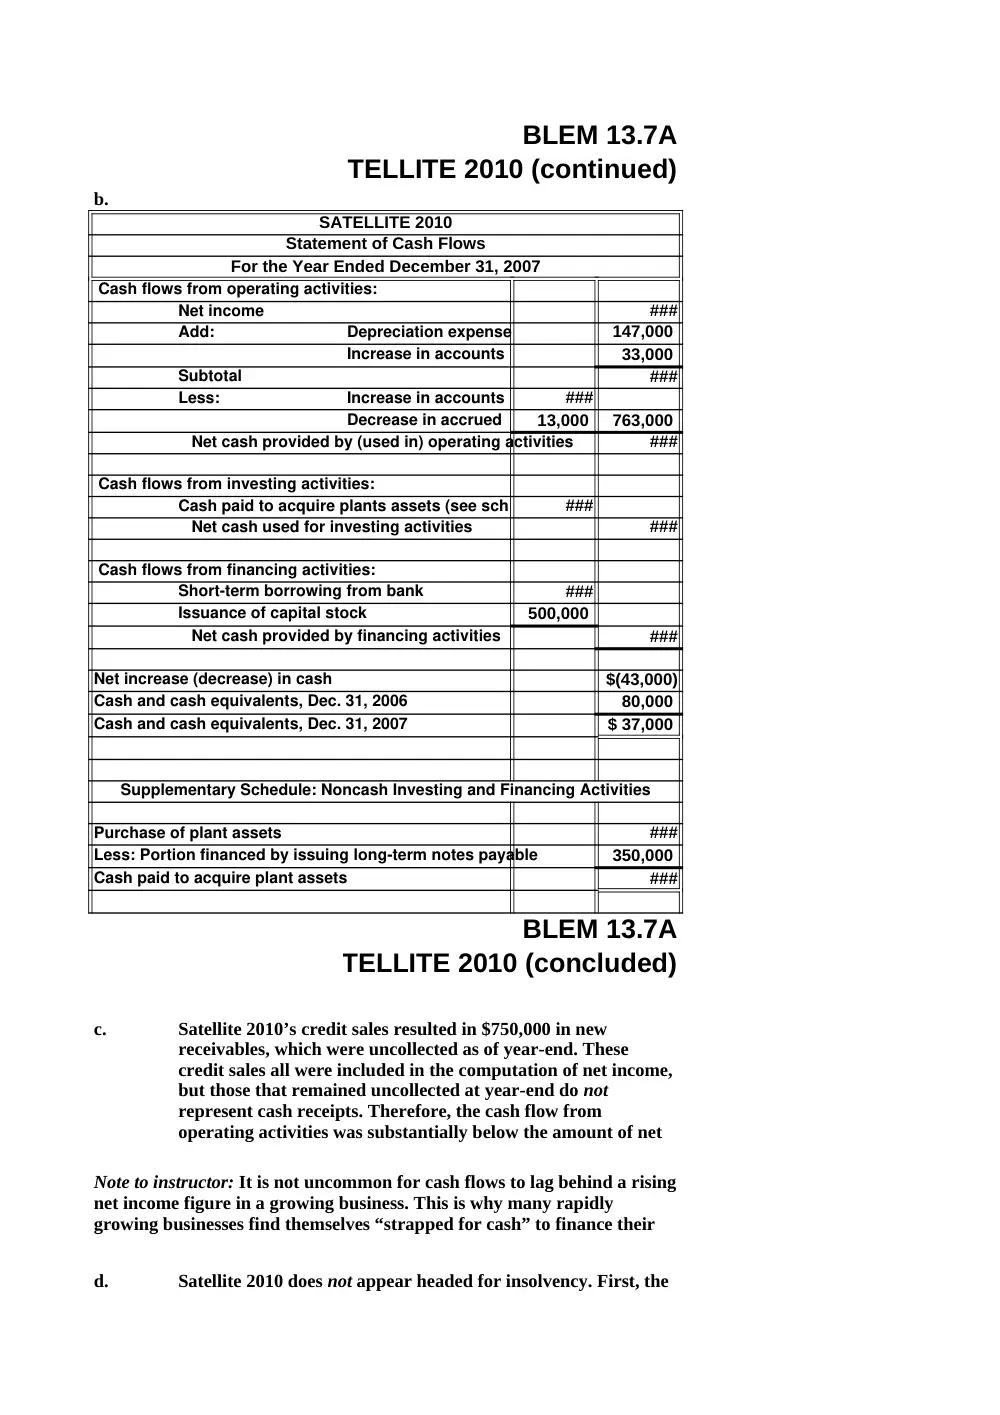
SATELLITE 2010
Statement of Cash Flows
For the Year Ended December 31, 2007
Cash flows from operating activities:
Net income
###
Add:
Depreciation expense
147,000
Increase in accounts
33,000
Subtotal
###
Less:
Increase in accounts
###
Decrease in accrued 13,000 763,000
Net cash provided by (used in) operating activities
###
Cash flows from investing activities:
Cash paid to acquire plants assets (see sch
###
Net cash used for investing activities
###
Cash flows from financing activities:
Short-term borrowing from bank
###
Issuance of capital stock
500,000
Net cash provided by financing activities
###
Net increase (decrease) in cash
$(43,000)
Cash and cash equivalents, Dec. 31, 2006
80,000
Cash and cash equivalents, Dec. 31, 2007
$ 37,000
Supplementary Schedule: Noncash Investing and Financing Activities
Purchase of plant assets
###
Less: Portion financed by issuing long-term notes payable
350,000
Cash paid to acquire plant assets
###
BLEM 13.7A
TELLITE 2010 (concluded)
c.
d.
Satellite 2010’s credit sales resulted in $750,000 in new
receivables, which were uncollected as of year-end. These
credit sales all were included in the computation of net income,
but those that remained uncollected at year-end do not
represent cash receipts. Therefore, the cash flow from
operating activities was substantially below the amount of net
Note to instructor: It is not uncommon for cash flows to lag behind a rising
net income figure in a growing business. This is why many rapidly
growing businesses find themselves “strapped for cash” to finance their
Satellite 2010 does not appear headed for insolvency. First, the
company has a $6 million line of credit, against which it has
drawn only $1,450,000. This gives the company considerable
debt-paying ability. Next, if Satellite 2010’s rapid growth
continues, the company should not have difficulty issuing
additional capital stock to investors as a means of raising cash.
If a company is obviously successful, it usually is able to raise
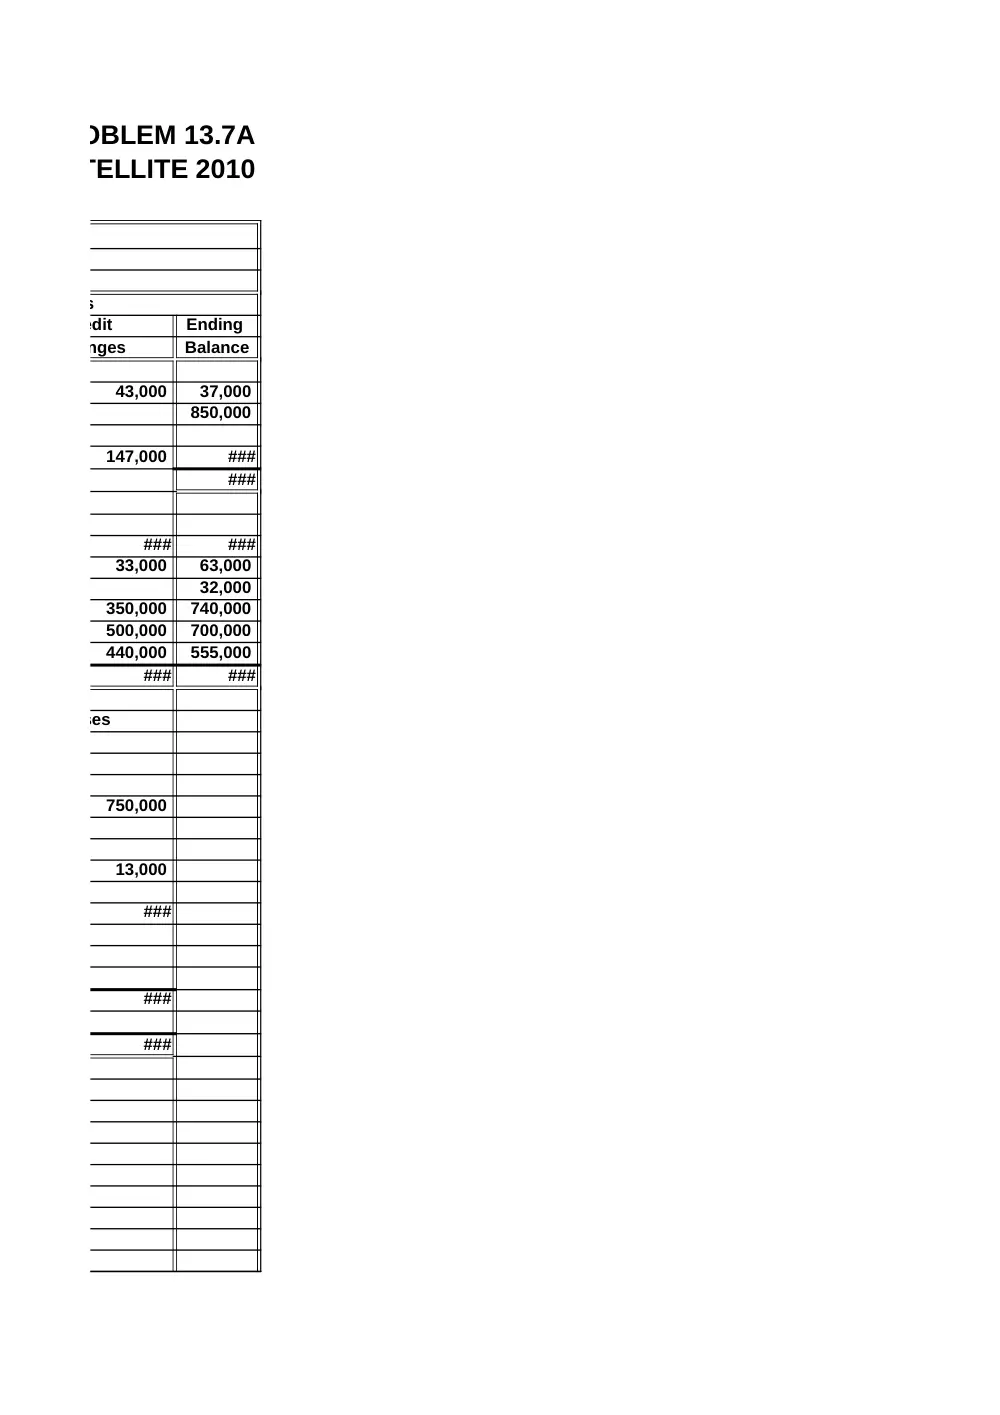
PROBLEM 13.7A
SATELLITE 2010
ransactions
Credit
Ending
Changes
Balance
43,000 37,000
850,000
147,000
###
###
###
###
33,000
63,000
32,000
350,000
740,000
500,000
700,000
440,000 555,000
###
###
Uses
750,000
13,000
###
###
###