
ACCT 210 Problems PPE, Fall 2014
American University of Beirut · Financial Accounting · 4 pages

More ACCT 210 files
- Problems 4 · Fall 2015ProblemsView
- Problems Solution Manual All Be,e and Problem ACCT 210 · Fall 2014Problems · with solutionView
- Problems · Fall 2009ProblemsView
- Homework Useful File · Fall 2018FileView
- Notes Accounting 210 Ch 13 · Fall 2018NotesView
- Notes Ch 11 · Fall 2018NotesView
- Notes Ch 9 · Fall 2018NotesView
- Notes Ch 10 · Fall 2018NotesView
Show the text of this problems
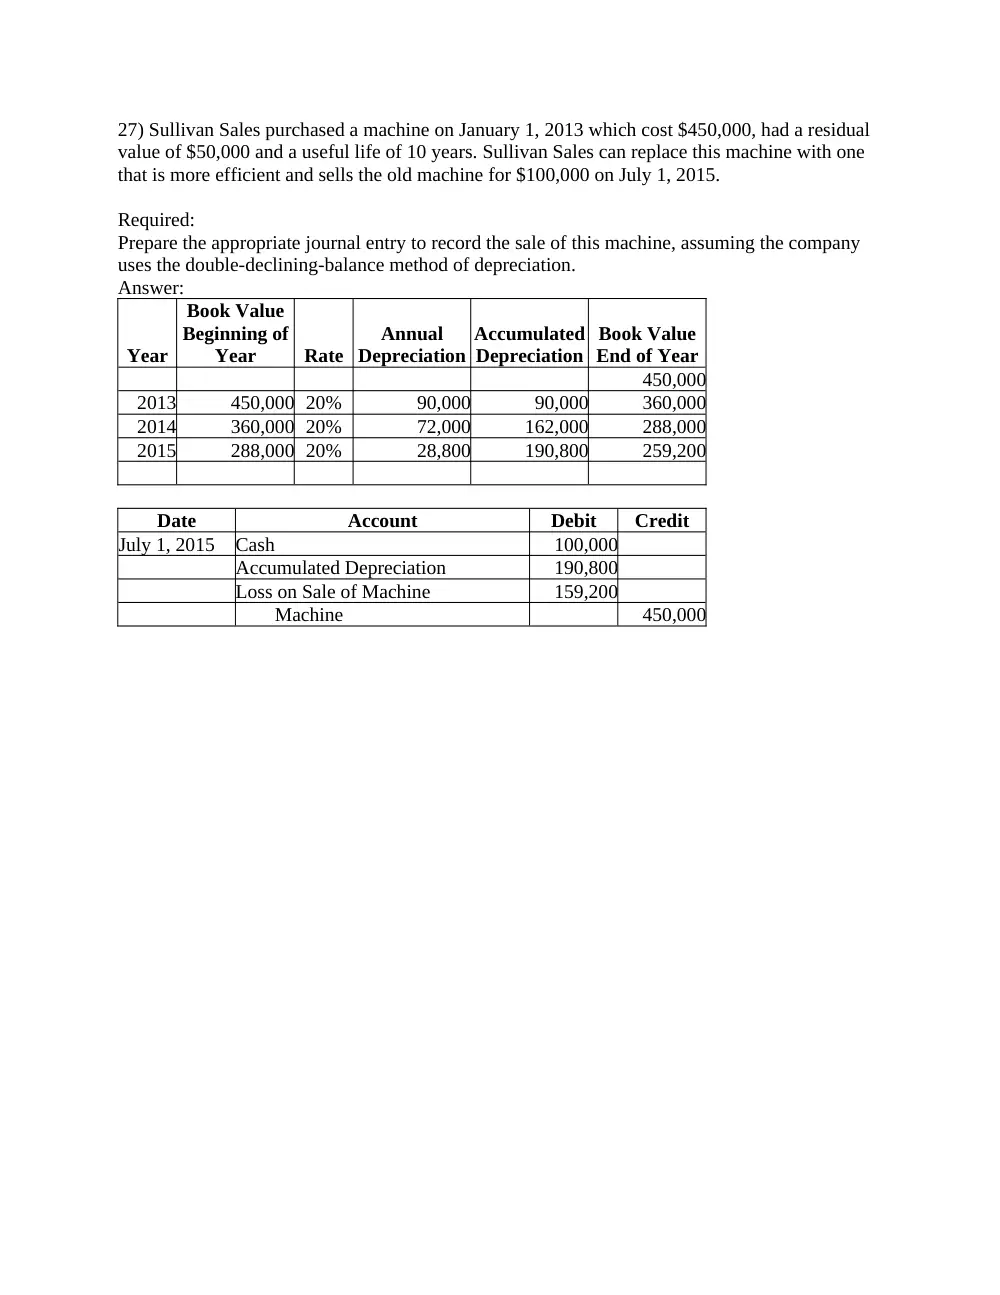
27) Sullivan Sales purchased a machine on January 1, 2013 which cost $450,000, had a residual
value of $50,000 and a useful life of 10 years. Sullivan Sales can replace this machine with one
that is more efficient and sells the old machine for $100,000 on July 1, 2015.
Required:
Prepare the appropriate journal entry to record the sale of this machine, assuming the company
uses the double-declining-balance method of depreciation.
Answer:
Year
Book Value
Beginning of
Year
Rate
Annual
Depreciation
Accumulated
Depreciation
Book Value
End of Year
450,000
2013
450,000 20%
90,000
90,000
360,000
2014
360,000 20%
72,000
162,000
288,000
2015
288,000 20%
28,800
190,800
259,200
Date
Account
Debit
Credit
July 1, 2015
Cash
100,000
Accumulated Depreciation
190,800
Loss on Sale of Machine
159,200
Machine
450,000
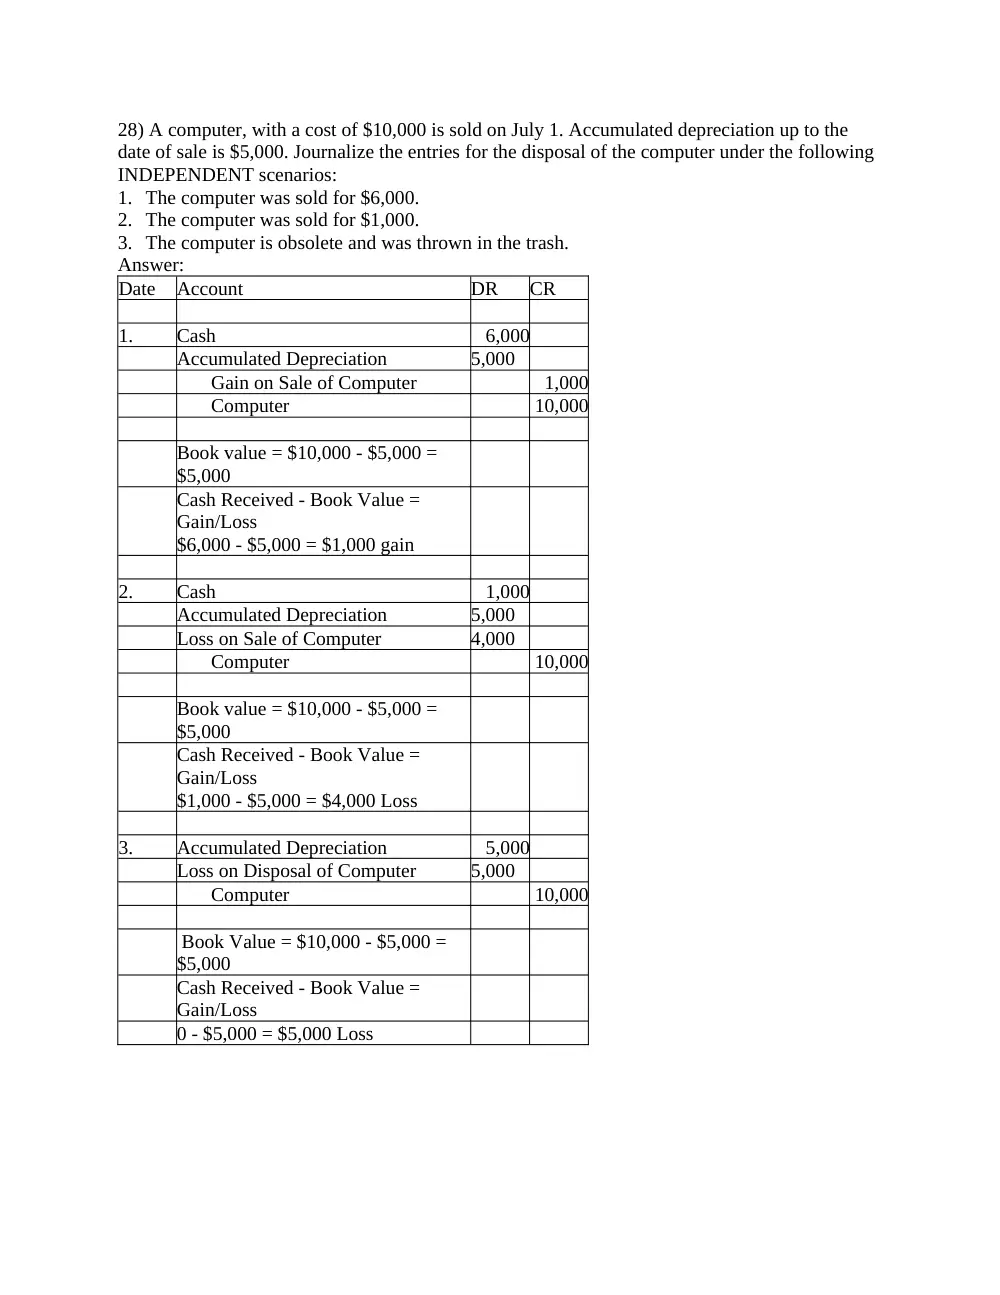
28) A computer, with a cost of $10,000 is sold on July 1. Accumulated depreciation up to the
date of sale is $5,000. Journalize the entries for the disposal of the computer under the following
INDEPENDENT scenarios:
1. The computer was sold for $6,000.
2. The computer was sold for $1,000.
3. The computer is obsolete and was thrown in the trash.
Answer:
Date
Account
DR
CR
1.
Cash
6,000
Accumulated Depreciation
5,000
Gain on Sale of Computer
1,000
Computer
10,000
Book value = $10,000 - $5,000 =
$5,000
Cash Received - Book Value =
Gain/Loss
$6,000 - $5,000 = $1,000 gain
2.
Cash
1,000
Accumulated Depreciation
5,000
Loss on Sale of Computer
4,000
Computer
10,000
Book value = $10,000 - $5,000 =
$5,000
Cash Received - Book Value =
Gain/Loss
$1,000 - $5,000 = $4,000 Loss
3.
Accumulated Depreciation
5,000
Loss on Disposal of Computer
5,000
Computer
10,000
Book Value = $10,000 - $5,000 =
$5,000
Cash Received - Book Value =
Gain/Loss
0 - $5,000 = $5,000 Loss
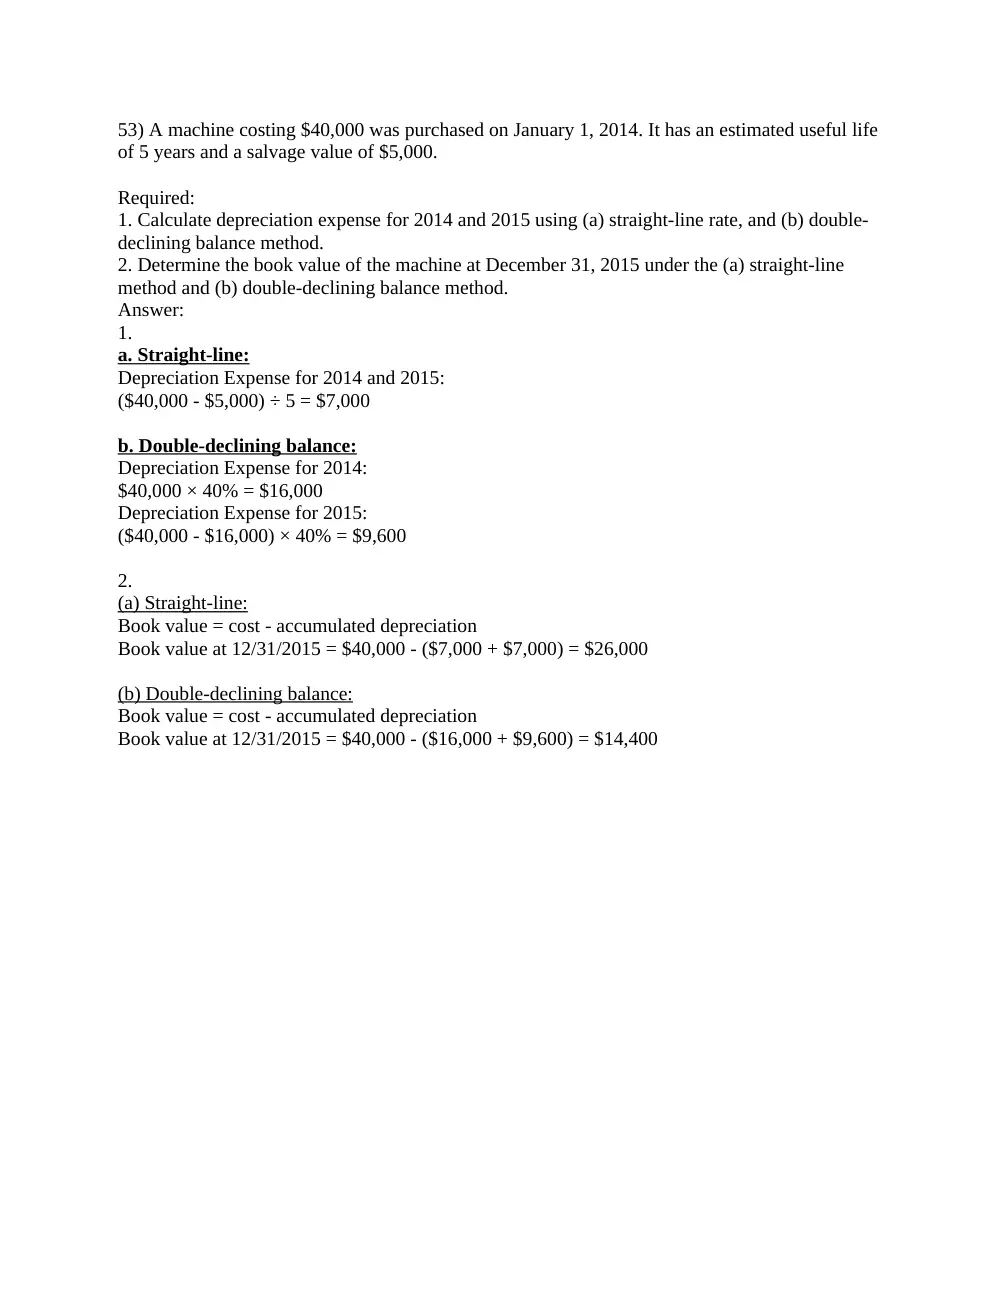
53) A machine costing $40,000 was purchased on January 1, 2014. It has an estimated useful life
of 5 years and a salvage value of $5,000.
Required:
1. Calculate depreciation expense for 2014 and 2015 using (a) straight-line rate, and (b) double-
declining balance method.
2. Determine the book value of the machine at December 31, 2015 under the (a) straight-line
method and (b) double-declining balance method.
Answer:
1.
a. Straight-line:
Depreciation Expense for 2014 and 2015:
($40,000 - $5,000) ÷ 5 = $7,000
b. Double-declining balance:
Depreciation Expense for 2014:
$40,000 × 40% = $16,000
Depreciation Expense for 2015:
($40,000 - $16,000) × 40% = $9,600
2.
(a) Straight-line:
Book value = cost - accumulated depreciation
Book value at 12/31/2015 = $40,000 - ($7,000 + $7,000) = $26,000
(b) Double-declining balance:
Book value = cost - accumulated depreciation
Book value at 12/31/2015 = $40,000 - ($16,000 + $9,600) = $14,400
54) A plant asset is acquired by a business on January 1, 2014, for $100,000. The asset's
estimated residual value is $10,000 and its estimated life is 5 years. Management chooses to use
straight-line depreciation.
On January 1, 2016, management revises the total useful life to 8 years and the residual value to
$5,000.
Required:
1. Compute the balance in Accumulated Depreciation on January 1, 2016.
2. Compute the Depreciation Expense for the year ending December 31, 2016.
3. Compute the balance in Accumulated Depreciation on December 31, 2016.
4. Prepare the adjusting journal entry on December 31, 2016 for the year. Omit the explanation.
Answer:
1. ($100,000 - $10,000) ÷ 5 = $18,000
$18,000 × 2 = $36,000
2. ($100,000 - $36,000 - $5,000) ÷ 6 = $9,833
3. $36,000 + $9,833 = $45,833
4.
ACCOUNT
DEBIT
CREDIT
Depreciation Expense
9,833
Accumulated
Depreciation
9,833
55) On January 1, 2015, Williams Company, Inc. purchased machinery for $350,000 and
depreciated it on a straight-line basis over 20 years. The estimated residual value was zero. On
January 1, 2018, the company realized the machine will remain useful for only 5 more years and
also revised the residual value to $12,000.
Required:
1. What is the depreciation expense per year before the change in estimate?
2. What is the revised depreciation expense per year?
3. Prepare the adjusting journal entry for the year ending December 31, 2018. Omit the
explanation.
Answer:
1. Depreciation Expense:
Original calculation:
($350,000 - 0) ÷ 20 = $17,500 per year
$17,500 × 3 = $52,500 Accumulated Depreciation
2. Revised depreciation expense:
($350,000 - $52,500 - $12,000) ÷ 5 = $57,100
3.
ACCOUNTS
DEBIT
CREDIT
Depreciation Expense
57,100
Accumulated Depreciation
57,100