
ACCT 210 Lecture, Fall 2004
American University of Beirut · Financial Accounting · 15 pages



Showing the first 10 of 15 pages. Download the PDF to see all of it.
More ACCT 210 files
Show the text of this lab
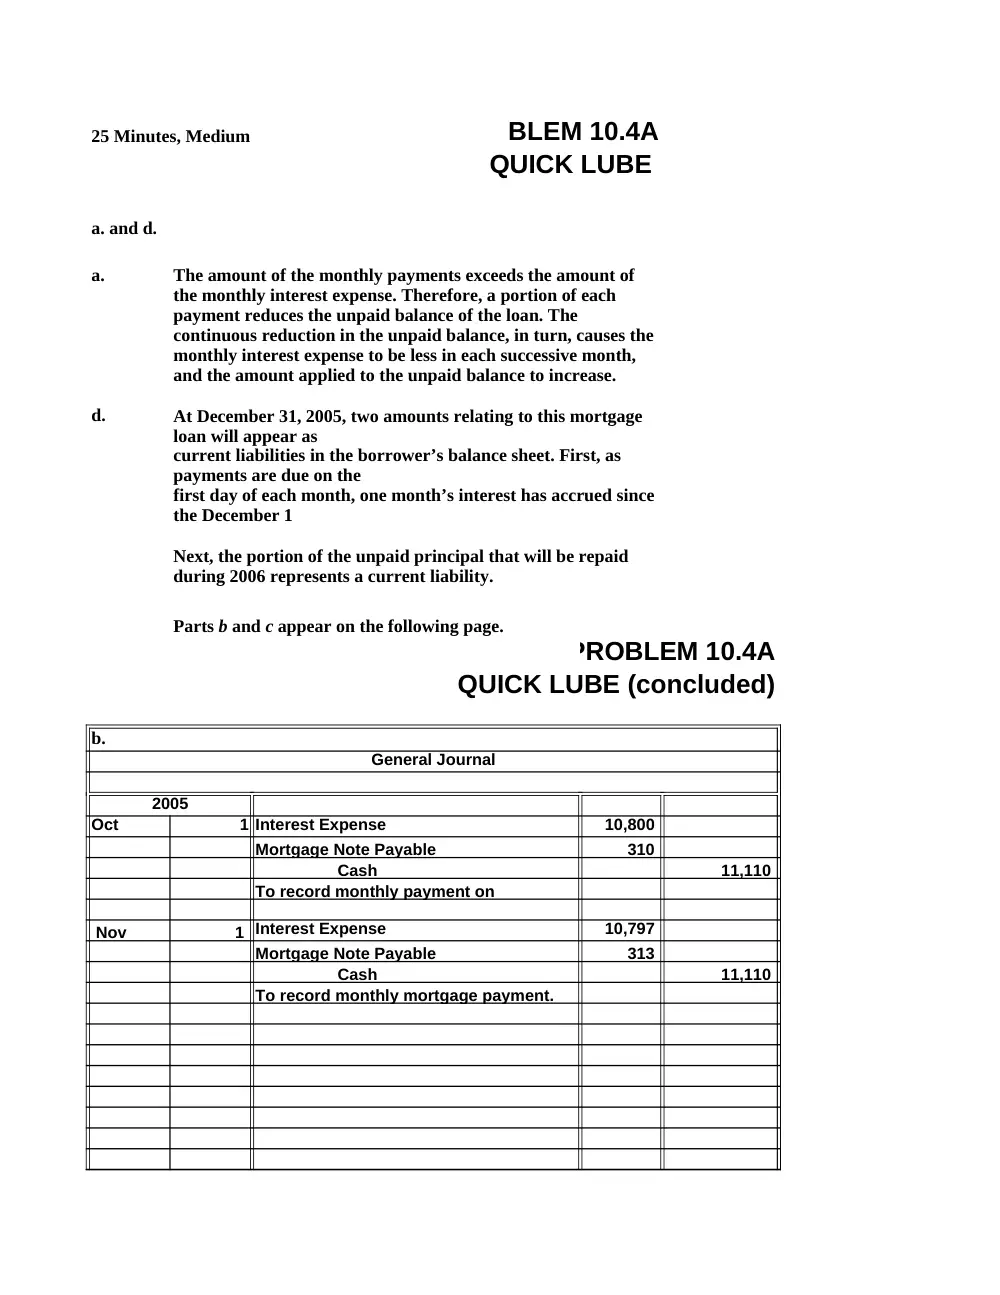
25 Minutes, Medium
BLEM 10.4A
QUICK LUBE
a. and d.
a.
d.
PROBLEM 10.4A
QUICK LUBE (concluded)
b.
General Journal
2005
Oct
1 Interest Expense
10,800
Mortgage Note Payable
310
Cash
11,110
Nov
1 Interest Expense
10,797
Mortgage Note Payable
313
Cash
11,110
To record monthly mortgage payment.
The amount of the monthly payments exceeds the amount of
the monthly interest expense. Therefore, a portion of each
payment reduces the unpaid balance of the loan. The
continuous reduction in the unpaid balance, in turn, causes the
monthly interest expense to be less in each successive month,
and the amount applied to the unpaid balance to increase.
At December 31, 2005, two amounts relating to this mortgage
loan will appear as
current liabilities in the borrower’s balance sheet. First, as
payments are due on the
first day of each month, one month’s interest has accrued since
the December 1
Next, the portion of the unpaid principal that will be repaid
during 2006 represents a current liability.
Parts b and c appear on the following page.
To record monthly payment on
mortgage.
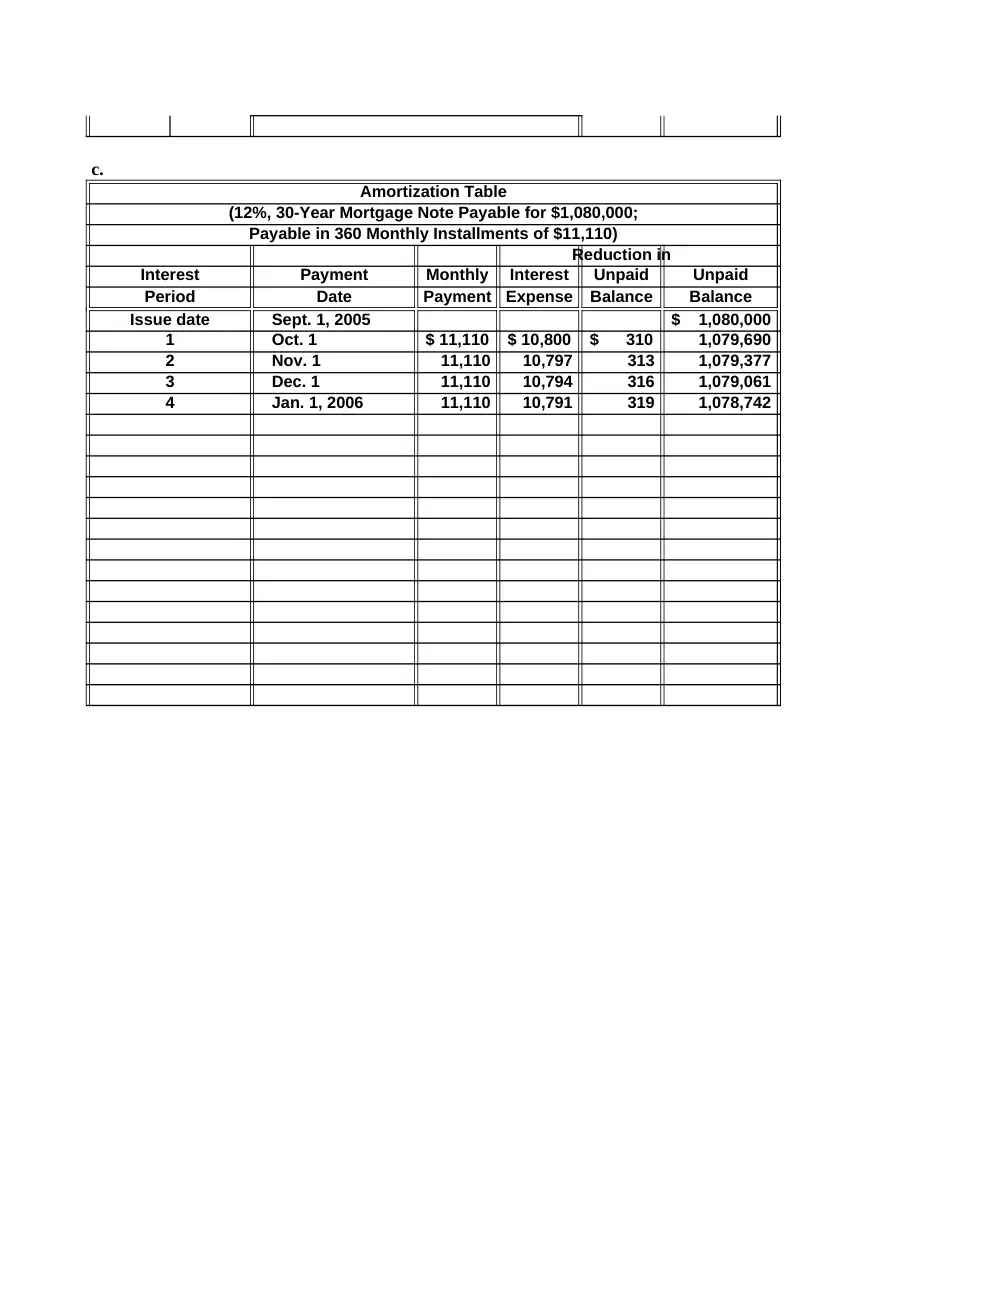
c.
Amortization Table
(12%, 30-Year Mortgage Note Payable for $1,080,000;
Payable in 360 Monthly Installments of $11,110)
Reduction in
Interest
Payment
Monthly
Interest
Unpaid
Unpaid
Period
Date
Payment
Expense Balance
Balance
Issue date
Sept. 1, 2005
$ 1,080,000
1
Oct. 1
$ 11,110 $ 10,800 $ 310 1,079,690
2
Nov. 1
11,110 10,797 313 1,079,377
3
Dec. 1
11,110 10,794 316 1,079,061
4
Jan. 1, 2006
11,110 10,791 319 1,078,742
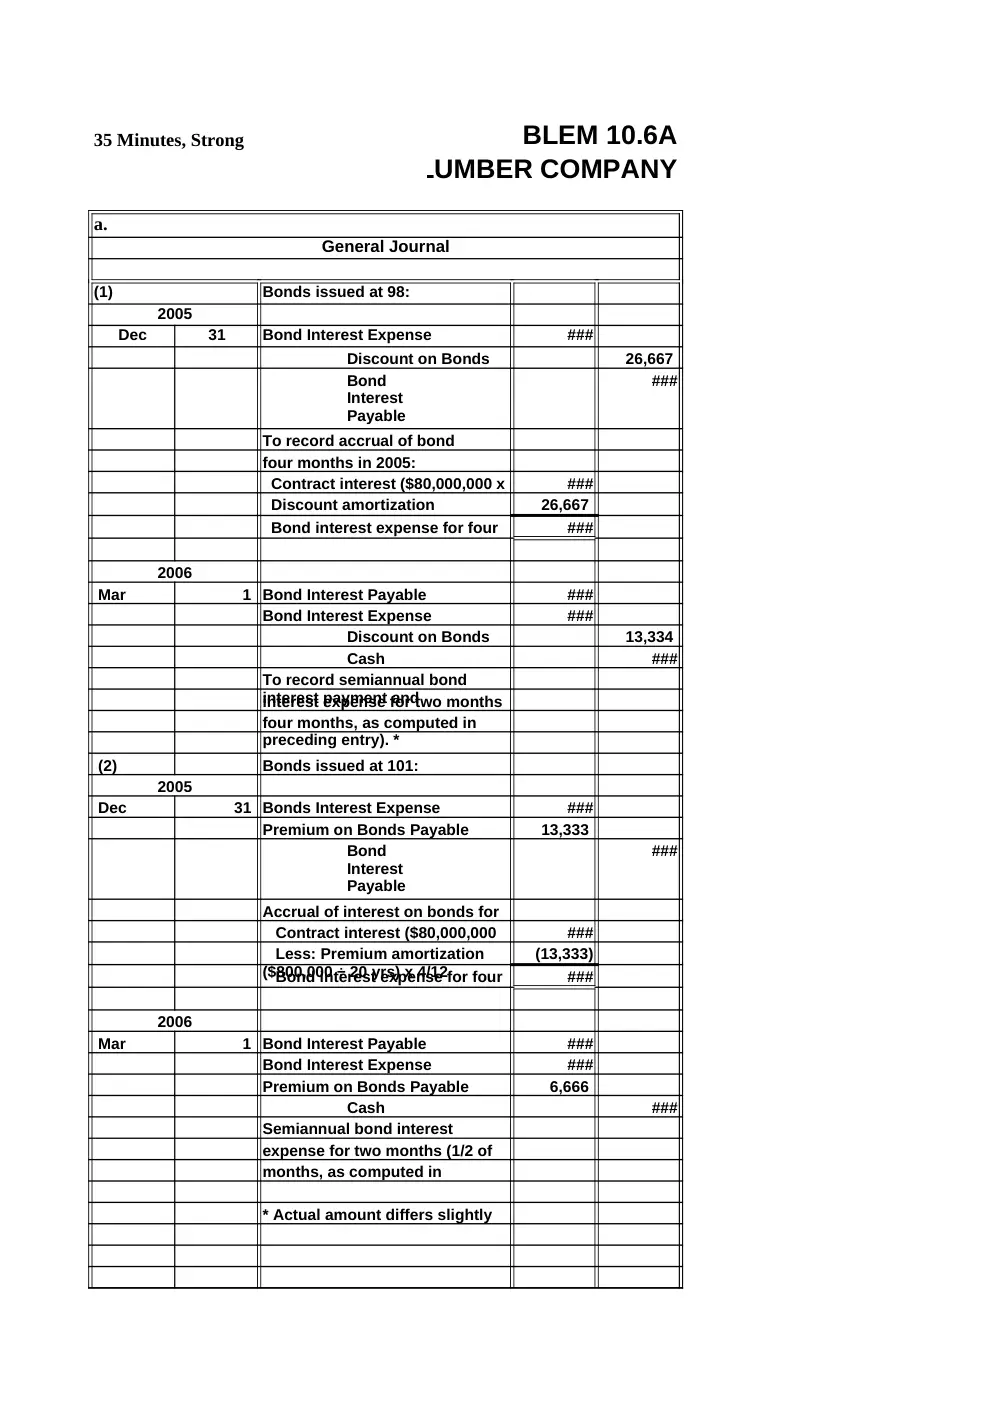
35 Minutes, Strong
BLEM 10.6A
LUMBER COMPANY
a.
General Journal
(1)
Bonds issued at 98:
2005
Dec
31
Bond Interest Expense
###
26,667
###
four months in 2005:
###
26,667
###
2006
Mar
1 Bond Interest Payable
###
Bond Interest Expense
###
13,334
Cash
###
(2)
Bonds issued at 101:
2005
Dec
31 Bonds Interest Expense
###
Premium on Bonds Payable
13,333
###
###
(13,333)
###
2006
Mar
1 Bond Interest Payable
###
Bond Interest Expense
###
Premium on Bonds Payable
6,666
Cash
###
Discount on Bonds
Payable
Bond
Interest
Payable
To record accrual of bond
interest expense for
Contract interest ($80,000,000 x
10% x 4/12)
Discount amortization
($1,600,000 ÷ 20 years) x 4/12
Bond interest expense for four
months
Discount on Bonds
Payable
To record semiannual bond
interest payment and
interest expense for two months
(1/2 of interest for
four months, as computed in
preceding entry). *
Bond
Interest
Payable
Accrual of interest on bonds for
four months:
Contract interest ($80,000,000
x 10% x 4/12)
Less: Premium amortization
($800,000 ÷ 20 yrs) x 4/12
Bond interest expense for four
months
Semiannual bond interest
payment and interest
expense for two months (1/2 of
interest for four
months, as computed in
preceding entry).*
* Actual amount differs slightly
due to rounding errors.
BLEM 10.6A
R COMPANY (concluded)
b.
Net bond liability at Dec. 31, 20
Bonds
Bonds
Issued
Issued
at 98
at 101
Bond payable
###
###
* Less: Discount on bonds payable (
###
** Add: Premium on bonds payable
746,667
###
###
* Discount amortized at Dec. 31, 2006:
Amount amortized in 2005 ………
$ 26,667
80,000
Discount amortized
###
** Premium amortized at Dec. 31, 2006:
Amount amortized in 2005 …………
$ 13,333
40,000
Premium amortized at 12/31
$ 53,333
c.
Net bond liability at Dec. 31,
2006:
Amount amortized in 2006 ($1,600,000 ¸ 20 years) …………………………………..
Amount amortized in 2006 ($800,000 ¸ 20 years) ……………………………………
The effective rate of interest would be higher under
assumption 1. The less that investors pay for bonds with a
given contract rate of interest, the higher the effective interest
rate they will earn.
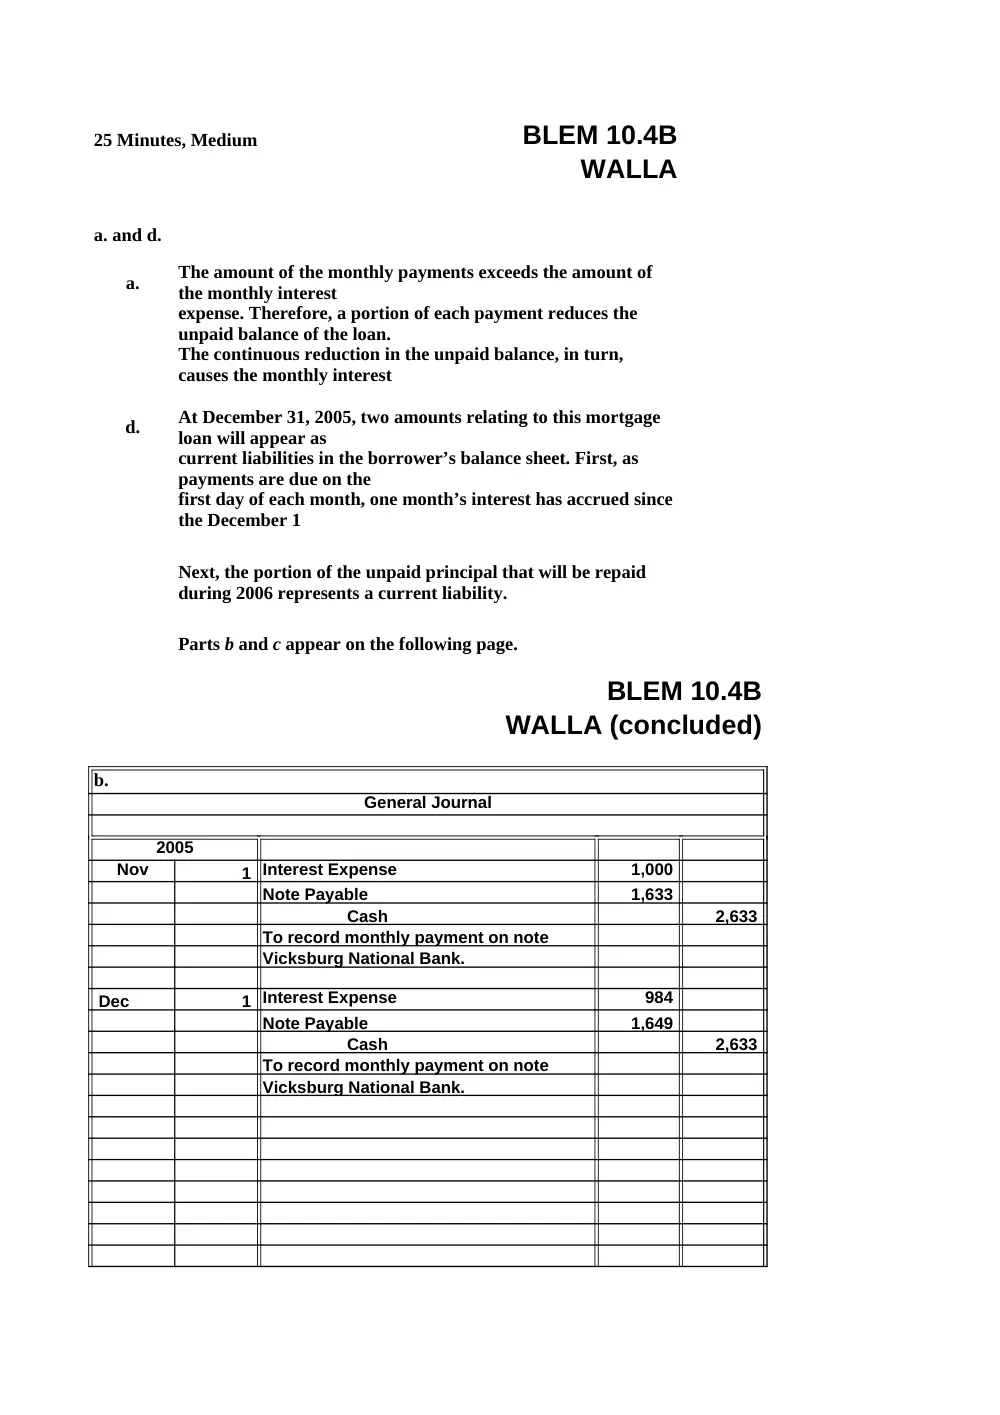
25 Minutes, Medium
BLEM 10.4B
WALLA
a. and d.
a.
d.
BLEM 10.4B
WALLA (concluded)
b.
General Journal
2005
Nov
1 Interest Expense
1,000
Note Payable
1,633
Cash
2,633
Vicksburg National Bank.
Dec
1 Interest Expense
984
Note Payable
1,649
Cash
2,633
Vicksburg National Bank.
The amount of the monthly payments exceeds the amount of
the monthly interest
expense. Therefore, a portion of each payment reduces the
unpaid balance of the loan.
The continuous reduction in the unpaid balance, in turn,
causes the monthly interest
At December 31, 2005, two amounts relating to this mortgage
loan will appear as
current liabilities in the borrower’s balance sheet. First, as
payments are due on the
first day of each month, one month’s interest has accrued since
the December 1
Next, the portion of the unpaid principal that will be repaid
during 2006 represents a current liability.
Parts b and c appear on the following page.
To record monthly payment on note
payable to
To record monthly payment on note
payable to
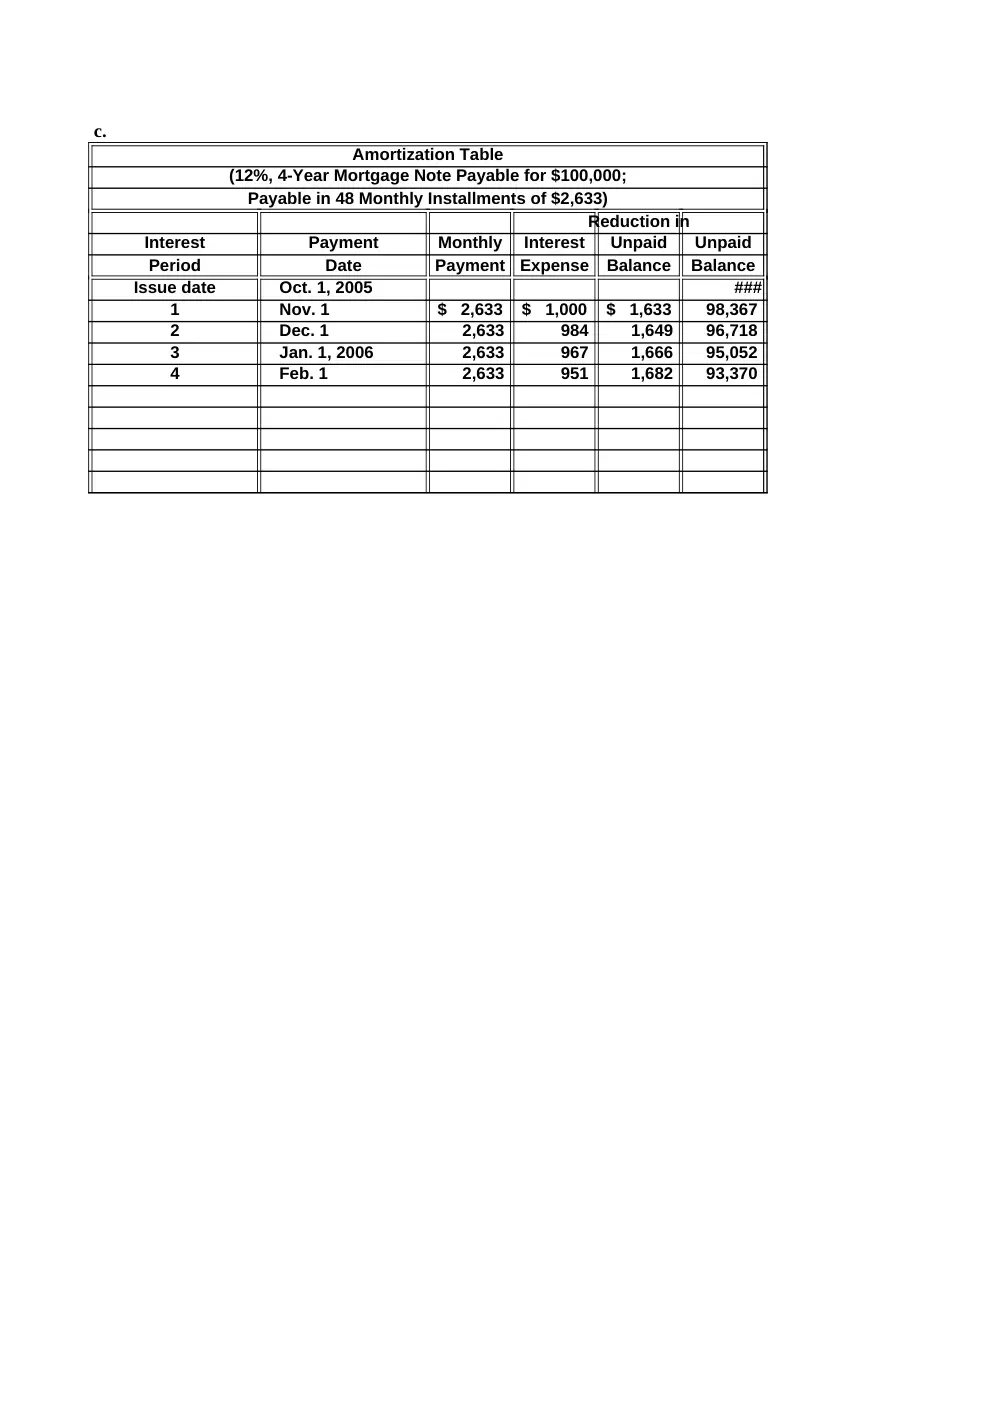
c.
Amortization Table
(12%, 4-Year Mortgage Note Payable for $100,000;
Payable in 48 Monthly Installments of $2,633)
Reduction in
Interest
Payment
Monthly
Interest
Unpaid
Unpaid
Period
Date
Payment
Expense Balance Balance
Issue date
Oct. 1, 2005
###
1
Nov. 1
$ 2,633 $ 1,000 $ 1,633 98,367
2
Dec. 1
2,633 984 1,649 96,718
3
Jan. 1, 2006
2,633 967 1,666 95,052
4
Feb. 1
2,633 951 1,682 93,370
35 Minutes, Strong
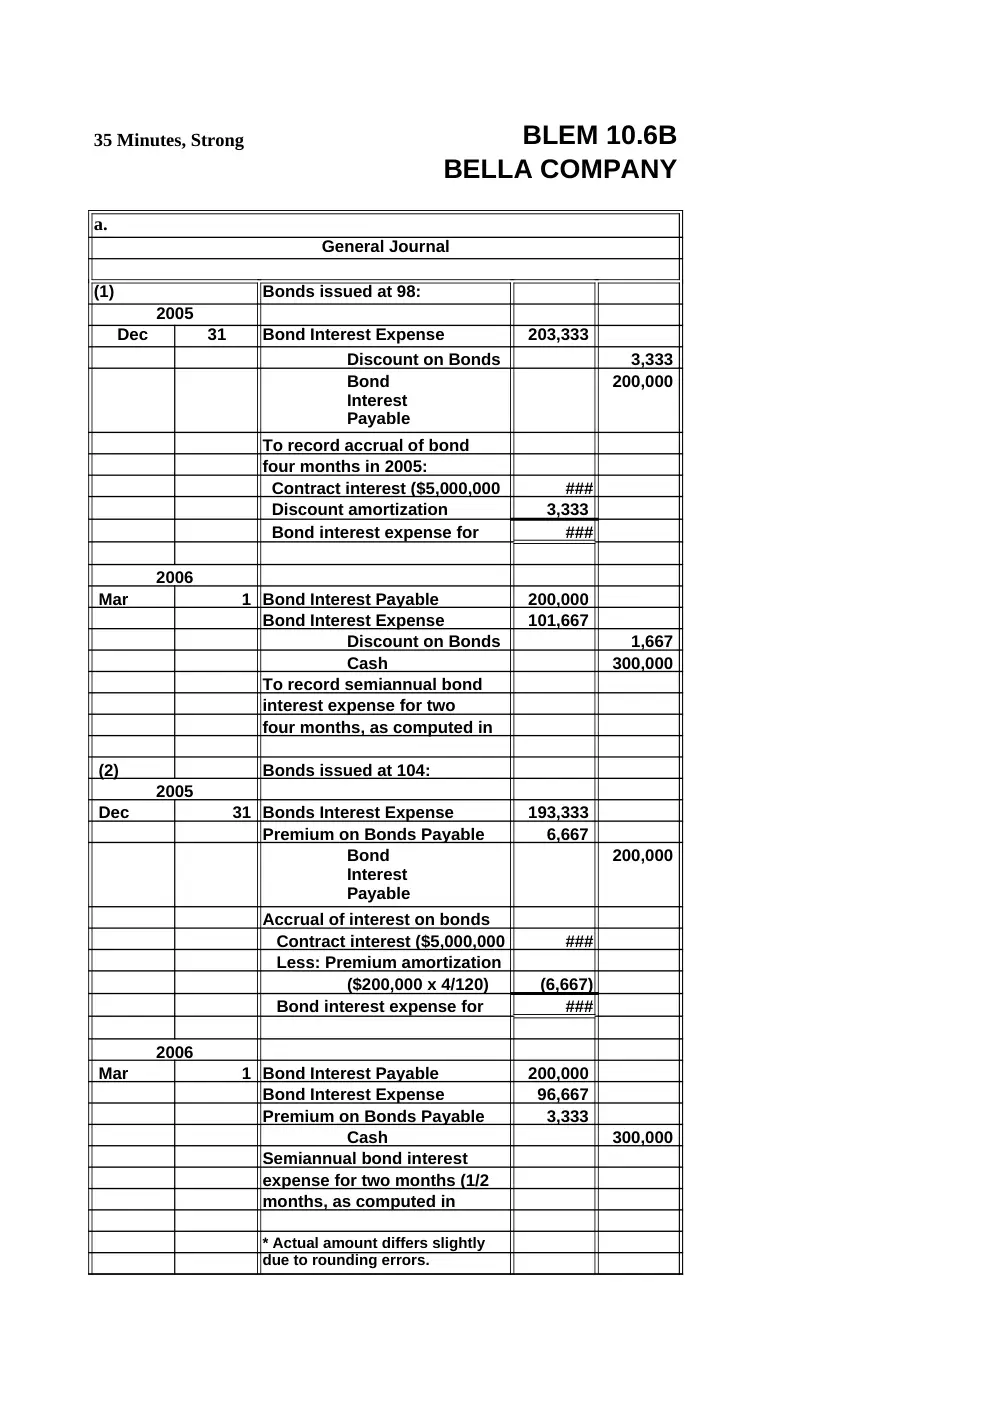
BLEM 10.6B
BELLA COMPANY
a.
General Journal
(1)
Bonds issued at 98:
2005
Dec
31
Bond Interest Expense
203,333
3,333
200,000
four months in 2005:
###
3,333
###
2006
Mar
1 Bond Interest Payable
200,000
Bond Interest Expense
101,667
1,667
Cash
300,000
(2)
Bonds issued at 104:
2005
Dec
31 Bonds Interest Expense
193,333
Premium on Bonds Payable
6,667
200,000
###
Less: Premium amortization
($200,000 x 4/120)
(6,667)
###
2006
Mar
1 Bond Interest Payable
200,000
Bond Interest Expense
96,667
Premium on Bonds Payable
3,333
Cash
300,000
Discount on Bonds
Payable
Bond
Interest
Payable
To record accrual of bond
interest expense for
Contract interest ($5,000,000
x 12% x 4/12)
Discount amortization
($100,000 x 4/120)
Bond interest expense for
four months
Discount on Bonds
Payable
To record semiannual bond
interest expense for two
months (1/2 of interest for
four months, as computed in
Bond
Interest
Payable
Accrual of interest on bonds
for four months:
Contract interest ($5,000,000
x 12% x 4/12)
Bond interest expense for
four months
Semiannual bond interest
payment and interest
expense for two months (1/2
of interest for four
months, as computed in
preceding entry).*
* Actual amount differs slightly
due to rounding errors.
BLEM 10.6B
BELLA (concluded)
b.
Net bond liability at Dec. 31, 20
Bonds
Bonds
Issued
Issued
at 98
at 104
Bond payable
###
###
* Less:Discount on bonds payable ( (86,667)
** Add:Premium on bonds payable
Net bond liability
173,333
###
###
* Discount amortized at Dec. 31, 2006:
Amount amortized in 2005 ………
$ 3,333
Amount amortized in 2006 ($100,000 x
10,000
Discount amortized
$ 13,333
** Premium amortized at Dec. 31, 2006:
Amount amortized in 2005 ………
$ 6,667
Amount amortized in 2006 ($200,000 x
20,000
Premium amortized at 12/31
$ 26,667
c.
The effective rate of interest would be higher under
assumption 1. The less that investors pay for bonds with a
given contract rate of interest, the higher the effective interest
rate they will earn.
45 Minutes, Strong
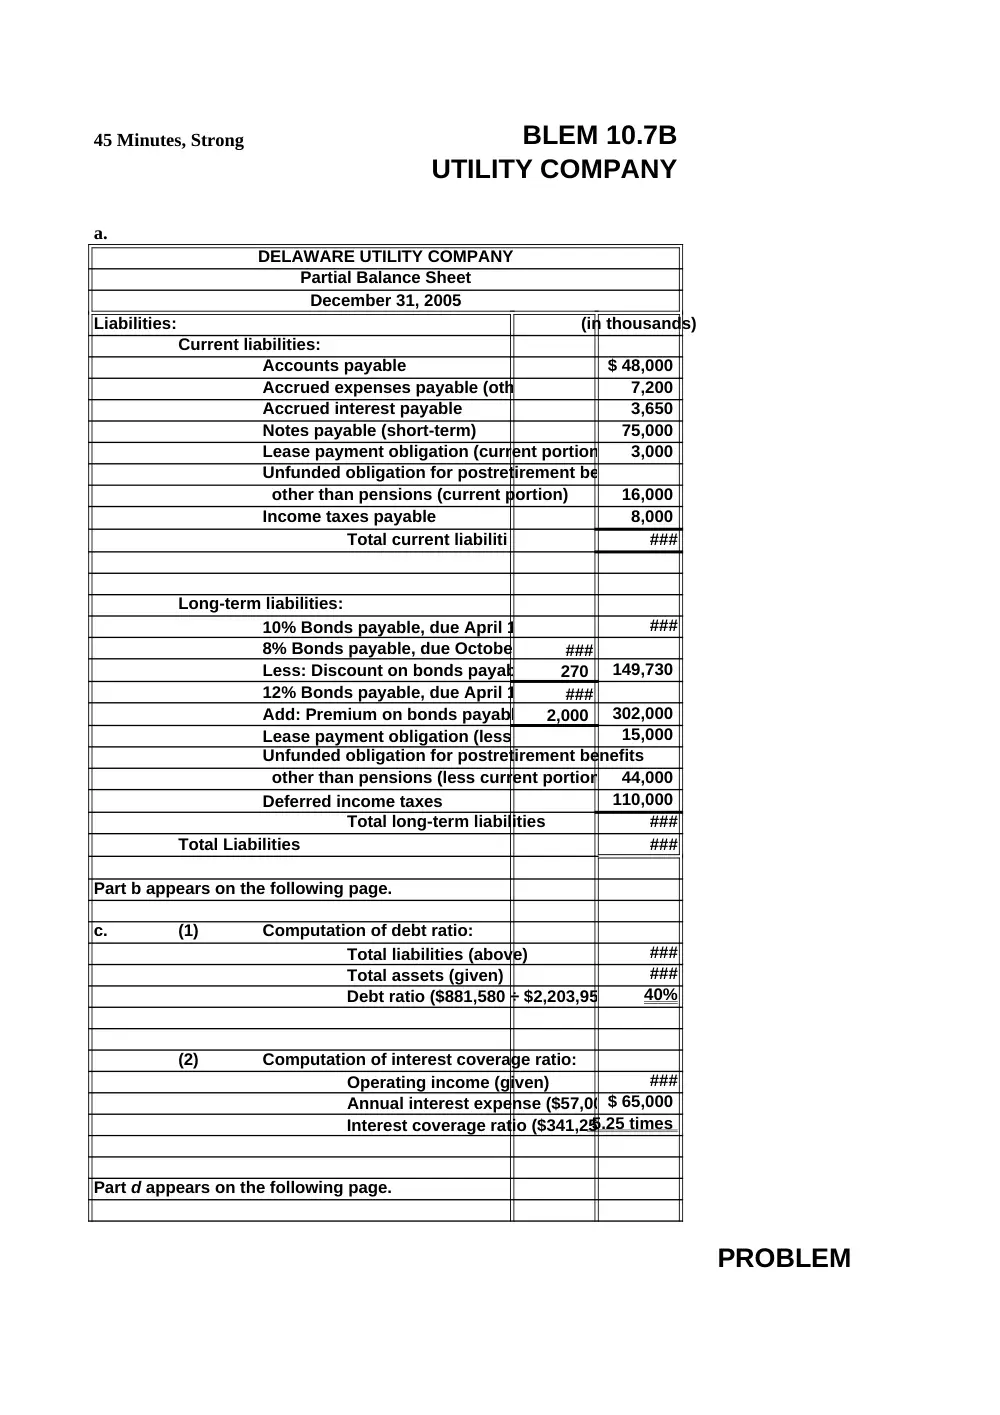
BLEM 10.7B
UTILITY COMPANY
a.
DELAWARE UTILITY COMPANY
Partial Balance Sheet
December 31, 2005
Liabilities:
(in thousands)
Current liabilities:
Accounts payable
$ 48,000
Accrued expenses payable (othe
7,200
Accrued interest payable
3,650
Notes payable (short-term)
75,000
Lease payment obligation (current portion 3,000
Unfunded obligation for postretirement ben
other than pensions (current portion)
16,000
Income taxes payable
8,000
Total current liabiliti
###
Long-term liabilities:
10% Bonds payable, due April 1
###
8% Bonds payable, due October
###
Less: Discount on bonds payab 270 149,730
12% Bonds payable, due April 1
###
Add: Premium on bonds payabl 2,000 302,000
Lease payment obligation (less
15,000
Unfunded obligation for postretirement benefits
other than pensions (less current portion 44,000
Deferred income taxes
110,000
Total long-term liabilities
###
Total Liabilities
###
Part b appears on the following page.
c.
(1)
Computation of debt ratio:
Total liabilities (above)
###
Total assets (given)
###
40%
(2)
Computation of interest coverage ratio:
Operating income (given)
###
Annual interest expense ($57,00 $ 65,000
5.25 times
PROBLEM 10.7B
Debt ratio ($881,580 ÷ $2,203,950)
Interest coverage ratio ($341,250
Part d appears on the following page.
(concluded)
b.
(1)
(2)
(3)
(4)
As the pension plan is fully funded, the company has no pension liability.
(5)
(6)
d.
DELAWARE UTILITY COMPANY
As the 10% bond issue is being refinanced on a long-term basis (that is, paid from
the proceeds of a long-term bond issue rather than from current assets), it is
classified as a long-term liability rather than a current liability.
The 8% bonds will be repaid from a bond sinking fund rather than from current
assets. Therefore, this liability continues to be classified as long-term, despite its
maturity date in less than one year.
The portion of the capitalized lease payment obligation that will be repaid within
one year ($3,000) is classified as a current liability, and the remainder of this
obligation is classified as long-term. The payments applicable to operating leases
will be recognized as rental expense in the periods in which these costs are
incurred.
The $16,000 portion of the unfunded liability for nonpension postretirement benefits
that will be funded within one year is a current liability, and the remaining $44,000
($60,000 - $16,000) is classified as long-term.
Income taxes payable relate to the current year’s income tax return and, therefore,
are a current liability. Although deferred income taxes can include a current
portion, all of the deferred income taxes are stated to be a long-term liability.
Based solely upon its debt ratio and interest coverage ratio, Delaware Utility appears to be a
good credit risk. One must consider, however, that Delaware Utility is a utility company, not a
business organization that battles numerous competitors on a daily basis. Utility companies
enjoy a “captive market” on a long-term basis. Also, their rates are regulated to allow them to
recover their costs and to earn a reasonable profit, except in unusual circumstances.
In summary, the fact that Delaware Utility is a profitable utility company with a reasonable
debt ratio and interest coverage ratio makes this business entity a relatively low long-term
credit risk.
OBLEM 10.7B
(concluded)
n liability.
TY COMPANY
(that is, paid from
nt assets), it is
than from current
-term, despite its
l be repaid within
ainder of this
o operating leases
se costs are
ostretirement benefits
e remaining $44,000
turn and, therefore,
ude a current
-term liability.
ity appears to be a
tility company, not a
Utility companies
ated to allow them to
umstances.
with a reasonable
ly low long-term
45 Minutes, Strong
BLEM 10.7A
ESOTA SATELLITE
NE CORPORATION
a.
MINNESOTA SATELLITE TELEPHONE CORPORATION
Partial Balance Sheet
December 31, 2005
Liabilities:
(in thousands)
Current liabilities:
Accounts payable
$ 65,600
Accrued expenses payable (othe
11,347
Accrued interest payable
7,333
Notes payable (short-term)
110,000
Lease payment obligation (current portion 4,621
Unfunded obligation for postretirement ben
other than pensions (current portion)
18,000
Income taxes payable
17,300
Total current liabiliti
###
Long-term liabilities:
6-3/4% Bonds payable, due Febr
###
8-1/2% Bonds payable, due June
###
Less: Discount on bonds payab 260 249,740
11% Bonds payable, due June 1
###
Add: Premium on bonds payabl 1,700 301,700
Lease payment obligation (less
18,979
Unfunded obligation for postretirement benefits
other than pensions (less current portion 54,000
Deferred income taxes
130,000
Total long-term liabilities
###
Total liabilities
###
Part b appears on the following page.
c.
(1)
Computation of debt ratio:
Total liabilities (above)
###
Total assets (given)
###
52%
(2)
Computation of interest coverage ratio:
Operating income (given)
###
Annual interest expense ($61,00 $ 78,000
3.6 times
Debt ratio ($1,088,620 ÷ $2,093,500)
Interest coverage ratio ($280,000
Part d appears on the following page.
PROBLEM 10.7A
MINNESOTA SATELLITE
LEPHONE CORPORATION
(concluded)
b.
(1)
(2)
(3)
(4)
As the pension plan is fully funded, the company has no pension liability.
(5)
(6)
d.
As the 6 3/4% bond issue is being refinanced on a long-term basis (that is, paid from
the proceeds of a long-term bond issue rather than from current assets), it is
classified as a long-term liability rather than a current liability.
The 8 1/2% bonds will be repaid from a bond sinking fund rather than from current
assets. Therefore, this liability continues to be classified as long-term, despite its
maturity date in less than one year.
The portion of the capitalized lease payment obligation that will be repaid within
one year ($4,621) is classified as a current liability, and the remainder of this
obligation is classified as long-term. The payments applicable to operating leases
will be recognized as rental expense in the periods in which these costs are
incurred.
The $18,000 portion of the unfunded liability for nonpension postretirement benefits
that will be funded within one year is a current liability, and the remaining $54,000
($72,000 - $18,000) is classified as long-term.
Income taxes payable relate to the current year’s income tax return and, therefore,
are a current liability. Although deferred income taxes can include a current
portion, all of the deferred income taxes are stated to be a long-term liability.
Based solely upon its debt ratio and interest coverage ratio, Minnesota Satellite Telephone
Corporation appears to be a good credit risk. One must consider, however, that Minnesota
Satellite Telephone Corporation is a telephone company, not a business organization that
battles hundreds of numerous competitors on a daily basis. Telephone companies enjoy a
somewhat of a “captive market” on a long-term basis. Also, their rates are often regulated to
allow them to recover their costs and to earn a reasonable profit, except in unusual
circumstances.
In summary, the fact that Minnesota Satellite Telephone Corporation is a profitable telephone
company with a reasonable debt ratio and interest coverage ratio makes this business entity an
outstanding long-term credit risk.
OBLEM 10.7A
A SATELLITE
ORPORATION
(concluded)
n liability.
sis (that is, paid from
nt assets), it is
her than from current
-term, despite its
l be repaid within
ainder of this
o operating leases
se costs are
ostretirement benefits
e remaining $54,000
turn and, therefore,
ude a current
-term liability.
tellite Telephone
r, that Minnesota
ganization that
mpanies enjoy a
e often regulated to
n unusual
profitable telephone
his business entity an