
ACCT 210 Lecture, Fall 2004
American University of Beirut · Financial Accounting · 51 pages
Showing the first 10 of 51 pages. Download the PDF to see all of it.
More ACCT 210 files
Show the text of this lab
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-1
The Accounting Cycle
Accruals and Deferrals
Chapter
4
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-2
Learning Objective
Learning Objective
LO1
To explain the purpose
of adjusting entries.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-3
At the end of the
period, we need to
make adjusting entries
to get the accounts up
to date for the financial
statements.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-4
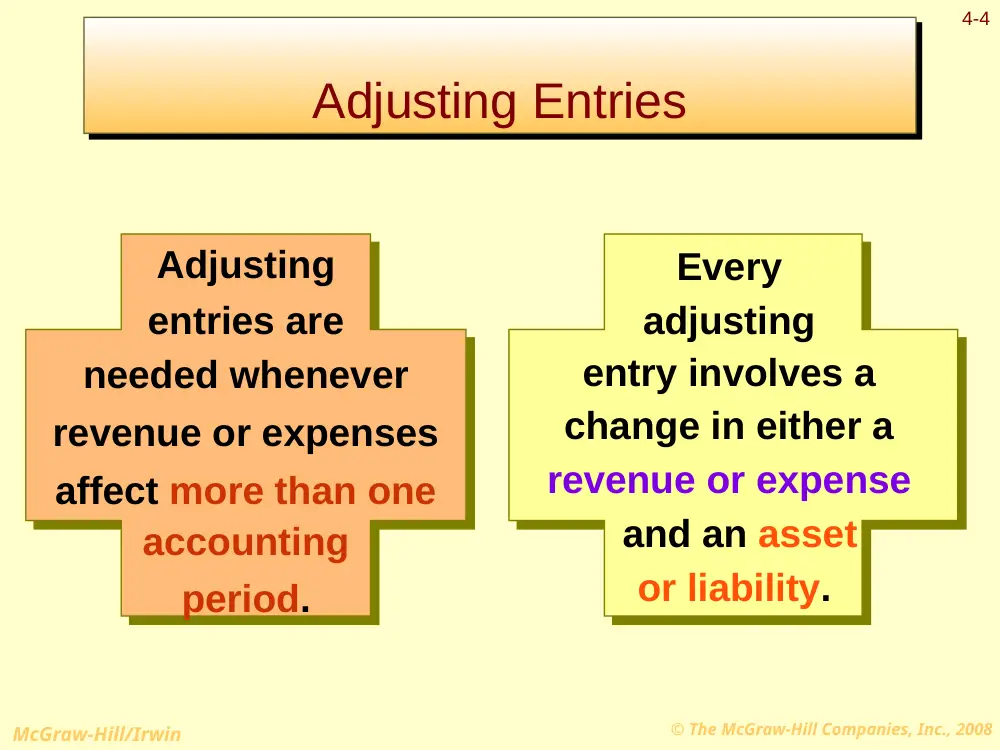
Adjusting
entries are
needed whenever
revenue or expenses
affect more than one
accounting
period.
Every
adjusting
entry involves a
change in either a
revenue or expense
and an asset
or liability.
Adjusting Entries
Adjusting Entries
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-5
Learning Objective
Learning Objective
LO2
To describe and
prepare the four basic
types of adjusting
entries.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-6
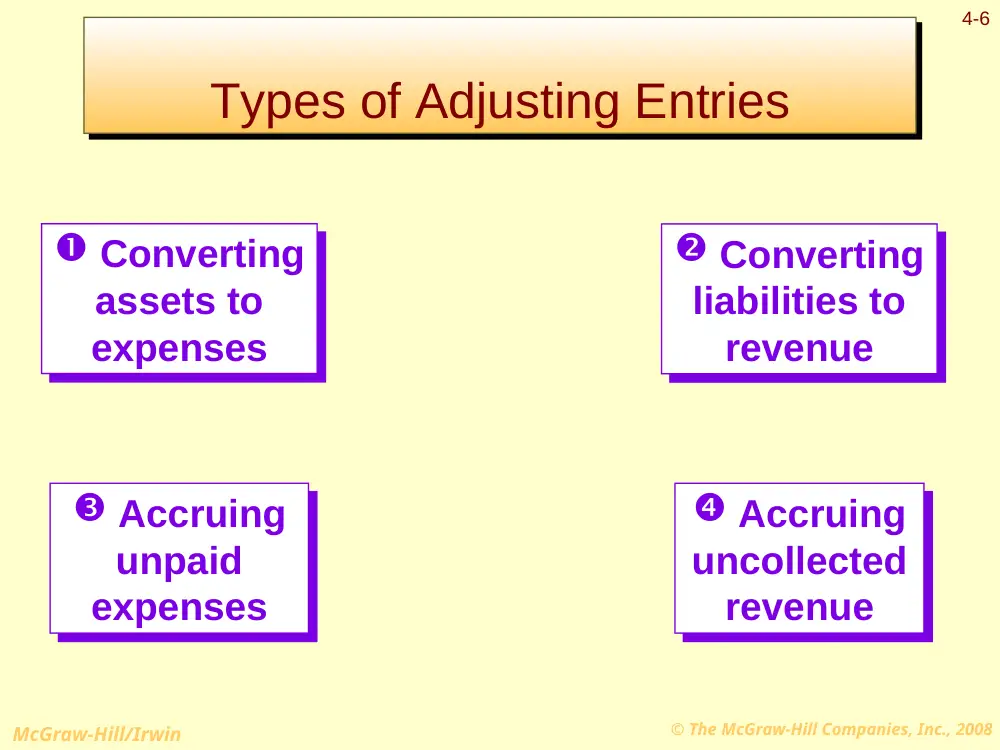
Converting
assets to
expenses
Converting
assets to
expenses
Accruing
unpaid
expenses
Accruing
unpaid
expenses
Converting
liabilities to
revenue
Converting
liabilities to
revenue
Accruing
uncollected
revenue
Accruing
uncollected
revenue
Types of Adjusting Entries
Types of Adjusting Entries
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-7
Learning Objective
Learning Objective
LO3
To prepare adjusting
entries to convert assets
to expenses.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-8
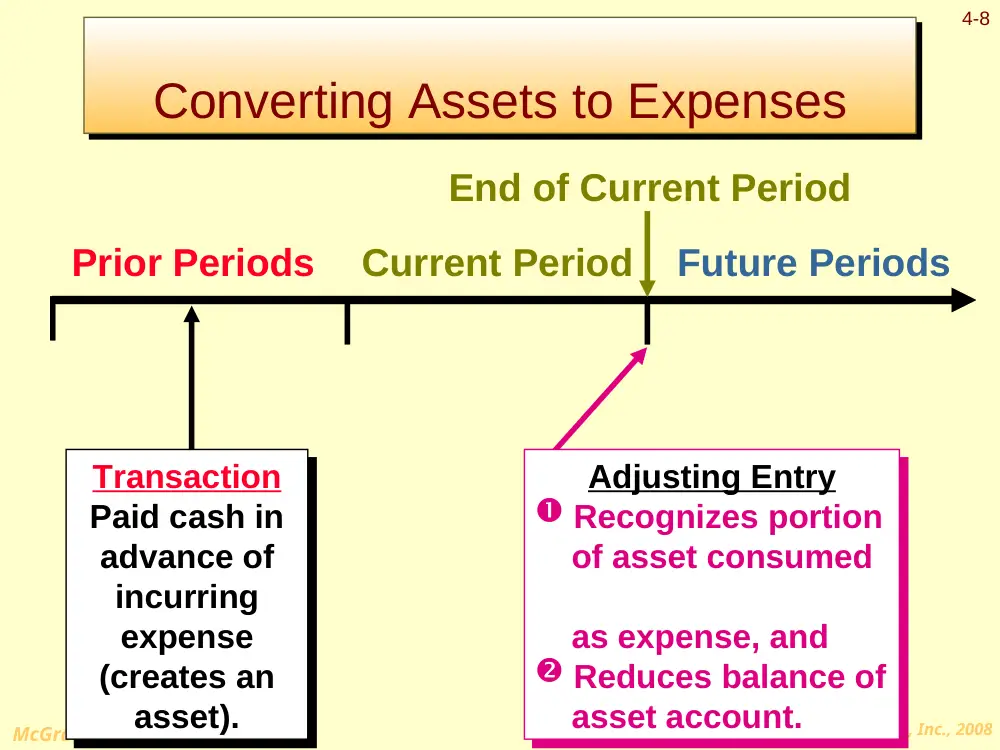
Prior Periods
Current Period
Future Periods
Transaction
Paid cash in
advance of
incurring
expense
(creates an
asset).
Transaction
Paid cash in
advance of
incurring
expense
(creates an
asset).
End of Current Period
Adjusting Entry
Recognizes portion
of asset consumed
as expense, and
Reduces balance of
asset account.
Adjusting Entry
Recognizes portion
of asset consumed
as expense, and
Reduces balance of
asset account.
Converting Assets to Expenses
Converting Assets to Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-9
Examples Include:
Depreciation
Supplies
Expiring Insurance Policies
Converting Assets to Expenses
Converting Assets to Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-10
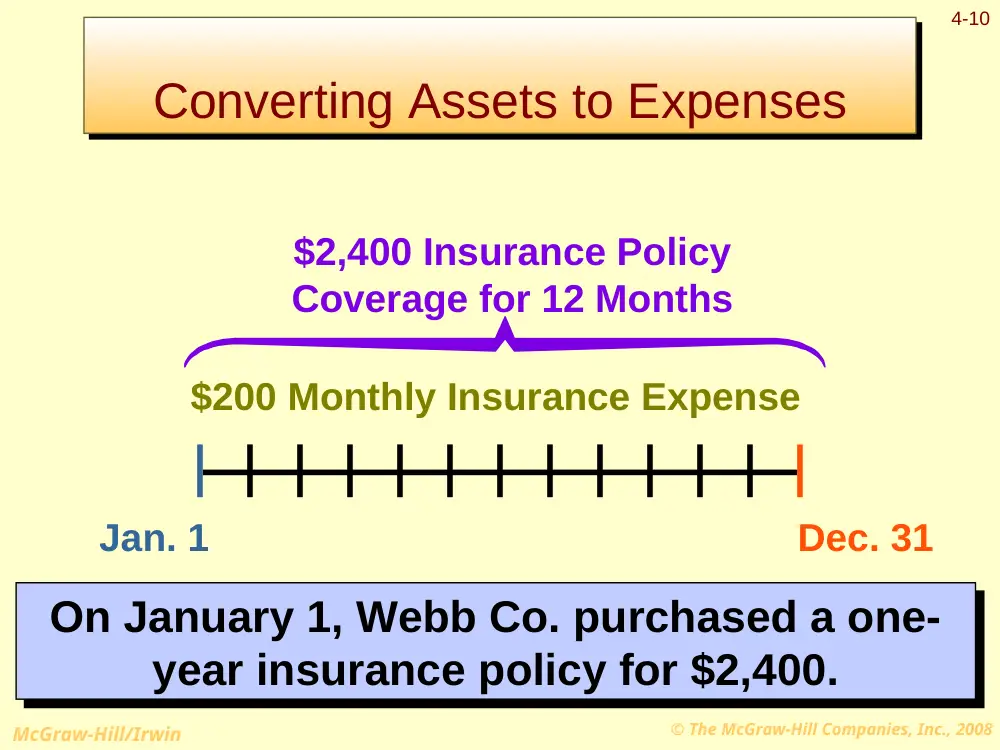
Jan. 1
Dec. 31
$2,400 Insurance Policy
Coverage for 12 Months
$200 Monthly Insurance Expense
On January 1, Webb Co. purchased a one-
year insurance policy for $2,400.
On January 1, Webb Co. purchased a one-
year insurance policy for $2,400.
Converting Assets to Expenses
Converting Assets to Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-11
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Jan. 1 Unexpired Insurance
2,400
Cash
2,400
Purchase a one-year insurance policy.
Initially, costs that benefit more than one
accounting period are recorded as assets.
Initially, costs that benefit more than one
accounting period are recorded as assets.
Converting Assets to Expenses
Converting Assets to Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-12
The costs are expensed as they are used to
generate revenue.
The costs are expensed as they are used to
generate revenue.
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Monthly Adjusting Entry for Insurance
Jan. 31 Insurance Expense
200
Unexpired Insurance
200
Insurance expense for January.
Converting Assets to Expenses
Converting Assets to Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-13
Insurance Expense
1/31
200
Unexpired Insurance
1/1
2,400
1/31
200
Bal.
2,200
Income Statement
Cost of assets
used this period to
generate revenue.
Income Statement
Cost of assets
used this period to
generate revenue.
Balance Sheet
Cost of assets
that benefit
future periods.
Balance Sheet
Cost of assets
that benefit
future periods.
Converting Assets to Expenses
Converting Assets to Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-14
Depreciation is the systematic allocation
of the cost of a depreciable asset to
expense.
Depreciation is the systematic allocation
of the cost of a depreciable asset to
expense.
Depreciable assets are physical objects
that retain their size and shape but lose
their economic usefulness over time.
Depreciable assets are physical objects
that retain their size and shape but lose
their economic usefulness over time.
The Concept of Depreciation
The Concept of Depreciation
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-15
The portion of an asset’s utility that is used
up must be expensed in the period used.
The portion of an asset’s utility that is used
up must be expensed in the period used.
Cash
(credit)
Cash
(credit)
Fixed
Asset
(debit)
Fixed
Asset
(debit)
On date
when initial
payment is
made . . .
The asset’s
usefulness is
partially
consumed
during the
period.
At end of
period . . .
Depreciation
Expense
(debit)
Depreciation
Expense
(debit)
Accumulated
Depreciation
(credit)
Accumulated
Depreciation
(credit)
The Concept of Depreciation
The Concept of Depreciation
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-16
On May 2, 2007, JJ’s Lawn Care Service
purchased a lawn mower with a useful
life of 50 months for $2,500 cash.
Using the straight-line method, calculate
the monthly depreciation expense.
$2,500
50
$50 =
$50
Depreciation
expense (per
period)
=
Cost of the asset
Estimated useful life
Depreciation Is Only an Estimate
Depreciation Is Only an Estimate
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-17
JJ’s Lawn Care Service would make the
following adjusting entry.
JJ’s Lawn Care Service would make the
following adjusting entry.
GENERAL JOURNAL
Date
Account Titles and Explanation
P
RDebit
Credit
May 31 Depreciation Expense: Equipment
50
Accumulated Depreciation: Equipment
50
To record one month's depreciation.
Contra-asset
Contra-asset
Depreciation Is Only an Estimate
Depreciation Is Only an Estimate
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-18
JJ’s $15,000 truck is depreciated over 60
months as follows:
JJ’s $15,000 truck is depreciated over 60
months as follows:
GENERAL JOURNAL
Date
Account Titles and Explanation
P
RDebit
Credit
May 31 Depreciation Expense: Truck
250
Accumulated Depreciation: Truck
250
To record one month's depreciation.
$15,00060 months = $250 per month
$15,00060 months = $250 per month
Depreciation Is Only an Estimate
Depreciation Is Only an Estimate
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-19
Accumulated depreciation would
appear on the balance sheet as
follows:
Accumulated depreciation would
appear on the balance sheet as
follows:
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-20
Learning Objective
Learning Objective
LO4
To prepare adjusting
entries to convert
liabilities to revenue.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-21
Prior Periods
Current Period
Future Periods
Transaction
Collect cash
in advance of
earning
revenue
(creates a
liability).
Transaction
Collect cash
in advance of
earning
revenue
(creates a
liability).
End of Current Period
Adjusting Entry
Recognizes portion
earned as revenue,
and
Reduces balance of
liability account.
Adjusting Entry
Recognizes portion
earned as revenue,
and
Reduces balance of
liability account.
Converting Liabilities to Revenue
Converting Liabilities to Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-22
Examples Include:
Airline Ticket Sales
Sports Teams’ Sales of
Season Tickets
Converting Liabilities to Revenue
Converting Liabilities to Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-23
Jan. 1
Dec. 31
$6,000 Rental Contract
Coverage for 12 Months
$500 Monthly Rental Revenue
On January 1, Webb Co. received $6,000 in
advance for a one-year rental contract.
On January 1, Webb Co. received $6,000 in
advance for a one-year rental contract.
Converting Liabilities to Revenue
Converting Liabilities to Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-24
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Jan. 1 Cash
6,000
Unearned Rental Revenue
6,000
Collected $6,000 in advance for rent.
Initially, revenues that benefit more than one
accounting period are recorded as liabilities.
Initially, revenues that benefit more than one
accounting period are recorded as liabilities.
Converting Liabilities to Revenue
Converting Liabilities to Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-25
Over time, the revenue is recognized as it is
earned.
Over time, the revenue is recognized as it is
earned.
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Monthly Adjusting Entry for Rent Revenue
Jan. 31 Unearned Rental Revenue
500
Rental Revenue
500
Rental revenue for January.
Converting Liabilities to Revenue
Converting Liabilities to Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-26
Rental Revenue
1/31
500
Unearned Rental Revenue
1/31
500
1/1
6,000
Bal.
5,500
Income Statement
Revenue earned
this period.
Income Statement
Revenue earned
this period.
Balance Sheet
Liability for
future periods.
Balance Sheet
Liability for
future periods.
Converting Liabilities to Revenue
Converting Liabilities to Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-27
Learning Objective
Learning Objective
LO5
To prepare adjusting
entries to accrue unpaid
expenses.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-28
Prior Periods
Current Period
Future Periods
Transaction
Pay cash in
settlement of
liability.
Transaction
Pay cash in
settlement of
liability.
End of Current Period
Adjusting Entry
Recognizes expense
incurred, and
Records liability for
future payment.
Adjusting Entry
Recognizes expense
incurred, and
Records liability for
future payment.
Accruing Unpaid Expenses
Accruing Unpaid Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-29
Examples Include:
Interest
Wages and Salaries
Property Taxes
Hey, when
do we get
paid?
Accruing Unpaid Expenses
Accruing Unpaid Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-30
Monday,
May 29
Friday,
June 2
$3,000 Wages
Expense
On May 31, Webb Co. owes wages of
$3,000. Payday is Friday, June 2.
On May 31, Webb Co. owes wages of
$3,000. Payday is Friday, June 2.
Wednesday,
May 31
Accruing Unpaid Expenses
Accruing Unpaid Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-31
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
May 31 Wages Expense
3,000
Wages Payable
3,000
To accrue wages owed to employees.
Initially, an expense and a liability are
recorded.
Initially, an expense and a liability are
recorded.
Accruing Unpaid Expenses
Accruing Unpaid Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-32
Wages Expense
5/31
3,000
Wages Payable
5/31
3,000
Income Statement
Cost incurred this
period to generate
revenue.
Income Statement
Cost incurred this
period to generate
revenue.
Balance Sheet
Liability to be
paid in a future
period.
Balance Sheet
Liability to be
paid in a future
period.
Accruing Unpaid Expenses
Accruing Unpaid Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-33
Monday,
May 29
Friday,
June 2
$5,000 Weekly Wages
Let’s look at the entry for June 2.
Let’s look at the entry for June 2.
Wednesday,
May 31
$2,000 Wages
Expense
$3,000 Wages
Expense
Accruing Unpaid Expenses
Accruing Unpaid Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-34
The liability is extinguished when the debt is
paid.
The liability is extinguished when the debt is
paid.
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
June 2 Wages Expense (for June)
2,000
Wages Payable (accrued in May)
3,000
Cash
5,000
Weekly payroll for May 29-June 2.
Accruing Unpaid Expenses
Accruing Unpaid Expenses
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-35
Learning Objective
Learning Objective
LO6
To prepare adjusting
entries to accrue
uncollected revenue.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-36
Prior Periods
Current Period
Future Periods
Transaction
Collect cash
in settlement
of receivable.
Transaction
Collect cash
in settlement
of receivable.
End of Current Period
Adjusting Entry
Recognizes revenue
earned but not yet
recorded, and
Records receivable.
Adjusting Entry
Recognizes revenue
earned but not yet
recorded, and
Records receivable.
Accruing Uncollected Revenue
Accruing Uncollected Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-37
Examples Include:
Interest Earned
Work Completed But Not
Yet Billed to Customer
Accruing Uncollected Revenue
Accruing Uncollected Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-38
Saturday,
Jan. 15
Tuesday,
Feb. 15
$170 Interest
Revenue
On Jan. 31, the bank owes Webb Co.
interest of $170. Interest is paid on the 15th
day of each month.
On Jan. 31, the bank owes Webb Co.
interest of $170. Interest is paid on the 15th
day of each month.
Monday,
Jan. 31
Accruing Uncollected Revenue
Accruing Uncollected Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-39
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Jan. 31 Interest Receivable
170
Interest Revenue
170
To recognize interest revenue.
Initially, the revenue is recognized and a
receivable is created.
Initially, the revenue is recognized and a
receivable is created.
Accruing Uncollected Revenue
Accruing Uncollected Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-40
Interest Revenue
1/31
170
Interest Receivable
1/31
170
Income Statement
Revenue earned
this period.
Income Statement
Revenue earned
this period.
Balance Sheet
Receivable to
be collected in a
future period.
Balance Sheet
Receivable to
be collected in a
future period.
Accruing Uncollected Revenue
Accruing Uncollected Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-41
Saturday,
Jan. 15
Tuesday,
Feb. 15
$320 Monthly Interest
$170 Interest
Revenue
Let’s look at the entry for February 15.
Let’s look at the entry for February 15.
Monday,
Jan. 31
$150 Interest
Revenue
Accruing Uncollected Revenue
Accruing Uncollected Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-42
The receivable is collected in a future period.
The receivable is collected in a future period.
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Feb. 15 Cash
320
Interest Revenue (for February)
150
Interest Receivable (accrued Jan. 31)
170
To record interest received.
Accruing Uncollected Revenue
Accruing Uncollected Revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-43
As a corporation earns taxable income, it
incurs income taxes expense, and also a
liability to governmental tax authorities.
As a corporation earns taxable income, it
incurs income taxes expense, and also a
liability to governmental tax authorities.
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Dec. 31 Income Taxes Expense
780
Income Taxes Payable
780
Estimated income taxes applicable to
taxable income earned in December.
Accruing Income Taxes Expense: The
Final Adjusting Entry
Accruing Income Taxes Expense: The
Final Adjusting Entry
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-44
Learning Objective
Learning Objective
LO7
To explain how the
principles of realization
and matching relate to
adjusting entries.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-45
Costs are matched with revenue
in two ways:
Costs are matched with revenue
in two ways:
Direct association of costs
with specific revenue
transactions.
Direct association of costs
with specific revenue
transactions.
Systematic allocation of costs
over the “useful life” of the
expenditure.
Systematic allocation of costs
over the “useful life” of the
expenditure.
Adjusting Entries and Accounting
Principles
Adjusting Entries and Accounting
Principles
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-46
Learning Objective
Learning Objective
LO8
To explain the concept
of materiality.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-47
An item is “material” if knowledge of the
item might reasonably influence the
decisions of users of financial statements.
An item is “material” if knowledge of the
item might reasonably influence the
decisions of users of financial statements.
Supplies
Lightbulbs
Many companies
immediately charge
the cost of
immaterial items to
expense.
The Concept of Materiality
The Concept of Materiality
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-48
Learning Objective
Learning Objective
LO9
To prepare an adjusted
trial balance and
describe its purpose.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-49
Journalize
transactions.
Post entries to
the ledger
accounts.
Prepare trial
balance.
Make end-of-
year
adjustments.
Prepare adjusted
trial balance.
Let’s look at JJ’s Lawn Care
Services’ adjusted trial balance.
Let’s look at JJ’s Lawn Care
Services’ adjusted trial balance.
Effects of the Adjusting Entries
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-50
JJ's Lawn Care Service
Adjusted Trial Balance
May 31, 2007
Cash
3,925
$
Accounts receivable
75
Tools & equipment
2,650
Accum. depreciation: tools & eq.
50
$
Truck
15,000
Accum. depreciation: truck
250
Notes payable
13,000
Accounts payable
150
Capital stock
8,000
Dividends
200
Sales revenue
750
Gasoline expense
50
Depreciation exp.: tools & eq.
50
Depreciation exp.: truck
250
Total
22,200
$
22,200
$
All balances
are taken from
the ledger
accounts on
May 31 after
preparing the
two
depreciation
adjusting
entries.
Adjusted Trial Balance
Adjusted Trial Balance
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
4-51
End of Chapter 4
End of Chapter 4