
ACCT 210 Lecture, Fall 2006
American University of Beirut · Financial Accounting · 72 pages



Showing the first 10 of 72 pages. Download the PDF to see all of it.
More ACCT 210 files
Show the text of this lab
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-1
Merchandising
Activities
Chapter
6
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-2
Learning Objective
Learning Objective
LO1
To describe the
operating cycle of a
merchandising
company.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-3
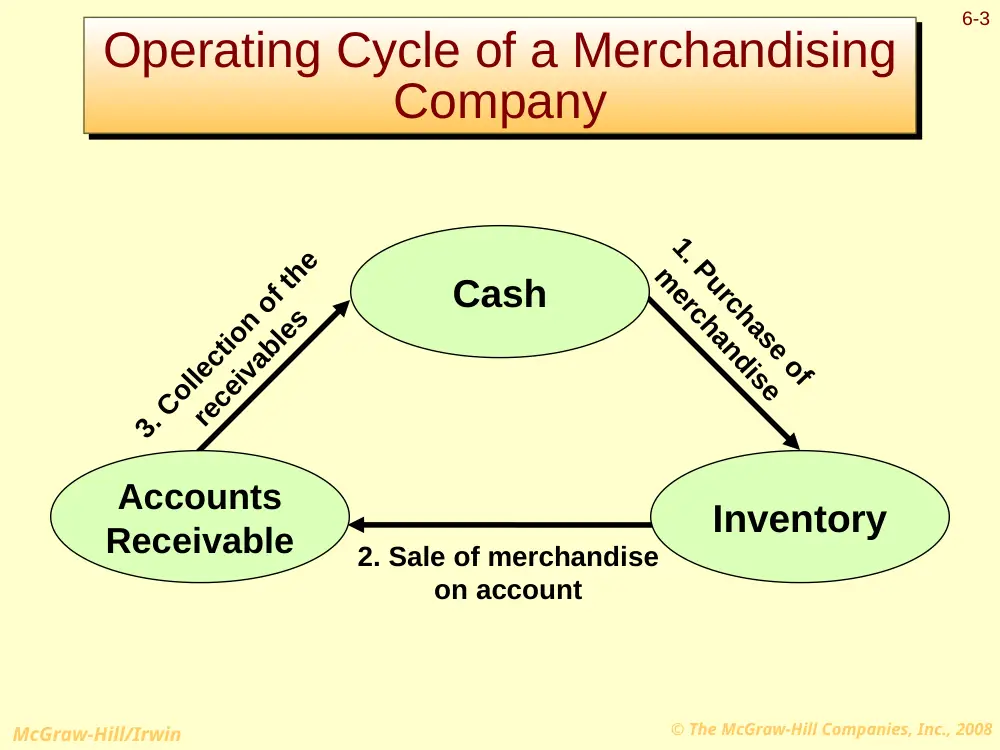
Operating Cycle of a Merchandising
Company
Operating Cycle of a Merchandising
Company
1. Purchase of
merchandise
3. Collection of the
receivables
2. Sale of merchandise
on account
Cash
Inventory
Accounts
Receivable
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-4
Comparing Merchandising Activities with
Manufacturing Activities
Comparing Merchandising Activities with
Manufacturing Activities
Merchandising
Company
Purchase
inventory in
ready-to-sell
condition.
Manufacturing
Company
Manufacture
inventory and
have a longer
and more
complex
operating cycle.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-5
Retailers and Wholesalers
Retailers and Wholesalers
Retailers sell
merchandise directly
to the public.
Wholesalers buy
merchandise from
several different
manufacturers and
then sell this
merchandise to
several retailers.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-6
Learning Objective
Learning Objective
LO2
To understand the
components of a
merchandising
company’s income
statement.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-7
Income Statement of a
Merchandising Company
Income Statement of a
Merchandising Company
Computer City
Condensed Income Statement
For the Year Ended December 31, 2007
Revenue from sales
900,000
$
Less: Cost of goods sold
540,000
Gross profit
360,000
$
Less: Expenses
270,000
Net income
90,000
$
Cost of
goods sold
represents
the expense
of goods
that are
sold to
customers.
Gross profit is a useful means of measuring
the profitability of sales transactions.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-8
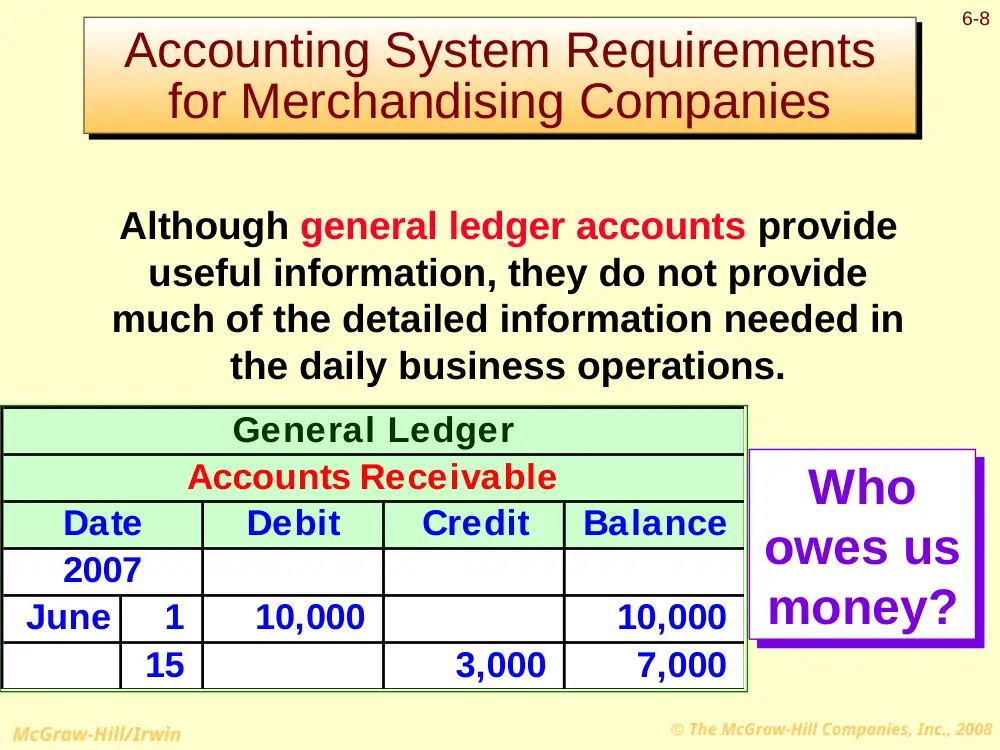
Accounting System Requirements
for Merchandising Companies
Accounting System Requirements
for Merchandising Companies
General Ledger
Accounts Receivable
Date
Debit
Credit
Balance
2007
June
1
10,000
10,000
15
3,000
7,000
Although general ledger accounts provide
useful information, they do not provide
much of the detailed information needed in
the daily business operations.
Who
owes us
money?
Who
owes us
money?
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-9
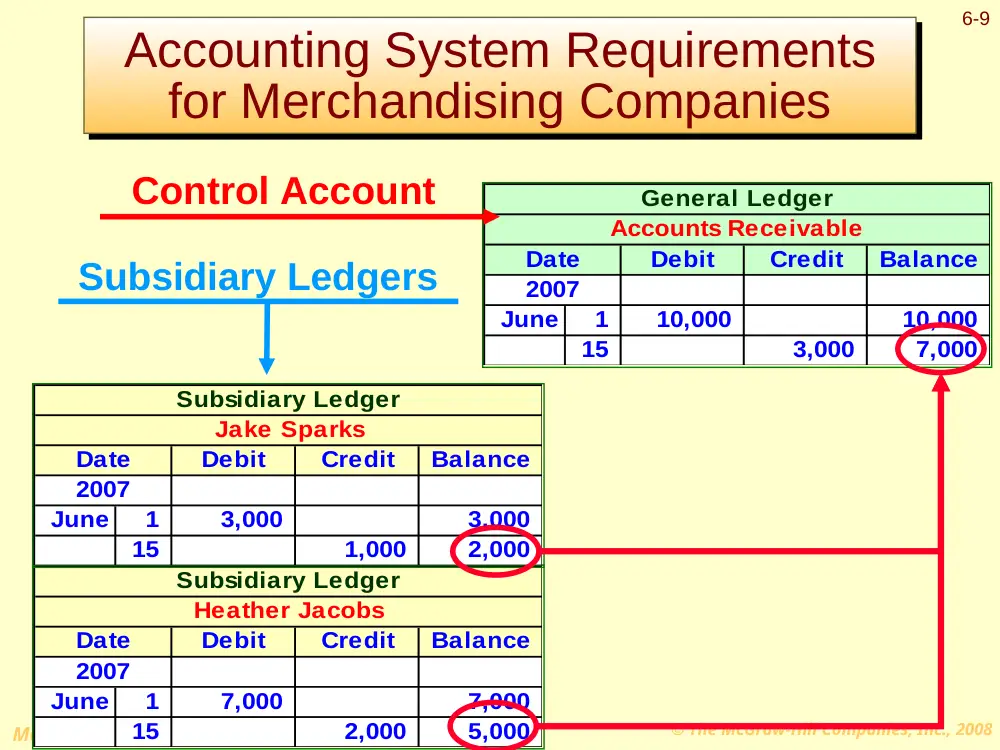
Accounting System Requirements
for Merchandising Companies
Accounting System Requirements
for Merchandising Companies
Subsidiary Ledger
Heather Jacobs
Date
Debit
Credit
Balance
2007
June
1
7,000
7,000
15
2,000
5,000
General Ledger
Accounts Receivable
Date
Debit
Credit
Balance
2007
June
1
10,000
10,000
15
3,000
7,000
Subsidiary Ledger
Jake Sparks
Date
Debit
Credit
Balance
2007
June
1
3,000
3,000
15
1,000
2,000
Control Account
Subsidiary Ledgers
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-10
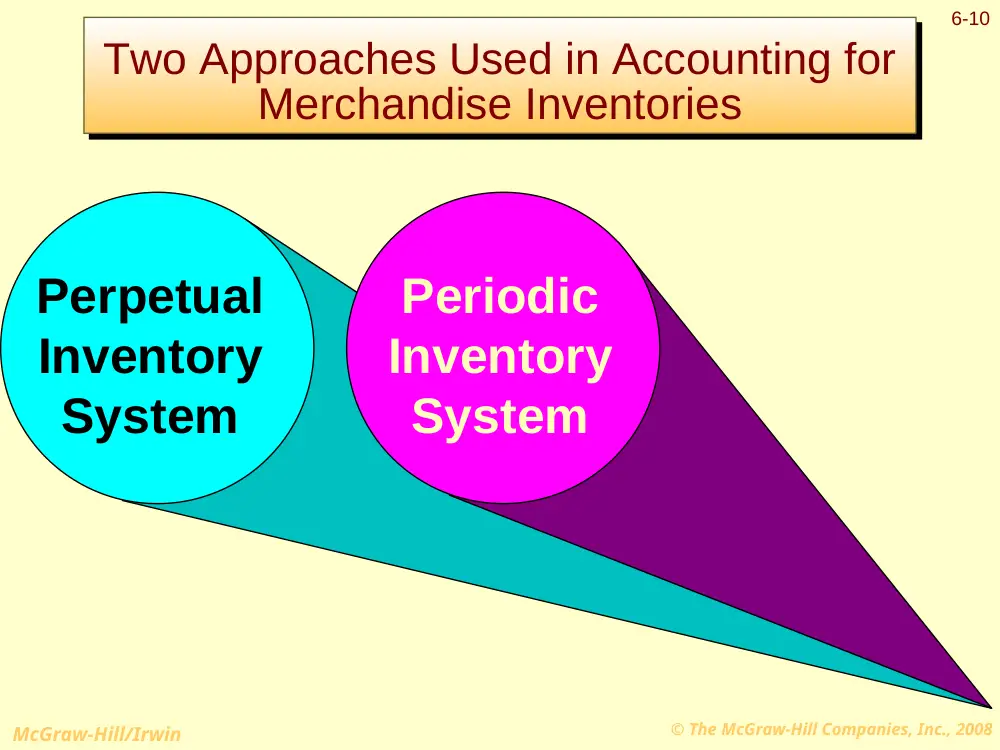
Two Approaches Used in Accounting for
Merchandise Inventories
Two Approaches Used in Accounting for
Merchandise Inventories
Perpetual
Inventory
System
Periodic
Inventory
System
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-11
Learning Objective
Learning Objective
LO3
To account for
purchases and sales of
merchandise in a
perpetual inventory
system.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-12
Perpetual Inventory Systems
Perpetual Inventory Systems
The inventory account is continuously
updated to reflect items on hand.
Let’s look
at some
entries!
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-13
Perpetual Inventory Systems
Perpetual Inventory Systems
On September 5, Worley Co. purchased 100
laser lights for resale for $30 per unit from
Electronic City on account.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-14
Perpetual Inventory Systems
Perpetual Inventory Systems
On September 10, Worley Co. sold 10 laser
lights for $50 per unit on account to ABC
Radios.
10 $30 = $300
10 $30 = $300
Cost
Retail
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-15
Perpetual Inventory Systems
Perpetual Inventory Systems
On September 15, Worley Co. paid Electronic
City $3,000 for the September 5 purchase.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-16
Perpetual Inventory Systems
Perpetual Inventory Systems
On September 22, Worley Co. received $500
from ABC Radios as payment in full for their
purchase on September 10.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-17
Taking a Physical Inventory
Taking a Physical Inventory
In order to ensure
the accuracy of
their perpetual
records, most
businesses take a
complete physical
count of the
merchandise on
hand at least once
a year.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-18
Taking a Physical Inventory
Taking a Physical Inventory
Reasonable amounts of inventory shrinkage are viewed as
a normal cost of doing business. Examples include
breakage, spoilage and theft.
On December 31, Worley Co. counts its inventory.
An inventory shortage of $2,000 is discovered.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-19
Closing Entries in a Perpetual
Inventory System
Closing Entries in a Perpetual
Inventory System
Close Revenue accounts
(including Sales) to Income
Summary.
Close Expense accounts
(including Cost of Goods
Sold) to Income Summary.
Close Income Summary
account to Retained
Earnings.
Close Dividends to Retained
Earnings.
The closing
entries are the
same!
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-20
Learning Objective
Learning Objective
LO4
To explain how a
periodic inventory
system operates.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-21
Periodic Inventory System
Periodic Inventory System
No effort is made to keep up-to-date
records of either inventory or cost of
goods sold.
Let’s look
at some
entries!
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-22
Periodic Inventory System
Periodic Inventory System
On September 5, Worley Co. purchased 100
laser lights for resale for $30 per unit from
Electronic City on account.
Notice that no entry is
made to Inventory.
Notice that no entry is
made to Inventory.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-23
Periodic Inventory System
Periodic Inventory System
On September 10, Worley Co. sold 10 laser
lights for $50 per unit on account to ABC
Radios.
Retail
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-24
Periodic Inventory System
Periodic Inventory System
On September 15, Worley Co. paid Electronic
City $3,000 for the September 5 purchase.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-25
Periodic Inventory System
Periodic Inventory System
On September 22, Worley Co. received $500
from ABC Radios as payment in full for their
purchase on September 10.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-26
Computing Cost of Goods Sold
Computing Cost of Goods Sold
The accounting records of Party
Supply show the following:
Inventory, Jan. 1
$ 14,000
Purchases (during year) 130,000
The accounting records of Party
Supply show the following:
Inventory, Jan. 1
$ 14,000
Purchases (during year) 130,000
At December 31, Party Supply
counted the merchandise on hand
at $12,000.
At December 31, Party Supply
counted the merchandise on hand
at $12,000.
Calculate Party Supply’s cost of goods sold
for the year.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-27
Computing Cost of Goods Sold
Computing Cost of Goods Sold
Inventory (beginning of the year)
14,000
$
Add: Purchases
130,000
Cost of goods available for sale
144,000
Less: Inventory (end of year)
12,000
Cost of goods sold
132,000
$
Cost of Goods Sold can be
calculated as follows:
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-28
Creating a Cost of Goods Sold
Account
Creating a Cost of Goods Sold
Account
Now, Party Supply must
create the Cost of Goods
Sold account.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-29
Creating a Cost of Goods Sold
Account
Creating a Cost of Goods Sold
Account
Now, Party Supply must
record the ending inventory
amount.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-30
Completing the Closing Process
Completing the Closing Process
Close Revenue accounts
(including Sales) to
Income Summary.
Close Expense accounts
(including Cost of
Goods Sold) to Income
Summary.
Close Income Summary
account to Retained
Earnings.
Close Dividends to
Retained Earnings.
The closing
entries are the
same!
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-31
Learning Objective
Learning Objective
LO5
To discuss the factors to
be considered in
selecting an inventory
system.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-32
Selecting an Inventory System
Selecting an Inventory System
Factors Suggesting a
Perpetual Inventory System
Factors Suggesting a
Periodic Inventory System
Large company with
professional management.
Small company, run by
owner.
Management and employees
wanting information about
items in inventory and the
quantities of specific
products that are selling.
Accounting records of
inventories and specific
product sales not needed in
daily operations; such
information developed
primarily for use in annual
income tax returns.
Items in inventory with a high
per-unit cost.
Inventory with many different
kinds of low-cost items.
Low volume of sales
transactions or a
computerized accounting
system.
High volume of sales
transactions and a manual
accounting system.
Merchandise stored at
multiple locations or in
warehouses separate from
sales sites.
All merchandise stored at the
sales site (for example, in the
store).
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-33
Learning Objective
Learning Objective
LO6
To account for
additional merchandise
transactions related to
purchases and sales.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-34
Credit Terms and Cash Discounts
Credit Terms and Cash Discounts
2/10, n/30
Read as: “Two ten, net thirty”
When manufacturers and wholesalers
sell their products on account, the
credit terms are stated in the invoice.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-35
Credit Terms and Cash Discounts
Credit Terms and Cash Discounts
2/10, n/30
Percentage
of Discount
# of Days
Discount Is
Available
Otherwise,
the Full
Amount Is
Due
# of Days
when Full
Amount Is
Due
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-36
Recording Purchases at Net Cost
Recording Purchases at Net Cost
Purchases are
recorded at their
net amounts.
Purchase
Discounts Lost
are recorded
when payment is
made outside
the discount
period.
Net
Method
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-37
Recording Purchases at Net Cost
Recording Purchases at Net Cost
On July 6, Play Clothes purchased $4,000 of
merchandise on credit with terms of
2/10, n/30 from Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-38
Recording Purchases at Net Cost
Recording Purchases at Net Cost
$4,000 98% =
$4,000 98% =
$3 920
On July 6, Play Clothes purchased $4,000 of
merchandise on credit with terms of
2/10, n/30 from Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-39
Recording Purchases at Net Cost
Recording Purchases at Net Cost
On July 15, Play Clothes pays the full amount
due to Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-40
Recording Purchases at Net Cost
Recording Purchases at Net Cost
On July 15, Play Clothes pays the full amount
due to Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-41
Recording Purchases at Net Cost
Recording Purchases at Net Cost
Now, assume that Play Clothes waited until
July 20 to pay the amount due in full to
Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-42
Recording Purchases at Net Cost
Recording Purchases at Net Cost
Nonoperating Expense
Nonoperating Expense
Now, assume that Play Clothes waited until
July 20 to pay the amount due in full to
Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-43
Recording Purchases at Gross
Invoice Price
Recording Purchases at Gross
Invoice Price
Purchases are
recorded at their
gross amounts.
Purchase
discounts taken
are recorded
when payment is
made inside the
discount period.
Gross
Method
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-44
Recording Purchases at Gross
Invoice Price
Recording Purchases at Gross
Invoice Price
On July 6, Play Clothes purchased $4,000 of
merchandise on credit with terms of
2/10, n/30 from Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-45
Recording Purchases at Gross
Invoice Price
Recording Purchases at Gross
Invoice Price
On July 6, Play Clothes purchased $4,000 of
merchandise on credit with terms of
2/10, n/30 from Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-46
Recording Purchases at Gross
Invoice Price
Recording Purchases at Gross
Invoice Price
On July 15, Play Clothes pays the full amount
due to Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-47
Recording Purchases at Gross
Invoice Price
Recording Purchases at Gross
Invoice Price
Reduces Cost of
Goods Sold
Reduces Cost of
Goods Sold
$4,000 98% =
$3,920
$4,000 98% =
$3,920
On July 15, Play Clothes pays the full amount
due to Kid’s Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-48
Recording Purchases at Gross
Invoice Price
Recording Purchases at Gross
Invoice Price
Now, assume that Play Clothes waited until
July 20 to pay the full amount due to Kid’s
Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-49
Recording Purchases at Gross
Invoice Price
Recording Purchases at Gross
Invoice Price
Now, assume that Play Clothes waited until
July 20 to pay the full amount due to Kid’s
Clothes.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-50
Returns of Unsatisfactory
Merchandise
Returns of Unsatisfactory
Merchandise
On August 5, Play Clothes returned $500 of
unsatisfactory merchandise purchased from Kid’s
Clothes on credit terms of 2/10, n/30. The purchase
was originally recorded at net cost.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-51
Returns of Unsatisfactory
Merchandise
Returns of Unsatisfactory
Merchandise
$500 98% = $490
$500 98% = $490
On August 5, Play Clothes returned $500 of
unsatisfactory merchandise purchased from Kid’s
Clothes on credit terms of 2/10, n/30. The purchase
was originally recorded at net cost.
Prepare the journal entry for Play Clothes.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-52
Transportation Costs on Purchases
Transportation Costs on Purchases
Transportation costs related to the
acquisition of assets are part of the
cost of the asset being acquired.
Transportation costs related to the
acquisition of assets are part of the
cost of the asset being acquired.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-53
Now, let’s talk
about sales!
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-54
Transactions Relating to Sales
Transactions Relating to Sales
Computer City
Partial Income Statement
For the Year Ended December 31, 2007
Revenue
Sales
912,000
$
Less: Sales returns and allowances
8,000
$
Sales discounts
4,000
12,000
Net sales
900,000
$
Credit terms and merchandise returns
affect the amount of revenue earned by
the seller.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-55
Sales
Sales
On August 2, Kid’s Clothes sold $2,000 of merchandise
to Play Clothes on credit terms 2/10, n/30. Kid’s
Clothes originally paid $1,000 for the merchandise.
Because Kid’s Clothes uses a perpetual inventory
system, they must make two entries.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-56
Sales
Sales
On August 2, Kid’s Clothes sold $2,000 of merchandise
to Play Clothes on credit terms 2/10, n/30. Kid’s
Clothes originally paid $1,000 for the merchandise.
Because Kid’s Clothes uses a perpetual inventory
system, they must make two entries.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-57
Sales Returns and Allowances
Sales Returns and Allowances
On August 5, Play Clothes returned $500 of
unsatisfactory merchandise to Kid’s Clothes from the
August 2 sale. Kid’s Clothes cost for this
merchandise was $250.
Because Kid’s Clothes uses a perpetual inventory
system, they must make two entries.
Contra-revenue
Contra-revenue
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-58
On August 5, Play Clothes returned $500 of
unsatisfactory merchandise to Kid’s Clothes from the
August 2 sale. Kid’s Clothes cost for this
merchandise was $250.
Because Kid’s Clothes uses a perpetual inventory
system, they must make two entries.
Sales Returns and Allowances
Sales Returns and Allowances
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-59
Sales
Sales
On July 6, Kid’s Clothes sold $4,000 of merchandise to
Play Clothes on credit with terms of 2/10, n/30. The
merchandise originally cost Kid’s Clothes $2,000.
Because Kid’s Clothes uses a perpetual inventory
system, they must make two entries.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
6-60
Sales
Sales
On July 6, Kid’s Clothes sold $4,000 of merchandise to
Play Clothes on credit with terms of 2/10, n/30. The
merchandise originally cost Kid’s Clothes $2,000.
Because Kid’s Clothes uses a perpetual inventory
system, they must make two entries.