
ACCT 210 Lecture, Fall 2008
American University of Beirut · Financial Accounting · 76 pages
Showing the first 10 of 76 pages. Download the PDF to see all of it.
More ACCT 210 files
Show the text of this lab
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-1
INVENTORIES AND
COST OF GOODS SOLD
Chapter
8
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-2
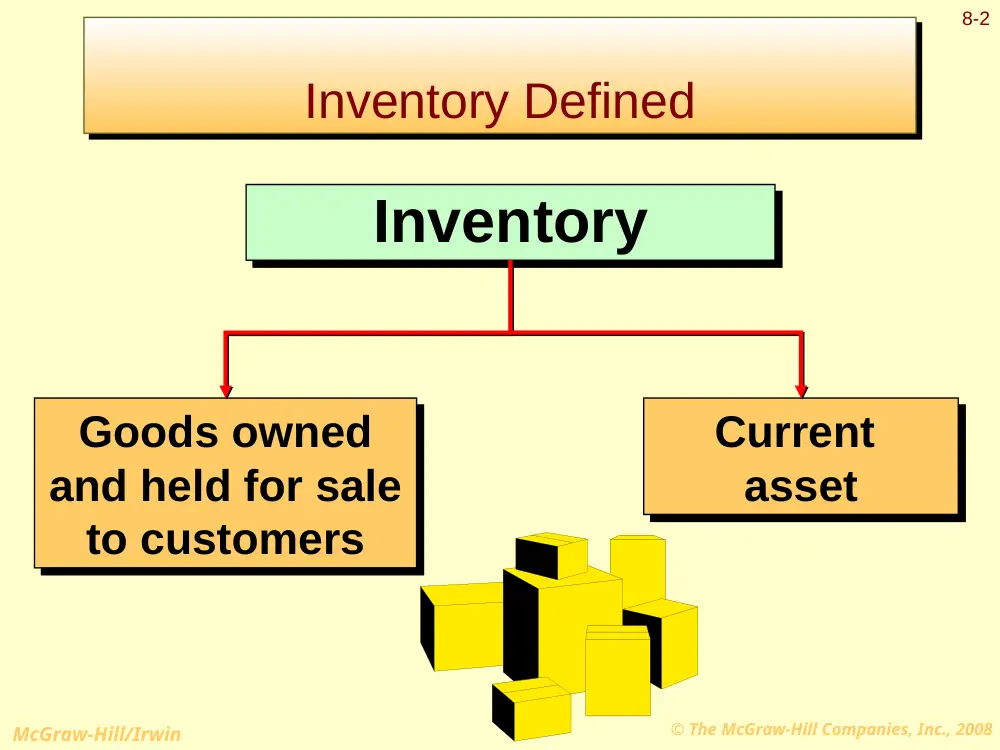
Inventory
Inventory
Goods owned
and held for sale
to customers
Goods owned
and held for sale
to customers
Current
asset
Current
asset
Inventory Defined
Inventory Defined
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-3
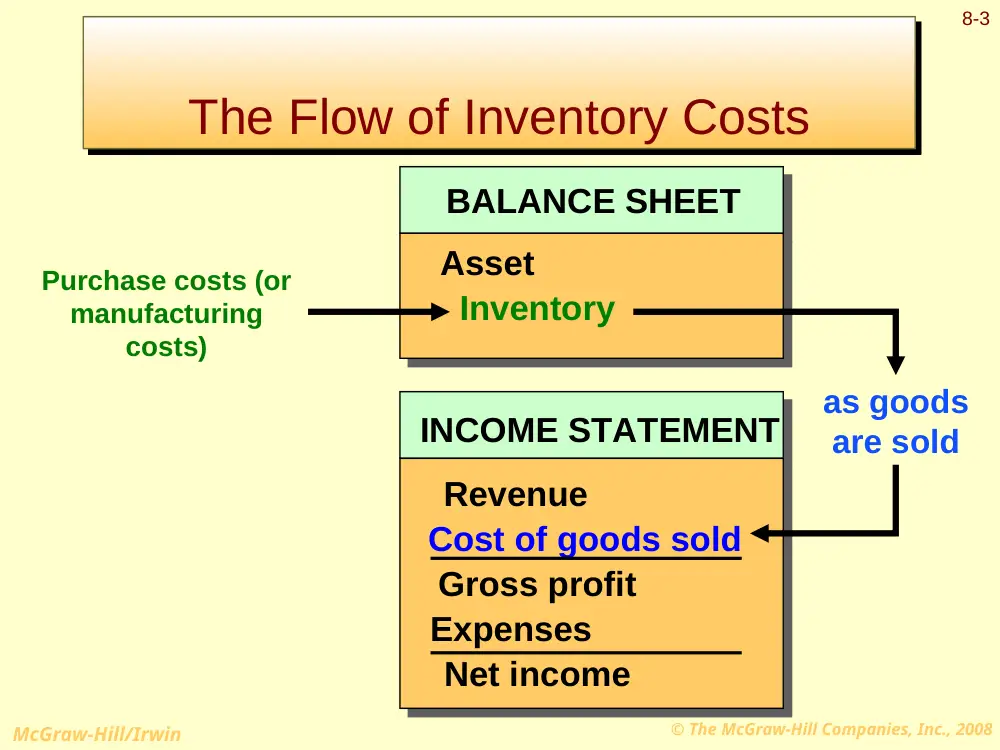
INCOME STATEMENT
Revenue
Cost of goods sold
Gross profit
Expenses
Net income
Purchase costs (or
manufacturing
costs)
as goods
are sold
BALANCE SHEET
Asset
Inventory
The Flow of Inventory Costs
The Flow of Inventory Costs
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-4
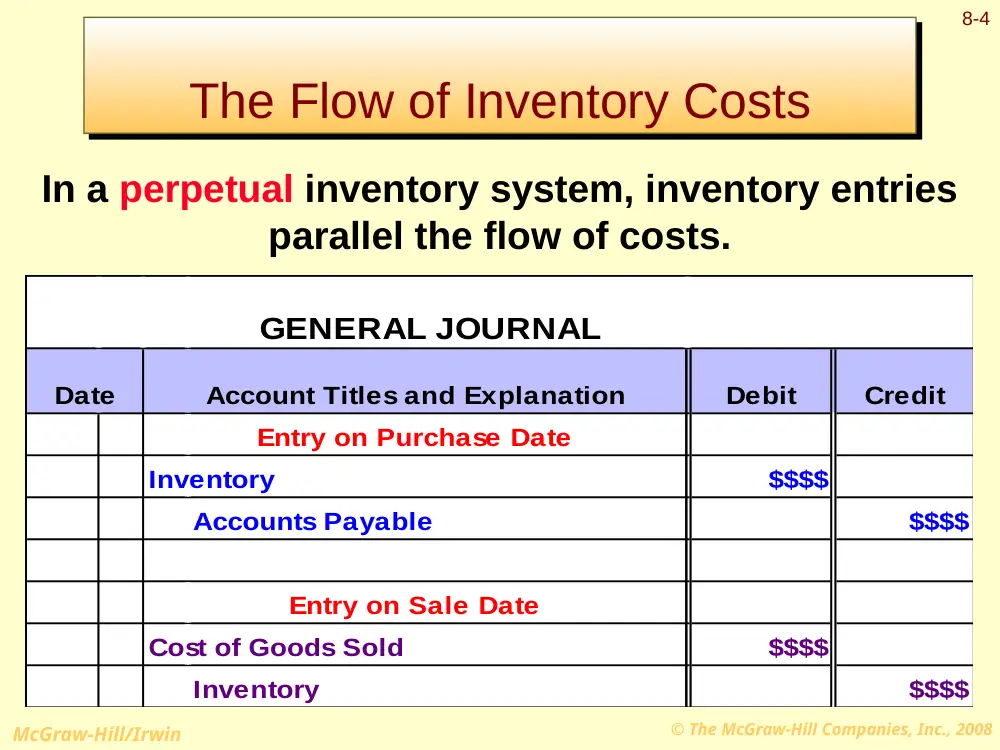
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Entry on Purchase Date
Inventory
$$$$
Accounts Payable
$$$$
Entry on Sale Date
Cost of Goods Sold
$$$$
Inventory
$$$$
In a perpetual inventory system, inventory entries
parallel the flow of costs.
The Flow of Inventory Costs
The Flow of Inventory Costs
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-5
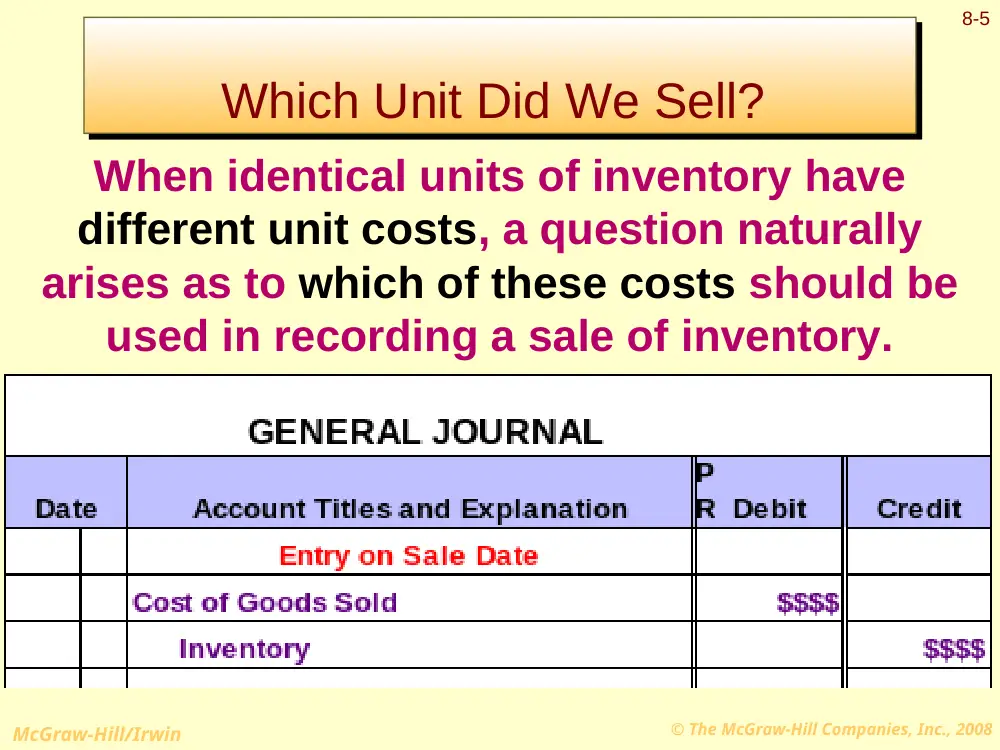
When identical units of inventory have
different unit costs, a question naturally
arises as to which of these costs should be
used in recording a sale of inventory.
Which Unit Did We Sell?
Which Unit Did We Sell?
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-6
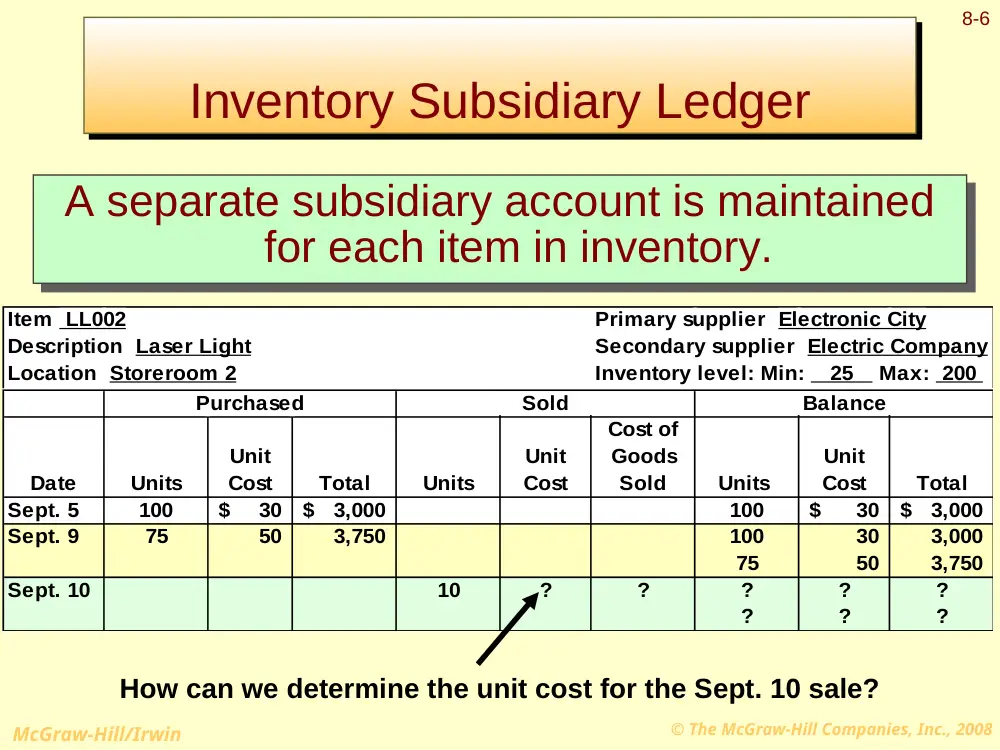
A separate subsidiary account is maintained
for each item in inventory.
A separate subsidiary account is maintained
for each item in inventory.
How can we determine the unit cost for the Sept. 10 sale?
Item LL002
Primary supplier Electronic City
Description Laser Light
Secondary supplier Electric Company
Location Storeroom 2
Inventory level: Min: 25 Max: 200
Purchased
Sold
Balance
Date
Units
Unit
Cost
Total
Units
Unit
Cost
Cost of
Goods
Sold
Units
Unit
Cost
Total
Sept. 5
100
$ 30
$ 3,000
100
$ 30
3,000
$
Sept. 9
75
50
3,750
100
30
3,000
75
50
3,750
Sept. 10
10
?
?
?
?
?
?
?
?
Inventory Subsidiary Ledger
Inventory Subsidiary Ledger
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-7
Learning Objective
Learning Objective
LO1
In a perpetual inventory system,
you are to determine the cost of
goods sold using (a) specific
identification, (b) average cost, (c)
FIFO, and (d) LIFO. You should
be able to discuss the advantages
and shortcomings of each
method.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-8
We use one of these inventory valuation
methods to determine cost of inventory sold.
Inventory Cost Flows
Inventory Cost Flows
Specific
Identification
Average
Cost
LIFO
FIFO
FIFO
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-9
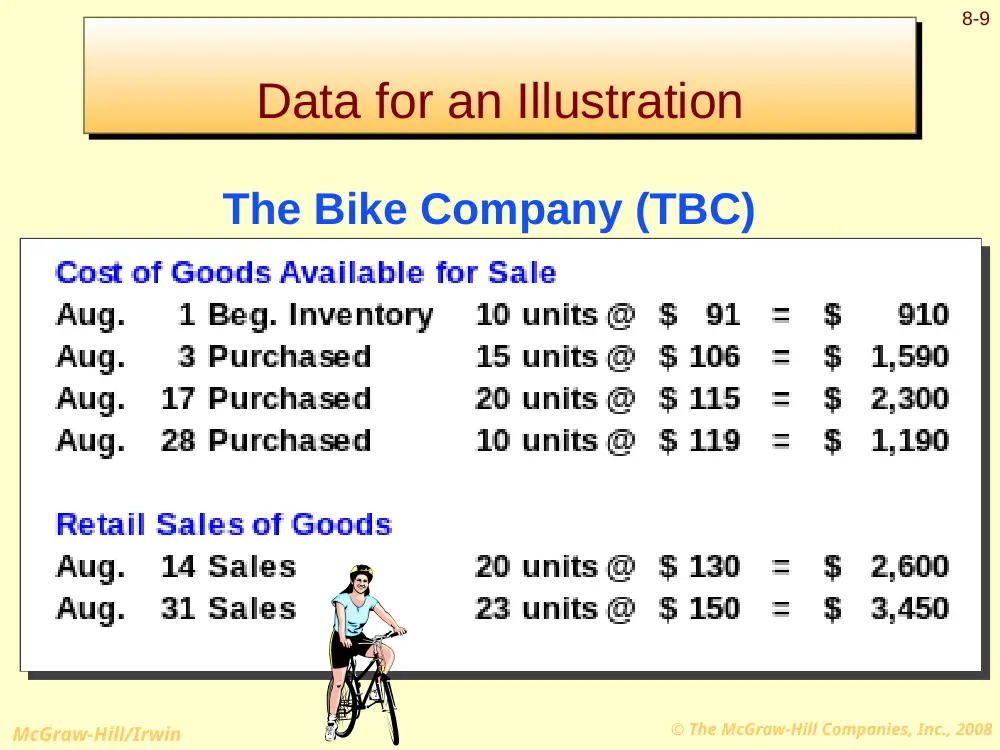
The Bike Company (TBC)
Data for an Illustration
Data for an Illustration
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-10
Specific Identification
Specific Identification
When a unit
is sold, its
specific cost is
added to cost of
goods sold.
When a unit
is sold, its
specific cost is
added to cost of
goods sold.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-11
On August 14, TBC sold 20 bikes for $130 each.
On August 14, TBC sold 20 bikes for $130 each.
Of the bikes sold 9 originally cost $91 and
Of the bikes sold 9 originally cost $91 and
11 cost $106.
11 cost $106.
On August 14, TBC sold 20 bikes for $130 each.
On August 14, TBC sold 20 bikes for $130 each.
Of the bikes sold 9 originally cost $91 and
Of the bikes sold 9 originally cost $91 and
11 cost $106.
11 cost $106.
Specific Identification
Specific Identification
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-12
The Cost of Goods Sold for the August 14 sale is
The Cost of Goods Sold for the August 14 sale is
$1,985, leaving $515 and 5 units in inventory.
$1,985, leaving $515 and 5 units in inventory.
The Cost of Goods Sold for the August 14 sale is
The Cost of Goods Sold for the August 14 sale is
$1,985, leaving $515 and 5 units in inventory.
$1,985, leaving $515 and 5 units in inventory.
Let’s look at the entries for the Aug. 14 sale.
Let’s look at the entries for the Aug. 14 sale.
Specific Identification
Specific Identification
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-13
Retail (20 × $103)
Retail (20 × $103)
Cost
Cost
A similar entry is made after each sale.
A similar entry is made after each sale.
Specific Identification
Specific Identification
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-14
Additional purchases were made on August 17 and 28.
Costs associated with sales on August 31 were as follows: 1 @ $91,
3 @ $106, 15 @ $115, & 4 @ $119.
Additional purchases were made on August 17 and 28.
Costs associated with sales on August 31 were as follows: 1 @ $91,
3 @ $106, 15 @ $115, & 4 @ $119.
Specific Identification
Specific Identification
Cost of Goods
Sold for
August 31 =
$2,610
Cost of Goods
Sold for
August 31 =
$2,610
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-15
Balance Sheet
Inventory = $1,395
Income Statement
COGS = $4,595
1
@
106
$
=
106
$
5
@
115
$
=
575
6
@
119
$
=
714
End. Inv.
1,395
$
1
@
106
$
=
106
$
5
@
115
$
=
575
6
@
119
$
=
714
End. Inv.
1,395
$
Specific Identification
Specific Identification
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-16
Since specific
identification is so
easy, can’t we use it
all the time?
Not really. Specific
Not really. Specific
identification is hard to use
identification is hard to use
when we sell a lot of inventory
when we sell a lot of inventory
that has lots of different costs.
that has lots of different costs.
Specific Identification
Specific Identification
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-17
Cost of Goods
Available for
Sale
Units on hand
on the date of
sale
÷
Average-Cost Method
Average-Cost Method
When a unit is sold,
the average cost of each unit
average cost of each unit
in inventory is assigned to cost
of goods sold.
When a unit is sold,
the average cost of each unit
average cost of each unit
in inventory is assigned to cost
of goods sold.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-18
On August 14, TBC sold 20 bikes for $130 each.
On August 14, TBC sold 20 bikes for $130 each.
On August 14, TBC sold 20 bikes for $130 each.
On August 14, TBC sold 20 bikes for $130 each.
The average cost per unit
must be computed prior
to each sale.
The average cost per unit
must be computed prior
to each sale.
Average-Cost Method
Average-Cost Method
$2,500 25 = $100
$2,500 25 = $100
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-19
The average cost per
The average cost per
unit is $100.
unit is $100.
The average cost per
The average cost per
unit is $100.
unit is $100.
Let’s look at the entries
for the Aug. 14 sale.
Average-Cost Method
Average-Cost Method
$100 = $2,500 25
$100 = $2,500 25
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-20
Retail
Retail
Cost
Cost
A similar entry is made after each sale.
A similar entry is made after each sale.
A similar entry is made after each sale.
A similar entry is made after each sale.
Average-Cost Method
Average-Cost Method
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-21
Additional purchases were made on August 17
Additional purchases were made on August 17
and August 28.
and August 28.
On August 31, an additional 23 units were sold.
On August 31, an additional 23 units were sold.
Additional purchases were made on August 17
Additional purchases were made on August 17
and August 28.
and August 28.
On August 31, an additional 23 units were sold.
On August 31, an additional 23 units were sold.
Average-Cost Method
Average-Cost Method
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-22
$114 = $3,990 35
$114 = $3,990 35
Average-Cost Method
Average-Cost Method
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-23
$114 = $3,990 35
$114 = $3,990 35
The average cost per
unit is $114.
The average cost per
unit is $114.
Average-Cost Method
Average-Cost Method
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-24
Income Statement
COGS = $4,622
Balance Sheet
Inventory = $1,368
$114 × 12 = $1,368
$114 × 12 = $1,368
Average-Cost Method
Average-Cost Method
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-25
Costs of
Goods Sold
Costs of
Goods Sold
Ending
Inventory
Ending
Inventory
Oldest
Costs
Oldest
Costs
Recent
Costs
Recent
Costs
First-In, First-Out Method (FIFO)
First-In, First-Out Method (FIFO)
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-26
On August 14, TBC sold 20 bikes for $130 each.
On August 14, TBC sold 20 bikes for $130 each.
On August 14, TBC sold 20 bikes for $130 each.
On August 14, TBC sold 20 bikes for $130 each.
The Cost of Goods Sold for the August 14 sale is $1,970,
The Cost of Goods Sold for the August 14 sale is $1,970,
leaving $530 and 5 units in inventory.
leaving $530 and 5 units in inventory.
The Cost of Goods Sold for the August 14 sale is $1,970,
The Cost of Goods Sold for the August 14 sale is $1,970,
leaving $530 and 5 units in inventory.
leaving $530 and 5 units in inventory.
First-In, First-Out Method (FIFO)
First-In, First-Out Method (FIFO)
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-27
Retail
Retail
Cost
Cost
A similar entry is made after each sale.
A similar entry is made after each sale.
A similar entry is made after each sale.
A similar entry is made after each sale.
First-In, First-Out Method (FIFO)
First-In, First-Out Method (FIFO)
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-28
Additional purchases were made on Aug. 17 and Aug. 28.
On August 31, an additional 23 units were sold.
Additional purchases were made on Aug. 17 and Aug. 28.
On August 31, an additional 23 units were sold.
First-In, First-Out Method (FIFO)
First-In, First-Out Method (FIFO)
Cost of Goods Sold for August 31 = $2,600
Cost of Goods Sold for August 31 = $2,600
Cost of Goods Sold for August 31 = $2,600
Cost of Goods Sold for August 31 = $2,600
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-29
Balance Sheet
Inventory = $1,420
Income Statement
COGS = $4,570
2
@
$115
=
230
$
10 @
$119
=
1,190
End. Inv.
1,420
$
2
@
$115
=
230
$
10 @
$119
=
1,190
End. Inv.
1,420
$
First-In, First-Out Method (FIFO)
First-In, First-Out Method (FIFO)
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-30
Costs of
Goods Sold
Costs of
Goods Sold
Ending
Inventory
Ending
Inventory
Recent
Costs
Recent
Costs
Oldest
Costs
Oldest
Costs
Last-In, First-Out Method (LIFO)
Last-In, First-Out Method (LIFO)
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-31
On August 14, TBC sold 20 bikes for $130 each.
On August 14, TBC sold 20 bikes for $130 each.
Last-In, First-Out Method (LIFO)
Last-In, First-Out Method (LIFO)
The Cost of Goods Sold for the August 14 sale is
$2,045, leaving $455 and 5 units in inventory.
The Cost of Goods Sold for the August 14 sale is
$2,045, leaving $455 and 5 units in inventory.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-32
Retail
Retail
Cost
Cost
A similar entry is made after each sale.
A similar entry is made after each sale.
A similar entry is made after each sale.
A similar entry is made after each sale.
Last-In, First-Out Method (LIFO)
Last-In, First-Out Method (LIFO)
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-33
Last-In, First-Out Method (LIFO)
Last-In, First-Out Method (LIFO)
Additional purchases were made on Aug. 17 and Aug. 28.
Additional purchases were made on Aug. 17 and Aug. 28.
On Aug. 31, an additional 23 units were sold.
On Aug. 31, an additional 23 units were sold.
Additional purchases were made on Aug. 17 and Aug. 28.
Additional purchases were made on Aug. 17 and Aug. 28.
On Aug. 31, an additional 23 units were sold.
On Aug. 31, an additional 23 units were sold.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-34
Last-In, First-Out Method (LIFO)
Last-In, First-Out Method (LIFO)
Cost of Goods Sold for August 31 = $2,685
Cost of Goods Sold for August 31 = $2,685
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-35
Balance Sheet
Inventory = $1,260
Income Statement
COGS = $4,730
Last-In, First-Out Method (LIFO)
Last-In, First-Out Method (LIFO)
5
@
$ 91
=
455
$
7
@
$ 115
=
805
End. Inv.
1,260
$
5
@
$ 91
=
455
$
7
@
$ 115
=
805
End. Inv.
$1,260
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-36
Inventory Valuation Methods: A Summary
Costs Allocated to:
Valuation
Method
Cost of Goods
Sold
Inventory
Comments
Specific
Actual cost of
Actual cost of units
Parallels physical flow
identification
the units sold
remaining
Logical method when units
are unique
May be misleading for
identical units
Average cost
Number of units
sold times the
Number of units on
hand times the
Assigns all units the same
average unit cost
average unit cost average unit cost
Current costs are averaged
in with older costs
First-in, First-out
(FIFO)
Cost of earliest
purchases on
Cost of most
recently
Cost of goods sold is based
on older costs
hand prior to the
sale
purchased units
Inventory valued at current
costs
May overstate income during
periods of rising prices; may
increase income taxes due
Last-in, First-out
(LIFO)
Cost of most
recently
Cost of earliest
purchases
Cost of goods sold shown at
recent prices
purchased units
(assumed still in
inventory)
Inventory shown at old (and
perhaps out of date) costs
Most conservative method
during periods of rising
prices; often results in lower
income taxes
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-37
Once a company has
adopted a particular
accounting method, it
should follow that
method consistently
rather than switch
methods from one year
to the next.
The Principle of Consistency
The Principle of Consistency
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-38
Learning Objective
Learning Objective
LO2
To explain the need
for taking a physical
inventory.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-39
This inventory arrived
just in time for us to use
it in the manufacturing
process.
Just-In-Time (JIT) Inventory
Systems
Just-In-Time (JIT) Inventory
Systems
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-40
The primary reason for taking a physical inventory
is to adjust the perpetual inventory records for
unrecorded shrinkage losses, such as theft,
spoilage, or breakage.
The primary reason for taking a physical inventory
is to adjust the perpetual inventory records for
unrecorded shrinkage losses, such as theft,
spoilage, or breakage.
Taking a Physical Inventory
Taking a Physical Inventory
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-41
Learning Objective
Learning Objective
LO3
To record shrinkage
losses and other year-
end adjustments to
inventory.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-42
Reduces the value
of the inventory.
Reduces the value
of the inventory.
Obsolescence
Obsolescence
Adjust inventory
value to the lower
of historical cost or
current
replacement cost
(market).
Adjust inventory
value to the lower
of historical cost or
current
replacement cost
(market).
Lower of Cost
or Market
(LCM)
Lower of Cost
or Market
(LCM)
LCM and Other Write-Downs
of Inventory
LCM and Other Write-Downs
of Inventory
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-43
LCM and Other Write-Downs
of Inventory
LCM and Other Write-Downs
of Inventory
Cost
Market
Individual
Items
Inventory
Category
Total
Inventory
Bicycles:
Boy's bicycles
$ 4,200
$ 4,600
4,200
Girls bicycles
3,800
3,100
3,100
Junior bicycle
5,700
5,000
5,000
Total
$ 13,700
$ 12,700
12,700
Bicycle accessories:
Training wheels
$ 485
$ 525
485
Headlamps
312
400
312
Protective helmets
700
600
600
Gloves
245
212
212
Kneepads
195
145
145
Total
$ 1,937
$ 1,882
1,882
Total inventory
$ 15,637
$ 14,582
14,054
$
14,582
$
14,582
$
LCM Applied on the Basis of . . .
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-44
Year
End
A sale should be recorded when title to
the merchandise passes to the buyer.
A sale should be recorded when title to
the merchandise passes to the buyer.
F.O.B.
F.O.B.
shipping
shipping
point
point title
passes to
buyer at the
point of
shipment.
F.O.B.
F.O.B.
shipping
shipping
point
point title
passes to
buyer at the
point of
shipment.
F.O.B.
F.O.B.
destination
destination
point
point title
passes to
buyer at the
point of
destination.
F.O.B.
F.O.B.
destination
destination
point
point title
passes to
buyer at the
point of
destination.
Goods In Transit
Goods In Transit
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-45
Learning Objective
Learning Objective
LO4
In a periodic inventory
system, you are to determine
the cost of goods sold using
(a) specific identification, (b)
average cost, (c) FIFO, and
(d) LIFO.
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-46
In a periodic inventory system, inventory entries are
as follows.
Note that an entry is not
made to inventory.
Note that an entry is not
made to inventory.
Periodic Inventory Systems
Periodic Inventory Systems
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-47
In a periodic inventory system, inventory entries are
as follows.
Periodic Inventory Systems
Periodic Inventory Systems
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-48
The inventory on
hand and the cost
of goods sold for
the year are not
determined until
year-end.
Periodic Inventory Systems
Periodic Inventory Systems
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-49
Specific
identification
LIFO
Average
cost
FIFO
We use one of these inventory valuation
methods in a periodic inventory system.
Periodic Inventory Systems
Periodic Inventory Systems
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-50
Computers, Inc.
Mouse Pad Inventory
Date
Units
$/Unit
Total
Beginning
Inventory
1,000
5.25
$
5,250.00
$
Purchases:
Jan. 3
300
5.30
1,590.00
June 20
150
5.60
840.00
Sept. 15
200
5.80
1,160.00
Nov. 29
150
5.90
885.00
Goods
Available
for Sale
1,800
9,725.00
$
Ending
Inventory
1,200
?
Cost of
Goods Sold
600
?
Information for the Following
Inventory Examples
Information for the Following
Inventory Examples
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-51
By reviewing actual
purchase invoices,
Computers, Inc. determines
that the 1,200 mouse pads
on hand at year-end have
an actual total cost of
$6,400.
Determine the cost of
goods sold for the year.
Specific Identification
Specific Identification
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-52
Computers, Inc.
Mouse Pad Inventory
Date
Units
$/Unit
Total
Beginning
Inventory
1,000
5.25
$
5,250.00
$
Purchases:
Jan. 3
300
5.30
1,590.00
June 20
150
5.60
840.00
Sept. 15
200
5.80
1,160.00
Nov. 29
150
5.90
885.00
Goods
Available
for Sale
1,800
9,725.00
$
Ending
Inventory
1,200
6,400.00
$
Cost of
Goods Sold
600
3,325.00
$
Cost of Goods Sold
$9,725 - $6,400 = $3,325
Cost of Goods Sold
$9,725 - $6,400 = $3,325
Specific Identification
Specific Identification
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-53
Total Cost of
Total Cost of
Goods
Goods
Available for
Available for
Sale
Sale
Total Number
Total Number
of Units
of Units
Available for
Available for
Sale
Sale
÷
The average cost is
calculated at year-
end as follows:
The average cost is
calculated at year-
end as follows:
Average-Cost Method
Average-Cost Method
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-54
Computers, Inc.
Mouse Pad Inventory
Date
Units
$/Unit
Total
Beginning
Inventory
1,000
5.25
$
5,250.00
$
Purchases:
Jan. 3
300
5.30
1,590.00
June 20
150
5.60
840.00
Sept. 15
200
5.80
1,160.00
Nov. 29
150
5.90
885.00
Goods
Available
for Sale
1,800
9,725.00
$
Ending
Inventory
1,200
?
Cost of
Goods Sold
600
?
Avg. Cost $9,725 1,800
= $5.40278
Avg. Cost $9,725 1,800
= $5.40278
Average-Cost Method
Average-Cost Method
Computers, Inc.
Mouse Pad Inventory
Date
Units
$/Unit
Total
Beginning
Inventory
1,000
5.25
$
5,250.00
$
Purchases:
Jan. 3
300
5.30
1,590.00
June 20
150
5.60
840.00
Sept. 15
200
5.80
1,160.00
Nov. 29
150
5.90
885.00
Goods
Available
for Sale
1,800
9,725.00
$
Ending
Inventory
1,200
6,483.00
$
Cost of
Goods Sold
600
3,242.00
$
Ending Inventory
Avg. Cost $5.40278 1,200
= $6,483
Ending Inventory
Avg. Cost $5.40278 1,200
= $6,483
Cost of Goods Sold
Avg. Cost $5.40278 600 =
$3,242
Cost of Goods Sold
Avg. Cost $5.40278 600 =
$3,242
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-55
Costs of
Goods Sold
Costs of
Goods Sold
Ending
Inventory
Ending
Inventory
Oldest
Costs
Oldest
Costs
Recent
Costs
Recent
Costs
First-In, First-Out Method (FIFO)
First-In, First-Out Method (FIFO)
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-56
Remember:
Start with the
11/29 purchase
and then add
other purchases
until you reach
the number of
units in ending
inventory.
Remember:
Start with the
11/29 purchase
and then add
other purchases
until you reach
the number of
units in ending
inventory.
First-In, First-Out Method (FIFO)
First-In, First-Out Method (FIFO)
Computers, Inc.
Mouse Pad Inventory
Date
Units
$/Unit
Total
Beginning
Inventory
1,000
5.25
$
5,250.00
$
Purchases:
Jan. 3
300
5.30
1,590.00
June 20
150
5.60
840.00
Sept. 15
200
5.80
1,160.00
Nov. 29
150
5.90
885.00
Goods
Available
for Sale
1,800
9,725.00
$
Ending
Inventory
1,200
?
Cost of
Goods Sold
600
?
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-57
Date
Beg. Inv.
Purchases
End. Inv.
Cost of
Goods Sold
Nov. 29
150@$5.90
150@$5.90
Units
150
Now, let’s complete the
table.
Now, let’s complete the
table.
First-In, First-Out Method (FIFO)
First-In, First-Out Method (FIFO)
Date
Beg. Inv.
Purchases
End. Inv.
Cost of
Goods Sold
1,000@$5.25
600@$5.25
400@$5.25
Jan. 3
300@$5.30
300@$5.30
June 20
150@$5.60
150@$5.60
Sept. 15
200@$5.80
200@$5.80
Nov. 29
150@$5.90
150@$5.90
Units
1,200
600
Now, we have allocated
the cost to all 1,200 units
in ending inventory.
Date
Beg. Inv.
Purchases
End. Inv.
Cost of
Goods Sold
1,000@$5.25
600@$5.25
400@$5.25
Jan. 3
300@$5.30
300@$5.30
June 20
150@$5.60
150@$5.60
Sept. 15
200@$5.80
200@$5.80
Nov. 29
150@$5.90
150@$5.90
Units
1,200
600
Costs
$6,575
$3,150
Cost of Goods Available for Sale
$9,725
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-58
Completing
the table
summarizes
the
computations
just made.
Completing
the table
summarizes
the
computations
just made.
First-In, First-Out Method (FIFO)
First-In, First-Out Method (FIFO)
Computers, Inc.
Mouse Pad Inventory
Date
Units
$/Unit
Total
Beginning
Inventory
1,000
5.25
$
5,250.00
$
Purchases:
Jan. 3
300
5.30
1,590.00
June 20
150
5.60
840.00
Sept. 15
200
5.80
1,160.00
Nov. 29
150
5.90
885.00
Goods
Available
for Sale
1,800
9,725.00
$
Ending
Inventory
1,200
6,575.00
$
Cost of
Goods Sold
600
3,150.00
$
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-59
Costs of
Goods Sold
Costs of
Goods Sold
Ending
Inventory
Ending
Inventory
Recent
Costs
Recent
Costs
Oldest
Costs
Oldest
Costs
Last-In, First-Out Method (LIFO)
Last-In, First-Out Method (LIFO)
© The McGraw-Hill Companies, Inc., 2008
McGraw-Hill/Irwin
8-60
Remember: Start
with beginning
inventory and
then add other
purchases until
you reach the
number of units
in ending
inventory.
Remember: Start
with beginning
inventory and
then add other
purchases until
you reach the
number of units
in ending
inventory.
Last-In, First-Out Method (LIFO)
Last-In, First-Out Method (LIFO)
Computers, Inc.
Mouse Pad Inventory
Date
Units
$/Unit
Total
Beginning
Inventory
1,000
5.25
$
5,250.00
$
Purchases:
Jan. 3
300
5.30
1,590.00
June 20
150
5.60
840.00
Sept. 15
200
5.80
1,160.00
Nov. 29
150
5.90
885.00
Goods
Available
for Sale
1,800
9,725.00
$
Ending
Inventory
1,200
?
Cost of
Goods Sold
600
?