
ECON 211 Lecture Chapter Six, Spring 2015
American University of Beirut · Elementary Microeconomics Theory · 38 pages · Dr. Ramzi Mabsout




Showing the first 10 of 38 pages. Download the PDF to see all of it.
More ECON 211 files
- Lecture Chapter Three · Spring 2015LabView
- Lecture Chapter Seven · Spring 2015LabView
- Lecture Chapter One · Spring 2015LabView
- Lecture Chapter Two · Spring 2015LabView
- Lecture Chapter Five · Spring 2015LabView
- Lecture Chapter Four · Spring 2015LabView
- Syllabus · Spring 2012LabView
- Syllabus · Spring 2011LabView
Show the text of this lab
1 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
PART
The Market System
Choices Made by
Households and Firms
II
2 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE II.1 Firm and Household Decisions
Households demand in output markets and supply labor and capital in input markets.
To simplify our analysis, we have not included the government and international sectors in
this circular flow diagram. These topics will be discussed in detail later.
3 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE II.2 Understanding the Microeconomy and the Role of Government
To understand how the economy works, it helps to build from the ground up. We start in Chapters 6–8 with an overview of household
and firm decision making in simple perfectly competitive markets.
In Chapters 9–11, we see how firms and households interact in output markets (product markets) and input markets (labor/land and
capital) to determine prices, wages, and profits. Once we have a picture of how a simple perfectly competitive economy works, we begin
to relax assumptions.
Chapter 12 is a pivotal chapter that links perfectly competitive markets with a discussion of market imperfections and the role of
government.
In Chapters 13–19, we cover the three noncompetitive market structures (monopoly, monopolistic competition, and oligopoly),
externalities, public goods, uncertainty and asymmetric information, and income distribution as well as taxation and government finance.
4 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
perfect competition An industry structure in
which there are many firms, each being small
relative to the industry and producing virtually
identical products, and in which no firm is large
enough to have any control over prices.
homogeneous products Undifferentiated outputs;
products that are identical to or indistinguishable
from one another.
perfect knowledge The assumption that
households possess a knowledge of the qualities
and prices of everything available in the market and
that firms have all available information concerning
wage rates, capital costs, and output prices.
Basic assumptions pertaining to Chapters 6-12:
5 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
CHAPTER
OUTLINE6
Household Behavior
and Consumer Choice
Household Choice in Output Markets
The Determinants of Household Demand
The Budget Constraint
The Equation of the Budget Constraint
The Basis of Choice: Utility
Diminishing Marginal Utility
Allocating Income to Maximize Utility
The Utility-Maximizing Rule
Diminishing Marginal Utility and Downward-Sloping Demand
Income and Substitution Effects
The Income Effect
The Substitution Effect
Household Choice in Input Markets
The Labor Supply Decision
The Price of Leisure
Income and Substitution Effects of a Wage Change
Saving and Borrowing: Present versus Future Consumption
A Review: Households in Output and Input Markets
Appendix: Indifference Curves
6 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
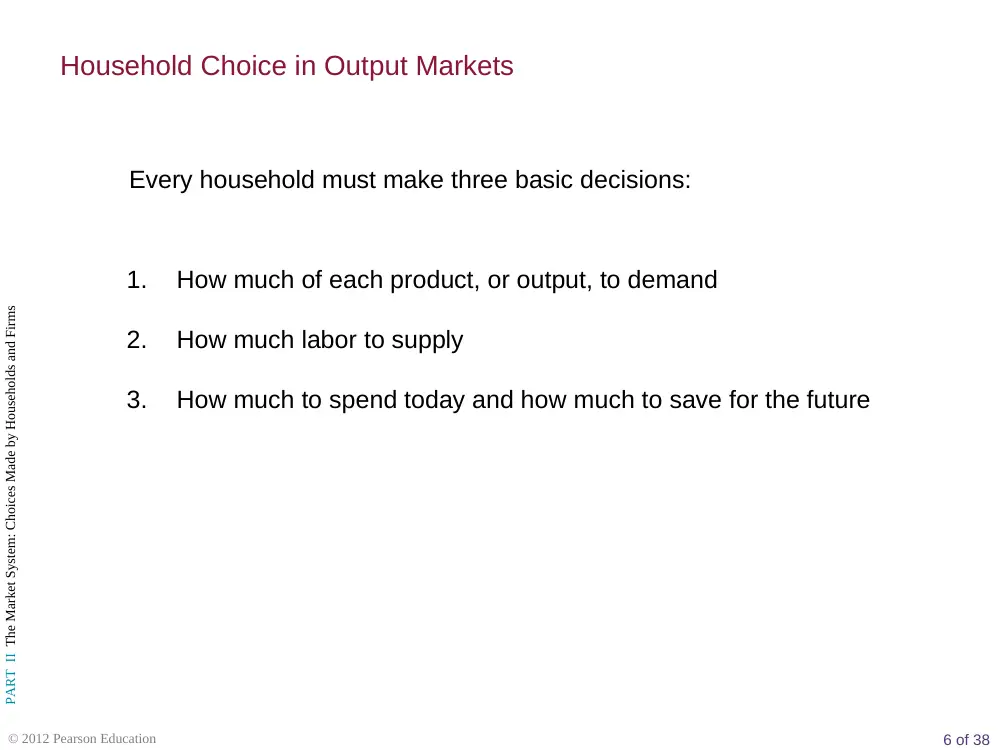
Every household must make three basic decisions:
1.
How much of each product, or output, to demand
2.
How much labor to supply
3.
How much to spend today and how much to save for the future
Household Choice in Output Markets
7 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
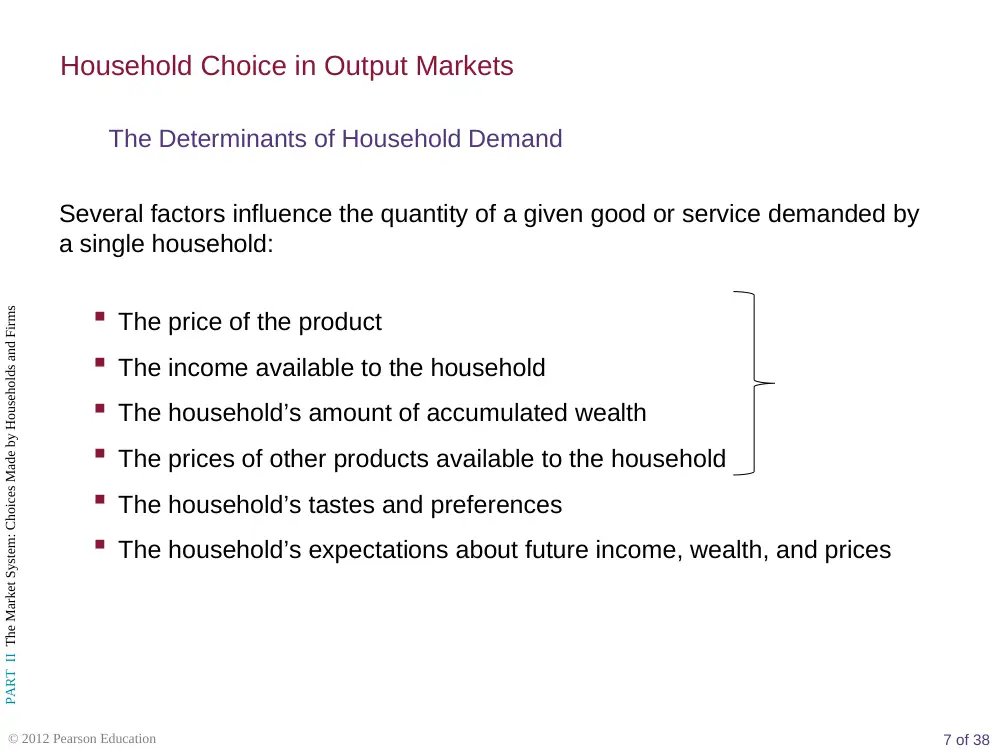
Several factors influence the quantity of a given good or service demanded by
a single household:
The price of the product
The income available to the household
The household’s amount of accumulated wealth
The prices of other products available to the household
The household’s tastes and preferences
The household’s expectations about future income, wealth, and prices
Household Choice in Output Markets
The Determinants of Household Demand
8 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
Household Choice in Output Markets
The Budget Constraint
Preferences, Tastes, Trade-Offs, and Opportunity Cost
Within the constraints imposed by limited incomes and fixed
prices, households are free to choose what they will and will not
buy.
Whenever a household makes a choice, it is weighing the good or
service that it chooses against all the other things that the same
money could buy.
As long as a household faces a limited budget—and all households
ultimately do—the real cost of any good or service is the value of
the other goods and services that could have been purchased with
the same amount of money (opportunity cost).
9 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
budget constraint The limits imposed on
household choices by income, wealth, and
product prices.
choice set or opportunity set The set of
options that is defined and limited by a
budget constraint.
TABLE 6.1 Possible Budget Choices of a Person Earning
$1,000 per Month after Taxes
Option
Monthly
Rent
Food
Other
Expenses
Total
Available?
A
$ 400
$250
$350
$1,000
Yes
B
600
200
200
1,000
Yes
C
700
150
150
1,000
Yes
D
1,000
100
100
1,200
No
Household Choice in Output Markets
The Budget Constraint
10 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6.1 Budget Constraint and
Opportunity Set for Ann and Tom
A budget constraint separates those
combinations of goods and services
that are available, given limited
income, from those that are not.
The available combinations make up
the opportunity set.
real income The set of opportunities
to purchase goods and services
available to a household as determined
by prices and money income. So while
your nominal income might go up, your
real income might do down if price
inflation is larger than the income
increase.
Household Choice in Output Markets
The Budget Constraint
The Budget Constraint More Formally
11 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
In general, the budget constraint can be written
PXX + PYY = I,
where PX = the price of X, X = the quantity of X consumed, PY = the
price of Y, Y = the quantity of Y consumed, and I = household income.
The budget constraint can also be re-written in graphical form
The Equation of the Budget Constraint
Household Choice in Output Markets
Y = I/PY – (PX/PY )X
12 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
Consuming one more X forces the consumer to reduce consumption
of Y by Px/Py
The Equation of the Budget Constraint
Household Choice in Output Markets
Y = I/Py – (Px/Py )X
13 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
Y
X
Slope is -px/py
+1
-px/py
Household Choice in Output Markets
The Equation of the Budget Constraint
14 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6.2 The Effect of a Decrease
in Price on Ann and Tom’s Budget
Constraint
When the price of a good
decreases, the budget constraint
swivels to the right, increasing the
opportunities available and
expanding choice.
The Equation of the Budget Constraint
Household Choice in Output Markets
Budget Constraints Change When Prices Rise or Fall
Y = I/Py – (↓Px/Py )X
15 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
The Equation of the Budget Constraint
Household Choice in Output Markets
Budget Constraints Change When Income Rise
Y = ↑I’/Py – (Px/Py )X
Y
Y2 (=I’/Py)
Y1(=I/Py)
X
X1 (=I/Px) X2 (=I’/Px)
New higher income I’
16 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
The Equation of the Budget Constraint
Household Choice in Output Markets
Budget Constraints Change With Equi-Proportionate Price
Change
Y
Y2 (=I/0.9Py)
Y1(=I/Py)
X
X1 (=I/Px) X2 (=I/0.9Px)
A 10% price decrease for both goods:
(-0.1PX +PX )X + (-0.1PY +PY )Y = I,
(0.9PX )X + (0.9PY )Y = I,
0.9(PX X + PY Y) = I,
PX X + PY Y = I/0.9
17 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
utility The satisfaction a product yields.
marginal utility (MU) The additional satisfaction
gained by the consumption or use of one more
unit of a good or service.
total utility The total amount of satisfaction
obtained from consumption of a good or service.
law of diminishing marginal utility The more
of any one good consumed in a given period, the
less satisfaction (utility) generated by consuming
each additional (marginal) unit of the same good.
The Basis of Choice: Utility
Diminishing Marginal Utility
18 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
TABLE 6.2 Total Utility and Marginal
Utility of Trips to the
Club per Week
Trips
to Club
Total
Utility
Marginal
Utility
1
12
12
2
22
10
3
28
6
4
32
4
5
34
2
6
34
0
FIGURE 6.3 Graphs of Frank’s Total and
Marginal Utility
Marginal utility is the additional utility gained
by consuming one additional unit of a
commodity—in this case, trips to the club.
When marginal utility is zero, total utility
stops rising.
The Basis of Choice: Utility
Diminishing Marginal Utility
19 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6.4 Diminishing Marginal
Utility and Downward-Sloping Demand
At a price of $40, the utility gained
from even the first Thai meal is not
worth the price.
However, a lower price of $25 lures
Ann and Tom into the Thai restaurant
5 times a month. (The utility from the
sixth meal is not worth $25.)
If the price is $15, Ann and Tom will
eat Thai meals 10 times a month—
until the marginal utility of a Thai meal
drops below the utility they could gain
from spending $15 on other goods
(opportunity cost!).
At 25 meals a month, they cannot
tolerate the thought of another Thai
meal even if it is free.
The Basis of Choice: Utility
Diminishing Marginal Utility and Downward-Sloping Demand
20 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
TABLE 6.3 Allocation of Fixed Expenditure per Week Between Two Alternatives
(1) Trips to Club
per Week
(2) Total Utility
(3) Marginal
Utility (MU)
(4) Price (P)
(5) Marginal
Utility per Dollar
(MU/P)
1
12
12
$3.00
4.0
2
22
10
3.00
3.3
3
28
6
3.00
2.0
4
32
4
3.00
1.3
5
34
2
3.00
0.7
6
34
0
3.00
0
(1) Basketball
Games per Week
(2) Total Utility
(3) Marginal
Utility (MU)
(4) Price (P)
(5) Marginal Utility
per Dollar
(MU/P)
1
21
21
$6.00
3.5
2
33
12
6.00
2.0
3
42
9
6.00
1.5
4
48
6
6.00
1.0
5
51
3
6.00
0.5
6
51
0
6.00
0
The Basis of Choice: Utility
Allocating Income to Maximize Utility 2 good and prices
21 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
In general, utility-maximizing consumers spread out their expenditures
until the following condition holds:
utility-maximizing rule Equating the ratio of the marginal
utility of a good to its price for all goods.
What happens if the two ratios are not equal?
The Basis of Choice: Utility
The Utility-Maximizing Rule
where MUX is the marginal utility derived from the last unit of X
consumed, MUY is the marginal utility derived from the last unit of Y
consumed, PX is the price per unit of X, and PY is the price per unit of Y.
for all goods,
- maximizing rule :
utility
Y
Y
X
X
P
MU
P
MU
22 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
We base the following analysis on four assumptions:
1.
We assume that this analysis is restricted to goods that yield positive
marginal utility, or, more simply, that “more is better.”
2.
The marginal rate of substitution is defined as MUX/MUY, or the ratio at
which a household is willing to substitute X for Y. We assume a
diminishing marginal rate of substitution.
3.
We assume that consumers have the ability to choose among the
combinations of goods and services available and the more mixed the
bundle of goods the more satisfied they are (convexity of indifference
curve).
4.
We assume that consumer choices are consistent with a simple
assumption of rationality (no crossing indifference curves)
CHAPTER 6 APPENDIX
Indifference Curves
Assumptions
23 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6A.1 An Indifference Curve
An indifference curve is a set of
points, each representing a
combination of some amount of good
X and some amount of good Y, that all
yield the same amount of total utility.
The consumer depicted here is
indifferent between bundles A and B,
B and C, and A and C.
Because “more is better,” our
consumer is unequivocally worse off
at A' than at A.
CHAPTER 6 APPENDIX
Indifference Curves
Deriving Indifference Curves
24 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6A.1 An Indifference Curve
CHAPTER 6 APPENDIX
Indifference Curves
Convexity
All the bundles on the green line are
different weighted averages of
bundles A and B. Because of the
convexity assumption, which states
that consumers like to mix goods,
these bundles will be on a higher
indifference curve
25 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6A.2 A Preference Map: A
Family of Indifference Curves
Each consumer has a unique family of
indifference curves called a
preference map.
Higher indifference curves represent
higher levels of total utility.
)
(
Y
MU
X
MU
Y
X
Y
X
MU
MU
X
Y
The slope of an indifference curve is the
ratio of the marginal utility of X to the
marginal utility of Y, and it is negative.
CHAPTER 6 APPENDIX
Indifference Curves
Properties of Indifference Curves
When we divide both sides by MUY
and by X, we obtain
26 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6A.3 Consumer Utility-Maximizing
Equilibrium
Consumers will choose the combination of X
and Y that maximizes total utility.
Graphically, the consumer will move along the
budget constraint until the highest possible
indifference curve is reached.
At that point, the budget constraint and the
indifference curve are tangent.
This point of tangency occurs at X* and Y*
(point B).
Y
X
Y
X
P
P
MU
MU
Y
Y
X
X
P
MU
P
MU
CHAPTER 6 APPENDIX
Indifference Curves
Consumer Choice
slope of indifference curve = slope of budget
constraint
By multiplying both sides of this equation
by MUY and dividing both sides by PX, we
can rewrite this utility-maximizing rule as
27 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6A.4 Deriving a Demand Curve from Indifference Curves and Budget Constraint
Indifference curves are labeled i1, i2, and i3; budget constraints are shown by the three diagonal lines from I/PY to I/PX
1, I/PX
2 and I/PX
3.
Lowering the price of X from PX
1
to PX
2 and then to PX
3 swivels the budget constraint to the right.
At each price, there is a different utility-maximizing combination of X and Y.
Utility is maximized at point A on i1, point B on i2, and point C on i3.
Plotting the three prices against the quantities of X chosen results in a standard downward-sloping demand curve.
CHAPTER 6 APPENDIX
Indifference Curves
Deriving a Demand Curve from Indifference Curves and Budget Constraints
I
28 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
Price changes affect households in two ways. First, if we assume
that households confine their choices to products that improve their
well-being, then a decline in the price of any product, ceteris
paribus, will make the household unequivocally better off.
In other words, if a household continues to buy the same amount of
every good and service after the price decrease, it will have income
left over. That extra income may be spent on the product whose
price has declined, hereafter called good X, or on other products.
The change in consumption of X due to this improvement in well-
being is called the income effect of a price change.
Income and Substitution Effects
The Income Effect
29 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
When the price of a product falls, that product also becomes relatively
cheaper. That is, it becomes more attractive relative to potential
substitutes. A fall in the price of product X might cause a household
to shift its purchasing pattern away from substitutes toward X. This
shift is called the substitution effect of a price change.
Everything works in the opposite direction when a price rises,
ceteris paribus. When the price of a product rises, that item
becomes more expensive relative to potential substitutes and the
household is likely to substitute other goods for it.
Income and Substitution Effects
The Substitution Effect
30 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6.5 Income and Substitution Effects of a Price Change
For normal goods, the income and substitution effects work in the same direction.
Higher prices lead to a lower quantity demanded, and lower prices lead to a higher quantity demanded.
Income and Substitution Effects
31 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
As in output markets, households face constrained choices in
input markets. They must decide
1. Availability of jobs
2. Market wage rates
3. Skills they possess
In essence, household members must decide how much labor to
supply. The choices they make are affected by:
Household Choice in Input Markets
The Labor Supply Decision
1. Whether to work
2. How much to work
3. What kind of a job to work at
32 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
Trading one good for another involves
buying less of one and more of another,
so households simply reallocate money
from one good to the other.
“Buying” more leisure, however, means
reallocating time between work and
nonwork activities.
For each hour of leisure that you decide to
consume, you give up one hour’s wages.
Thus, the wage rate is the price of leisure.
Household Choice in Input Markets
The Price of Leisure is the Wage
33 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
labor supply curve A curve that shows the
quantity of labor supplied at different wage
rates. Its shape depends on how households
react to changes in the wage rate.
Income effect: as the household earns
higher income it also buys more leisure (so
less work).
Substitution effect: opportunity cost of
leisure increases (higher forgone wage) so
household works more.
Household Choice in Input Markets
Income and Substitution Effects of a Wage Change
34 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
FIGURE 6.7 Two Labor Supply Curves
When the substitution effect outweighs the income
effect, the labor supply curve slopes upward (a).
When the income effect outweighs the substitution
effect, the result is a “backward-bending” labor supply
curve: The labor supply curve slopes downward (b).
Household Choice in Input Markets
Income and Substitution Effects
of a Wage Change
35 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
Just as changes in wage rates affect household
behavior in the labor market, changes in interest rates
affect household behavior in capital markets.
↑ i = ↑ cost of current consumption = ↑ savings
(substitution effect)
↑ i = less savings needed to reach a specific target
amount = ↓ savings (income effect)
Most empirical evidence indicates that saving tends to
increase as the interest rate rises. In other words, the
substitution effect is larger than the income effect.
financial capital market The complex set
of institutions in which suppliers of capital
(households that save) and the demand for
capital (firms wanting to invest) interact.
Household Choice in Input Markets
Saving and Borrowing: Present versus Future Consumption
36 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
We now have a rough sketch of the factors
that determine output demand and input
supply. (You can review these in Figure II.1.)
In the next three chapters, we turn to firm
behavior and explore in detail the factors that
affect output supply and input demand.
A Review: Households in Output and Input Markets
37 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
budget constraint
choice set or opportunity set
diamond/water paradox
financial capital market
homogeneous products
labor supply curve
law of diminishing marginal utility
marginal utility (MU)
perfect competition
perfect knowledge
real income
total utility
utility
utility-maximizing rule
R E V I E W T E R M S A N D C O N C E P T
S
38 of 38
PART II The Market System: Choices Made by Households and Firms
© 2012 Pearson Education
Indifference curve
Marginal rate of substitution
Preference map
A P P E N D I X R E V I E W T E R M S A N D C O N C E P T S