
ECON 211 Lecture Chapter Three, Spring 2015
American University of Beirut · Elementary Microeconomics Theory · 47 pages · Dr. Ramzi Mabsout




Showing the first 10 of 47 pages. Download the PDF to see all of it.
More ECON 211 files
- Lecture Chapter Six · Spring 2015LabView
- Lecture Chapter Seven · Spring 2015LabView
- Lecture Chapter One · Spring 2015LabView
- Lecture Chapter Two · Spring 2015LabView
- Lecture Chapter Five · Spring 2015LabView
- Lecture Chapter Four · Spring 2015LabView
- Syllabus · Spring 2012LabView
- Syllabus · Spring 2011LabView
Show the text of this lab
1 of 50
PART I Introduction to Economics
© 2012 Pearson Education
CHAPTER
OUTLINE3
Demand, Supply, and
Market Equilibrium
Firms and Households: The Basic Decision-Making
Units
Input Markets and Output Markets: The Circular
Flow
Demand in Product/Output Markets
Changes in Quantity Demanded versus Changes in Demand
Price and Quantity Demanded: The Law of Demand
Other Determinants of Household Demand
Shift of Demand versus Movement Along the Demand Curve
From Household Demand to Market Demand
Supply in Product/Output Markets
Price and Quantity Supplied: The Law of Supply
Other Determinants of Supply
Shift of Supply versus Movement Along the Supply Curve
From Individual Supply to Market Supply
Market Equilibrium
Excess Demand
Excess Supply
Changes in Equilibrium
Demand and Supply in Product Markets: A Review
Looking Ahead: Markets and the Allocation of
Resources
2 of 50
PART I Introduction to Economics
© 2012 Pearson Education
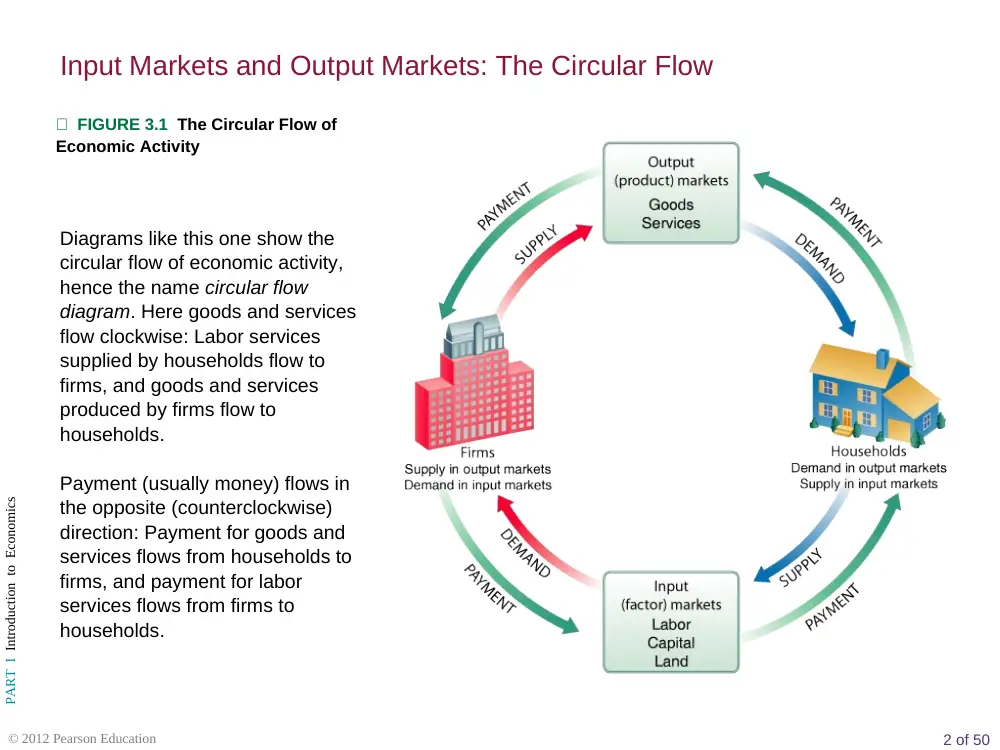
FIGURE 3.1 The Circular Flow of
Economic Activity
Diagrams like this one show the
circular flow of economic activity,
hence the name circular flow
diagram. Here goods and services
flow clockwise: Labor services
supplied by households flow to
firms, and goods and services
produced by firms flow to
households.
Payment (usually money) flows in
the opposite (counterclockwise)
direction: Payment for goods and
services flows from households to
firms, and payment for labor
services flows from firms to
households.
Input Markets and Output Markets: The Circular Flow
3 of 50
PART I Introduction to Economics
© 2012 Pearson Education
firm An organization that transforms resources
(inputs) into products (outputs). Firms are the primary
producing units in a market economy.
entrepreneur A person who organizes, manages, and
assumes the risks of a firm, taking a new idea or a new
product and turning it into a successful business.
households The consuming units in an economy.
Firms and Households: The Basic Decision-Making Units
4 of 50
PART I Introduction to Economics
© 2012 Pearson Education
product or output markets The markets in which
goods and services are exchanged for final
consumption.
input or factor markets The markets in
which the resources used to produce goods
and services are exchanged.
Input Markets and Output Markets: The Circular Flow
5 of 50
PART I Introduction to Economics
© 2012 Pearson Education
labor market The input/factor market in
which households supply work for wages to
firms that demand labor.
capital market The input/factor market in
which households supply their savings, for
interest or for claims to future profits, to firms
that demand funds to buy capital goods.
Input Markets and Output Markets: The Circular Flow
factors of production The inputs into the
production process. Land, labor, and capital
are the three key factors of production.
land market The input/factor market in
which households supply land or other real
property in exchange for rent.
6 of 50
PART I Introduction to Economics
© 2012 Pearson Education
Input and output markets are connected through the behavior of
both firms and households.
Firms determine the quantities and character of outputs produced
and the types and quantities of inputs demanded.
Households determine the types and quantities of products
demanded and the quantities and types of inputs supplied.
Input Markets and Output Markets: The Circular Flow
7 of 50
PART I Introduction to Economics
© 2012 Pearson Education
A household’s decision about what quantity of a particular
output, or product, to demand depends on a number of
factors, including:
The price of the product in question.
The income available to the household.
The household’s amount of accumulated wealth.
The prices of other products available to the
household.
The household’s tastes and preferences.
The household’s expectations about future income,
wealth, and prices.
Demand in Product/Output Markets
8 of 50
PART I Introduction to Economics
© 2012 Pearson Education
The most important relationship in individual markets
is that between market price and quantity demanded.
Changes in the price of a product affect the quantity demanded
per period. Changes in any other factor, such as income or
preferences, affect demand.
Thus, an increase in the price of Coca-Cola is likely to cause a
decrease in the quantity of Coca-Cola demanded.
However, an increase in income is likely to cause an increase in the
demand for most goods.
Demand in Product/Output Markets
Changes in Quantity Demanded versus Changes in Demand
9 of 50
PART I Introduction to Economics
© 2012 Pearson Education
quantity demanded The amount (number
of units) of a product that a household
would buy in a given period if it could buy
all it wanted at the current market price.
Demand in Product/Output Markets
10 of 50
PART I Introduction to Economics
© 2012 Pearson Education
demand schedule A table showing how
much of a given product a household
would be willing to buy at different prices.
demand curve A graph illustrating how
much of a given product a household
would be willing to buy at different prices.
Demand in Product/Output Markets
Price and Quantity Demanded: The Law of Demand
11 of 50
PART I Introduction to Economics
© 2012 Pearson Education
TABLE 3.1 Alex’s Demand Schedule
for Gasoline
Price
(per Gallon)
Quantity Demanded
(Gallons per Week)
$ 8.00
0
7.00
2
6.00
3
5.00
5
4.00
7
3.00
10
2.00
14
1.00
20
0.00
26
FIGURE 3.2 Alex’s Demand Curve
The relationship between price (P) and quantity
demanded (q) presented graphically is called a
demand curve.
Demand curves have a negative slope, indicating that
lower prices cause quantity demanded to increase.
Note that Alex’s demand curve is blue; demand in
product markets is determined by household choice.
Demand in Product/Output Markets
Price and Quantity Demanded: The Law of Demand
12 of 50
PART I Introduction to Economics
© 2012 Pearson Education
law of demand The negative relationship
between price and quantity demanded: As
price rises, quantity demanded decreases;
as price falls, quantity demanded increases.
It is reasonable to expect quantity demanded to fall when price rises,
ceteris paribus, and to expect quantity demanded to rise when price
falls, ceteris paribus. Demand curves have a negative slope.
Demand in Product/Output Markets
Price and Quantity Demanded: The Law of Demand
Demand Curves Slope Downward
13 of 50
PART I Introduction to Economics
© 2012 Pearson Education
1. They have a negative slope.
2. They intersect the quantity (X-) axis.
3. They intersect the price (Y-) axis.
Demand in Product/Output Markets
Price and Quantity Demanded: The Law of Demand
Other Properties of Demand Curves
The actual shape of an individual household demand curve—whether
it is steep or flat, whether it is bowed in or bowed out—depends on
the unique tastes and preferences of the household and other factors.
14 of 50
PART I Introduction to Economics
© 2012 Pearson Education
shift of a demand curve The change that takes place
in a demand curve corresponding to a new relationship
between quantity demanded of a good and price of that
good. The shift is brought about by a change in the
original conditions.
movement along a demand curve The change in
quantity demanded brought about by a change in price.
Change in price of a good or service leads to
Change in quantity demanded (movement along a demand curve).
Change in income, preferences, or prices of other goods or services leads to
Change in demand (shift of a demand curve).
Shift of Demand versus Movement Along a Demand Curve
Demand in Product/Output Markets
15 of 50
PART I Introduction to Economics
© 2012 Pearson Education
TABLE 3.2 Shift of Alex’s Demand Schedule Due to
Increase in Income
Schedule D0
Schedule D1
Price
(per Gallon)
Quantity Demanded
(Gallons per Week at an
Income of $550 per Week)
Quantity Demanded
(Gallons per Week at an
Income of $730 per
Week)
$ 8.00
0
3
7.00
2
5
6.00
3
7
5.00
5
10
4.00
7
12
3.00
10
15
2.00
14
19
1.00
20
24
0.00
26
30
FIGURE 3.3 Shift of a Demand Curve following a Rise in
Income
When the price of a good changes, we move
along the demand curve for that good.
When any other factor that influences demand
changes (income, tastes, and so on), the relationship
between price and quantity is different; there is a shift of the
demand curve, in this case from D0 to D1.
Gasoline is a normal good.
Shift of Demand versus Movement Along a Demand Curve
Demand in Product/Output Markets
16 of 50
PART I Introduction to Economics
© 2012 Pearson Education
income The sum of all a household’s wages, salaries,
profits, interest payments, rents, and other forms of
earnings in a given period of time. It is a flow measure.
wealth or net worth The total value of what a household
owns minus what it owes. It is a stock measure.
Income, wealth, and prices of other goods available are
the three factors that determine the combinations of
goods and services that a household is able to buy, its
purchasing power.
Other Determinants of Household Demand
Demand in Product/Output Markets
Income and Wealth
17 of 50
PART I Introduction to Economics
© 2012 Pearson Education
normal goods Goods for which demand
goes up when income is higher and for which
demand goes down when income is lower.
inferior goods Goods for which demand
tends to fall when income rises.
Other Determinants of Household Demand
Demand in Product/Output Markets
Income and Wealth
18 of 50
PART I Introduction to Economics
© 2012 Pearson Education
FIGURE 3.4 Shifts versus Movement Along a Demand Curve
Shift of Demand versus Movement Along a Demand Curve
Demand in Product/Output Markets
a. When income increases, the demand for inferior goods shifts to the
left
and the demand for normal goods shifts to the right.
19 of 50
PART I Introduction to Economics
© 2012 Pearson Education
substitutes Goods that can serve as
replacements for one another; when the price of
one increases, demand for the other increases.
perfect substitutes products with identical
characteristics.
complements, complementary goods Goods
that “go together”; a decrease in the price of one
results in an increase in demand for the other
and vice versa.
Other Determinants of Household Demand
Demand in Product/Output Markets
Prices of Other Goods and Services
20 of 50
PART I Introduction to Economics
© 2012 Pearson Education
FIGURE 3.4 Shifts versus Movement Along a Demand Curve (continued)
b. If the price of hamburger rises, the quantity of hamburger demanded declines— this is a
movement along the demand curve.
The same price rise for hamburger would shift the demand for chicken (a substitute for
hamburger) to the right and the demand for ketchup (a complement to hamburger) to the
left.
Shift of Demand versus Movement Along a Demand Curve
Demand in Product/Output Markets
21 of 50
PART I Introduction to Economics
© 2012 Pearson Education
Changes in preferences can and do manifest
themselves in market behavior.
Within the constraints of prices and incomes,
preference shapes the demand curve, but it is difficult
to generalize about tastes and preferences. First, they
are volatile. Second, tastes are idiosyncratic.
Other Determinants of Household Demand
Demand in Product/Output Markets
Tastes and Preferences
22 of 50
PART I Introduction to Economics
© 2012 Pearson Education
What you decide to buy today certainly depends on
today’s prices and your current income and wealth.
But you may also have expectations about future
changes in prices and income/wealth too which may
affect your decisions.
There are many examples of the ways expectations
affect demand.
Increasingly, economic theory has come to recognize
the importance of expectations.
It is important to understand that demand depends on
more than just current incomes, prices, and tastes.
Other Determinants of Household Demand
Demand in Product/Output Markets
Expectations
23 of 50
PART I Introduction to Economics
© 2012 Pearson Education
market demand The sum of all the quantities of a good
or service demanded per period by all the households
buying in the market for that good or service.
From Household Demand to Market Demand
Demand in Product/Output Markets
24 of 50
PART I Introduction to Economics
© 2012 Pearson Education
FIGURE 3.5 Deriving Market Demand
from Individual Demand Curves
Total demand in the marketplace is simply the sum
of the demands of all the households shopping in a
particular market. It is the sum of all the individual
demand curves—that is, the sum of all the
individual quantities demanded at each price.
From Household Demand to Market Demand
Demand in Product/Output Markets
25 of 50
PART I Introduction to Economics
© 2012 Pearson Education
profit The difference between revenues and costs.
Firms build factories, hire workers, and buy raw materials
because they believe they can sell the products they
make for more than it costs to produce them.
Supply in Product/Output Markets
26 of 50
PART I Introduction to Economics
© 2012 Pearson Education
quantity supplied The amount of a particular
product that a firm would be willing and able
to offer for sale at a particular price during a
given time period.
supply schedule A table showing how much
of a product firms will sell at alternative prices.
Supply in Product/Output Markets
Price and Quantity Supplied: The Law of Supply
27 of 50
PART I Introduction to Economics
© 2012 Pearson Education
Supply in Product/Output Markets
Price and Quantity Supplied: The Law of Supply
law of supply The positive relationship
between price and quantity of a good
supplied: An increase in market price will
lead to an increase in quantity supplied, and
a decrease in market price will lead to a
decrease in quantity supplied.
supply curve A graph illustrating how much
of a product a firm will sell at different prices.
28 of 50
PART I Introduction to Economics
© 2012 Pearson Education
TABLE 3.3 Clarence Brown’s Supply
Schedule for Soybeans
Price (per Bushel)
Quantity Supplied
(Bushels per Year)
$1.50
0
1.75
10,000
2.25
20,000
3.00
30,000
4.00
45,000
5.00
45,000
FIGURE 3.6 Clarence Brown’s Individual Supply
Curve
A producer will supply more when the price of
output is higher. The slope of a supply curve is
positive.
Note that the supply curve is red: Supply is
determined by choices made by firms.
Supply in Product/Output Markets
Price and Quantity Supplied: The Law of Supply
29 of 50
PART I Introduction to Economics
© 2012 Pearson Education
For a firm to make a profit, its revenue must exceed its costs.
Cost of production depends on a number of factors, including the
available technologies and the prices and quantities of the inputs
needed by the firm (labor, land, capital, energy, and so on).
Supply in Product/Output Markets
Other Determinants of Supply
The Cost of Production
30 of 50
PART I Introduction to Economics
© 2012 Pearson Education
Assuming that its objective is to maximize profits, a firm’s decision
about what quantity of output, or product, to supply depends on:
1. The price of the good or service.
2. The cost of producing the product, which in turn depends on:
■ The price of required inputs (labor, capital, and land).
■ The technologies that can be used to produce the product.
3. The prices of related products.
Supply in Product/Output Markets
Other Determinants of Supply
31 of 50
PART I Introduction to Economics
© 2012 Pearson Education
movement along a supply curve The change in
quantity supplied brought about by a change in price.
shift of a supply curve The change that takes
place in a supply curve corresponding to a new
relationship between quantity supplied of a good and
the price of that good. The shift is brought about by a
change in the original conditions.
Supply in Product/Output Markets
Shift of Supply versus Movement Along a Supply Curve
32 of 50
PART I Introduction to Economics
© 2012 Pearson Education
TABLE 3.4 Shift of Supply Schedule for Soybeans
following Development of a New
Disease-Resistant Seed Strain
Schedule S0
Schedule S1
Price
(per Bushel)
Quantity Supplied
(Bushels per Year
Using Old Seed)
Quantity Supplied
(Bushels per Year
Using New Seed)
$1.50
0
5,000
1.75
10,000
23,000
2.25
20,000
33,000
3.00
30,000
40,000
4.00
45,000
54,000
5.00
45,000
54,000
FIGURE 3.7 Shift of the Supply Curve for Soybeans
following Development of a New Seed Strain
When the price of a product changes, we move
along the supply curve for that product; the quantity
supplied rises or falls.
When any other factor affecting supply changes, the
supply curve shifts.
Supply in Product/Output Markets
Shift of Supply versus Movement Along a Supply Curve
33 of 50
PART I Introduction to Economics
© 2012 Pearson Education
As with demand, it is very important to distinguish between
movements along supply curves (changes in quantity
supplied) and shifts in supply curves (changes in supply):
Change in price of a good or service leads to
Change in quantity supplied (movement along a supply curve).
Change in costs, input prices, technology, or prices of related goods and
services leads to
Change in supply (shift of a supply curve).
Supply in Product/Output Markets
Shift of Supply versus Movement Along a Supply Curve
34 of 50
PART I Introduction to Economics
© 2012 Pearson Education
market supply The sum of all that is supplied
each period by all producers of a single product.
Supply in Product/Output Markets
From Individual Supply to Market Supply
35 of 50
PART I Introduction to Economics
© 2012 Pearson Education
FIGURE 3.8 Deriving Market Supply from
Individual Firm Supply Curves
Total supply in the marketplace is the sum of all
the amounts supplied by all the firms selling in
the market. It is the sum of all the individual
quantities supplied at each price.
Supply in Product/Output Markets
From Individual Supply to Market Supply
36 of 50
PART I Introduction to Economics
© 2012 Pearson Education
equilibrium The condition that exists when
quantity supplied and quantity demanded are
equal. At equilibrium, there is no tendency for
price to change.
excess demand or shortage The condition
that exists when quantity demanded exceeds
quantity supplied at the current price.
Market Equilibrium
Excess Demand
37 of 50
PART I Introduction to Economics
© 2012 Pearson Education
When quantity demanded exceeds quantity supplied, price tends
to rise. When the price in a market rises, quantity demanded falls
and quantity supplied rises until an equilibrium is reached at
which quantity demanded and quantity supplied are equal.
FIGURE 3.9 Excess Demand,
or Shortage
At a price of $1.75 per
bushel, quantity demanded
exceeds quantity supplied.
When excess demand
exists, there is a tendency
for price to rise.
When quantity demanded
equals quantity supplied,
excess demand is
eliminated and the market is
in equilibrium. Here the
equilibrium price is $2.50
and the equilibrium quantity
is 35,000 bushels.
Market Equilibrium
Excess Demand
38 of 50
PART I Introduction to Economics
© 2012 Pearson Education
excess supply or surplus The condition
that exists when quantity supplied exceeds
quantity demanded at the current price.
Market Equilibrium
Excess Supply
39 of 50
PART I Introduction to Economics
© 2012 Pearson Education
When quantity supplied exceeds quantity demanded at the current price,
the price tends to fall. When price falls, quantity supplied is likely to
decrease and quantity demanded is likely to increase until an equilibrium
price is reached where quantity supplied and quantity demanded are equal.
FIGURE 3.10 Excess Supply,
or Surplus
At a price of $3.00, quantity
supplied exceeds quantity
demanded by 20,000
bushels.
This excess supply will
cause the price to fall.
Market Equilibrium
Excess Supply
40 of 50
PART I Introduction to Economics
© 2012 Pearson Education
When supply and demand curves shift,
the equilibrium price and quantity change.
FIGURE 3.11 The Coffee
Market: A Shift of Supply and
Subsequent Price Adjustment
Before the freeze, the coffee
market was in equilibrium at
a price of $1.20 per pound.
At that price, quantity
demanded equaled quantity
supplied.
The freeze shifted the
supply curve to the left (from
S0 to S1), increasing the
equilibrium price to $2.40.
Market Equilibrium
Changes In Equilibrium
41 of 50
PART I Introduction to Economics
© 2012 Pearson Education
When supply and demand curves shift,
the equilibrium price and quantity change.
Market Equilibrium
Changes In Equilibrium
D1
$
D0
T
0.80
E
0.70
R
Quantity (thousands liters of milk)
60 70 75
An increase in income shifts the demand
curve for milk outwards to the right from D0
to D1.
At the old equilibrium price of 70 cents per
liter (point E) the quantity demanded
increases from 60 to 75 thousands liter of
milk (point R).
But 70 cents is no longer the equilibrium
price since at this price quantity demanded
(75) exceeds quantity supplied (60).
Equilibrium is restored with increases in
price.
At the new and final equilibrium (T) demand
equals supply again, price has risen to 80
cents and quantity exchanged to 70
thousand liters.
Excess
demand
42 of 50
PART I Introduction to Economics
© 2012 Pearson Education
FIGURE 3.12 Examples of
Supply and Demand Shifts
for Product X
Market Equilibrium
Changes In Equilibrium
43 of 50
PART I Introduction to Economics
© 2012 Pearson Education
1.
A demand curve shows how much of a product a
household would buy if it could buy all it wanted at the
given price. A supply curve shows how much of a
product a firm would supply if it could sell all it wanted at
the given price.
2.
Quantity demanded and quantity supplied are always
per time period—that is, per day, per month, or per
year.
3.
The demand for a good is determined by price,
household income and wealth, prices of other goods
and services, tastes and preferences, and expectations.
Here are some important points to remember about the
mechanics of supply and demand in product markets:
Demand and Supply in Product Markets: A Review
44 of 50
PART I Introduction to Economics
© 2012 Pearson Education
4.
The supply of a good is determined by price, costs of
production, and prices of related products. Costs of
production are determined by available technologies of
production and input prices.
5.
Be careful to distinguish between movements along
supply and demand curves and shifts of these curves.
When the price of a good changes, the quantity of that
good demanded or supplied changes—that is, a
movement occurs along the curve. When any other
factor changes, the curve shifts, or changes position.
6.
Market equilibrium exists only when quantity supplied
equals quantity demanded at the current price.
Here are some important points to remember about the
mechanics of supply and demand in product markets:
Demand and Supply in Product Markets: A Review
45 of 50
PART I Introduction to Economics
© 2012 Pearson Education
In 2006, the average price for a daily edition of a Baltimore newspaper was
$0.50. In 2007, the average price had risen to $0.75.
Why Do the Prices of Newspapers Rise?
E C O N O M I C S I N P R A C T I C E
46 of 50
PART I Introduction to Economics
© 2012 Pearson Education
You can already begin to see how markets answer
the basic economic questions of what is produced,
how it is produced, and who gets what is produced.
Demand curves reflect what people are willing
and able to pay for products; demand curves
are influenced by incomes, wealth, preferences,
prices of other goods, and expectations.
Firms in business to make a profit have a good
reason to choose the best available technology
—lower costs mean higher profits.
When a good is in short supply, price rises. As it
does, those who are willing and able to continue
buying do so; others stop buying.
Looking Ahead: Markets and the Allocation of Resources
47 of 50
PART I Introduction to Economics
© 2012 Pearson Education
capital market
complements, complementary goods
demand curve
demand schedule
entrepreneur
equilibrium
excess demand or shortage
excess supply or surplus
factors of production
firm
households
income
inferior goods
input or factor markets
labor market
land market
law of demand
law of supply
market demand
market supply
movement along a demand curve
movement along a supply curve
normal goods
perfect substitutes
product or output markets
profit
quantity demanded
quantity supplied
shift of a demand curve
shift of a supply curve
substitutes
supply curve
supply schedule
wealth or net worth
R E V I E W T E R M S A N D C O N C E P T
S