
ACO 201 Chapter 2, Spring 2013
Notre Dame University–Louaize · Principles of Accounting I · 40 pages

Showing the first 10 of 40 pages. Download the PDF to see all of it.
More ACO 201 files
- Chapter 1 · Spring 2013ChapterView
- Chapter 3 · Spring 2013ChapterView
- Chapter 4 · Spring 2013ChapterView
- Chapter 5 · Spring 2013ChapterView
- Chapter 6 · Spring 2013ChapterView
- Chapter 7 · Spring 2013ChapterView
- Problems Chapter 2 Solution · Spring 2013Chapter · with solutionView
- Problems Chapter 3 Solution · Spring 2013Chapter · with solutionView
Show the text of this chapter
McGraw-Hill/Irwin
Copyright © 2010 by The McGraw-Hill Companies, Inc. All rights reserved.
Basic Financial Statements
Basic Financial Statements
Chapter 2
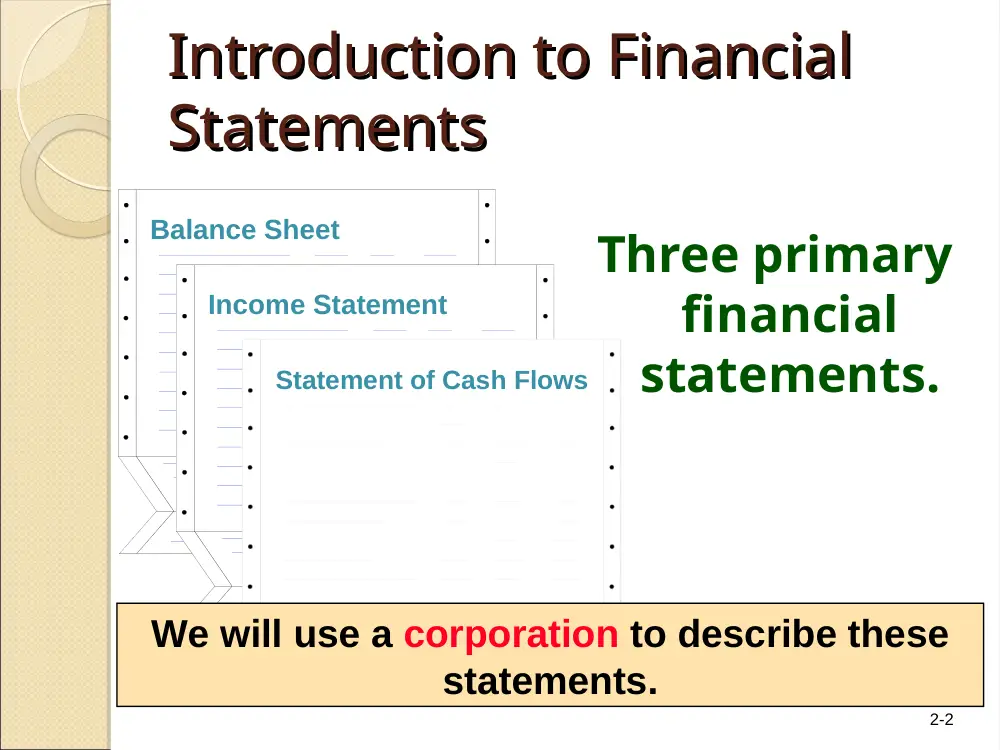
2-2
Introduction to Financial
Introduction to Financial
Statements
Statements
Three primary
financial
statements.
Income Statement
Balance Sheet
Statement of Cash Flows
We will use a corporation to describe these
statements.
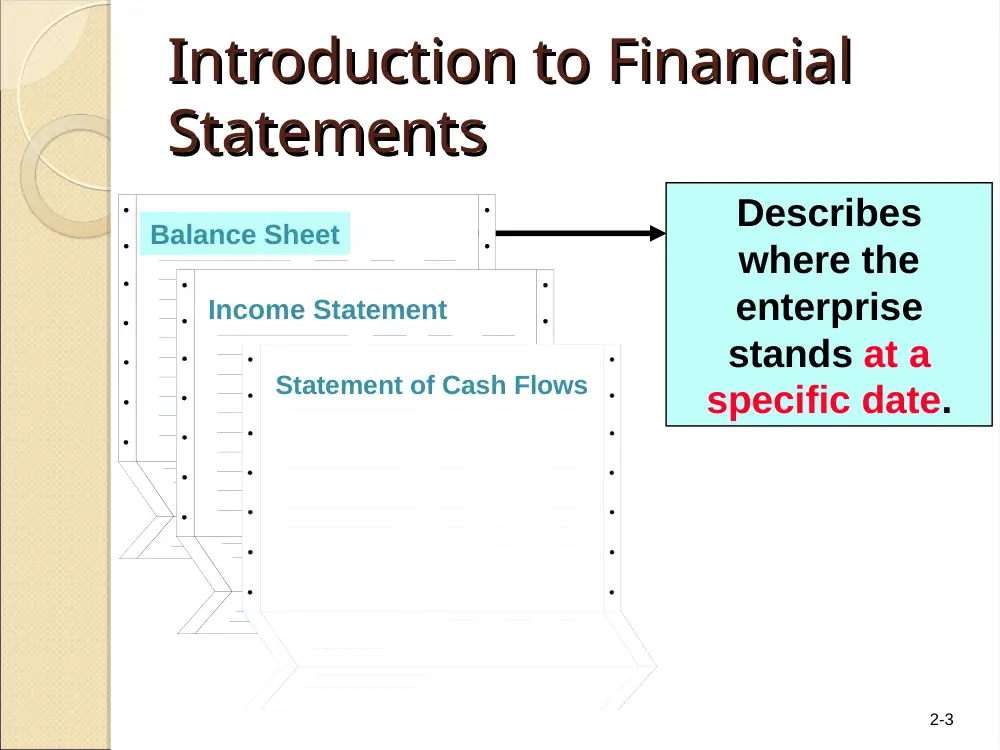
2-3
Describes
where the
enterprise
stands at a
specific date.
Income Statement
Balance Sheet
Statement of Cash Flows
Introduction to Financial
Introduction to Financial
Statements
Statements
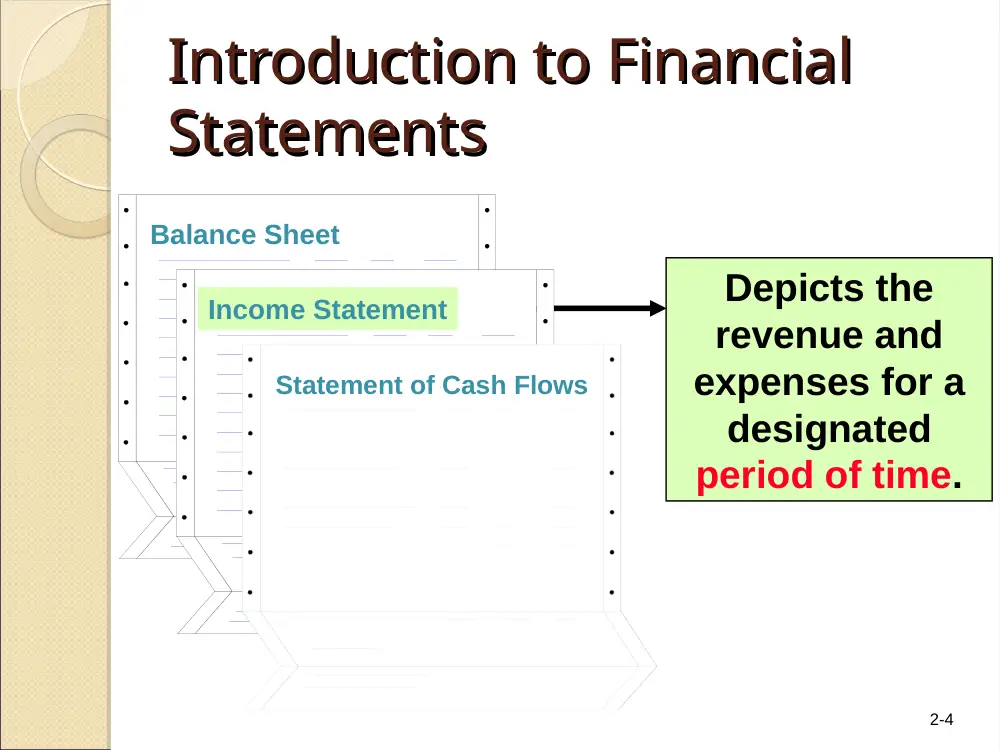
2-4
Depicts the
revenue and
expenses for a
designated
period of time.
Income Statement
Balance Sheet
Statement of Cash Flows
Introduction to Financial
Introduction to Financial
Statements
Statements
2-5
Depicts the
ways cash has
changed during
a designated
period of time.
Income Statement
Balance Sheet
Statement of Cash Flows
Introduction to Financial
Introduction to Financial
Statements
Statements
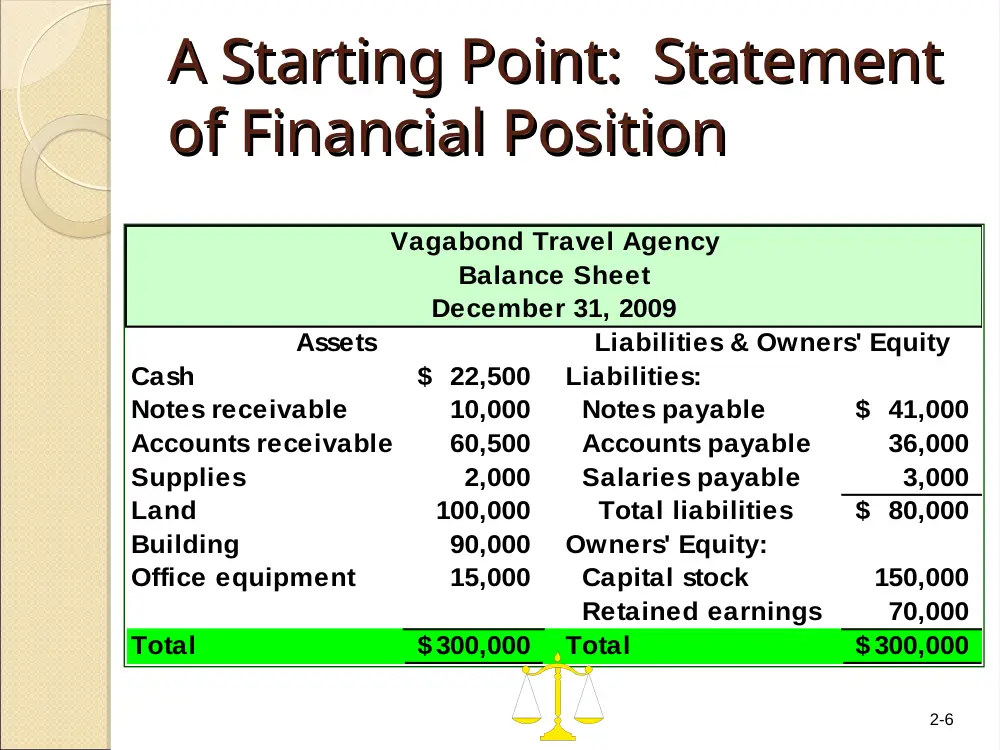
2-6
Vagabond Travel Agency
Balance Sheet
December 31, 2009
Assets
Liabilities & Owners' Equity
Cash
22,500
$
Liabilities:
Notes receivable
10,000
Notes payable
41,000
$
Accounts receivable
60,500
Accounts payable
36,000
Supplies
2,000
Salaries payable
3,000
Land
100,000
Total liabilities
80,000
$
Building
90,000
Owners' Equity:
Office equipment
15,000
Capital stock
150,000
Retained earnings
70,000
Total
$ 300,000
Total
300,000
$
A Starting Point: Statement
A Starting Point: Statement
of Financial Position
of Financial Position
2-7
The Concept of the Business
The Concept of the Business
Entity
Entity
Vagabond
Travel
Agency
A business
entity is
separate from
the personal
affairs of its
owner.
2-8
Vagabond Travel Agency
Balance Sheet
December 31, 2009
Assets
Liabilities & Owners' Equity
Cash
22,500
$
Liabilities:
Notes receivable
10,000
Notes payable
41,000
$
Accounts receivable
60,500
Accounts payable
36,000
Supplies
2,000
Salaries payable
3,000
Land
100,000
Total liabilities
80,000
$
Building
90,000
Owners' Equity:
Office equipment
15,000
Capital stock
150,000
Retained earnings
70,000
Total
$ 300,000
Total
300,000
$
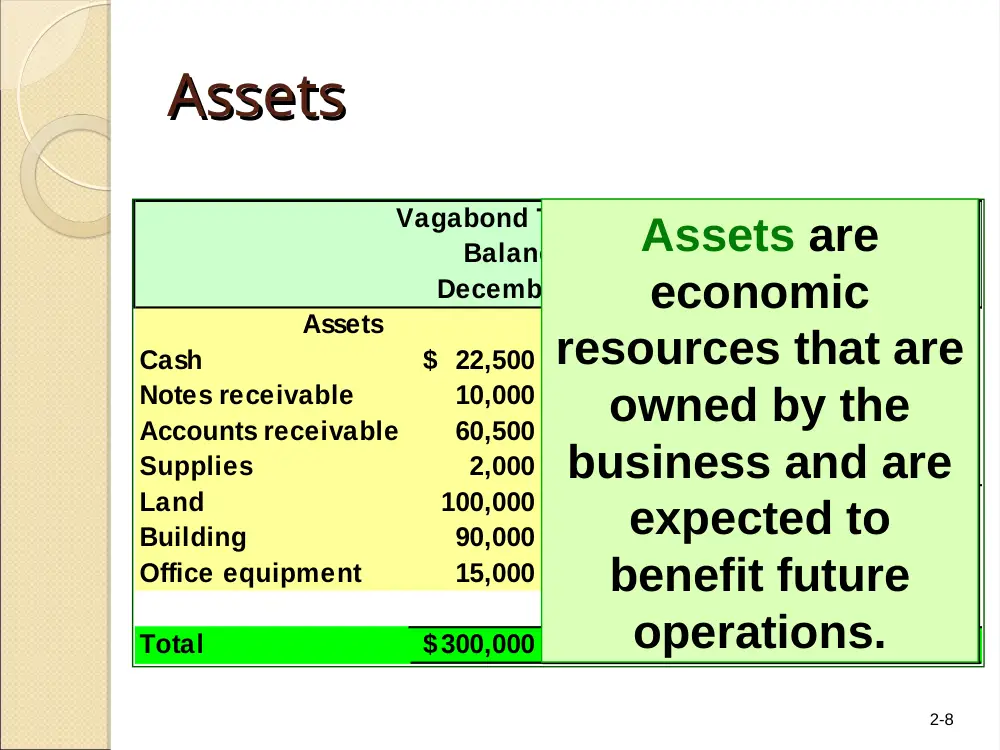
Assets
Assets
Assets are
economic
resources that are
owned by the
business and are
expected to
benefit future
operations.
Assets are
economic
resources that are
owned by the
business and are
expected to
benefit future
operations.
2-9
Assets
Assets
Cost Principle
Cost Principle
Cost Principle
Cost Principle
Going-Concern
Going-Concern
Assumption
Assumption
Going-Concern
Going-Concern
Assumption
Assumption
Objectivity
Objectivity
Principle
Principle
Objectivity
Objectivity
Principle
Principle
Stable-Dollar
Stable-Dollar
Assumption
Assumption
Stable-Dollar
Stable-Dollar
Assumption
Assumption
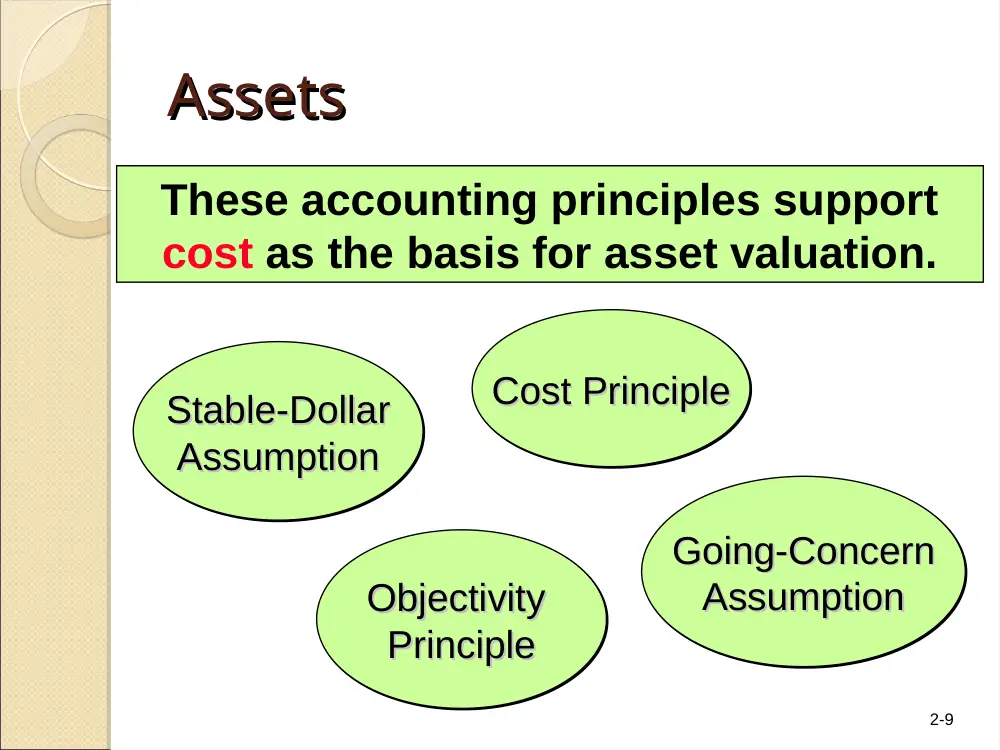
These accounting principles support
cost as the basis for asset valuation.
2-10
Vagabond Travel Agency
Balance Sheet
December 31, 2009
Assets
Liabilities & Owners' Equity
Cash
22,500
$
Liabilities:
Notes receivable
10,000
Notes payable
41,000
$
Accounts receivable
60,500
Accounts payable
36,000
Supplies
2,000
Salaries payable
3,000
Land
100,000
Total liabilities
80,000
$
Building
90,000
Owners' Equity:
Office equipment
15,000
Capital stock
150,000
Retained earnings
70,000
Total
$ 300,000
Total
300,000
$
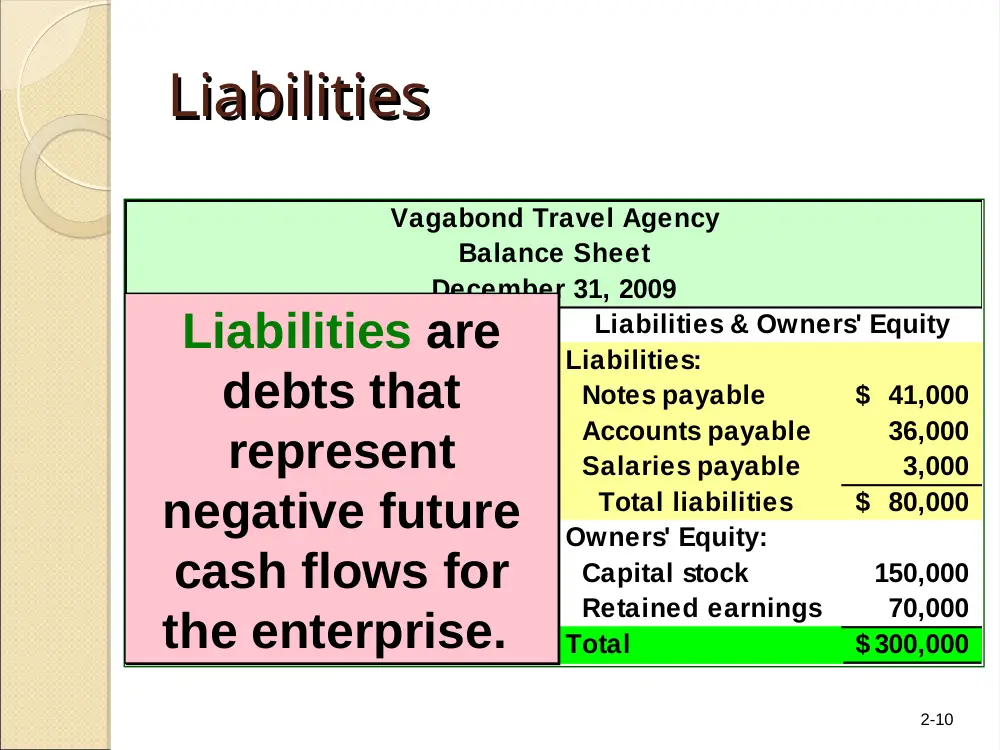
Liabilities
Liabilities
Liabilities are
debts that
represent
negative future
cash flows for
the enterprise.
Liabilities are
debts that
represent
negative future
cash flows for
the enterprise.
2-11
Owners’ Equity
Owners’ Equity
Vagabond Travel Agency
Balance Sheet
December 31, 2009
Assets
Liabilities & Owners' Equity
Cash
22,500
$
Liabilities:
Notes receivable
10,000
Notes payable
41,000
$
Accounts receivable
60,500
Accounts payable
36,000
Supplies
2,000
Salaries payable
3,000
Land
100,000
Total liabilities
80,000
$
Building
90,000
Owners' Equity:
Office equipment
15,000
Capital stock
150,000
Retained earnings
70,000
Total
$ 300,000
Total
300,000
$
Owners’ equity
represents the
owners’ claims
on the assets of
the business.
Owners’ equity
represents the
owners’ claims
on the assets of
the business.
2-12
Vagabond Travel Agency
Balance Sheet
December 31, 2009
Assets
Liabilities & Owners' Equity
Cash
22,500
$
Liabilities:
Notes receivable
10,000
Notes payable
41,000
$
Accounts receivable
60,500
Accounts payable
36,000
Supplies
2,000
Salaries payable
3,000
Land
100,000
Total liabilities
80,000
$
Building
90,000
Owners' Equity
Office equipment
15,000
Capital stock
150,000
Retained earnings
70,000
Total
$ 300,000
Total
300,000
$
The Accounting Equation
The Accounting Equation
Assets = Liabilities + Owners’ Equity
$300,000 = $80,000 + $220,000
Assets = Liabilities + Owners’ Equity
$300,000 = $80,000 + $220,000
2-13
Let’s analyze
transactions
for JJ’s Lawn
Care Service.
2-14
JJ's Lawn Care Service
Balance Sheet
May 1, 2009
Assets
Cash
8,000
$
Capital Stock
8,000
$
Total
8,000
$
Total
8,000
$
Owners' Equity
On May 1, Jill Jones and her family
invested $8,000 in JJ’s Lawn Care Service
and received 800 shares of stock.
2-15
JJ's Lawn Care Service
Balance Sheet
May 2, 2009
Assets
Cash
5,500
$
Capital Stock
8,000
$
Tools & Equipment
2,500
Total
8,000
$
Total
8,000
$
Owners' Equity
On May 2, JJ’s purchased a riding lawn
mower for $2,500 cash.
2-16
On May 8, JJ’s purchased a $15,000 truck.
JJ’s paid $2,000 down in cash and issued
a note payable for the remaining $13,000.
JJ's Lawn Care Service
Balance Sheet
May 8, 2009
Assets
Cash
3,500
$
Liabilities:
Tools & Equipment
2,500
Notes Payable
13,000
$
Truck
15,000
Owners' Equity:
Capital Stock
8,000
Total
21,000
$
Total
21,000
$
Liabilities and Owners' Equity
2-17
JJ's Lawn Care Service
Balance Sheet
May 11, 2009
Assets
Cash
3,500
$
Liabilities:
Tools & Equipment
2,800
Notes Payable
13,000
$
Truck
15,000
Accounts Payable
300
Total Liabilities
13,300
$
Owners' Equity:
Capital Stock
8,000
Total
21,300
$
Total
21,300
$
Liabilities and Owners' Equity
On May 11, JJ’s purchased some repair
parts for $300 on account.
2-18
JJ's Lawn Care Service
Balance Sheet
May 18, 2009
Assets
Cash
3,500
$
Liabilities:
Accounts Receivable
150
Notes Payable
13,000
$
Tools & Equipment
2,650
Accounts Payable
300
Truck
15,000
Total Liabilities
13,300
$
Owners' Equity:
Capital Stock
8,000
Total
21,300
$
Total
21,300
$
Liabilities and Owners' Equity
Jill realized she had purchased more repair parts than
needed.
On May 18, JJ’s was able to sell half of the repair parts to
ABC Lawns for $150, a price equal to JJ’s cost. JJ’s will
receive the cash within 30 days.
2-19
JJ's Lawn Care Service
Balance Sheet
May 25, 2009
Assets
Cash
3,575
$
Liabilities:
Accounts Receivable
75
Notes Payable
13,000
$
Tools & Equipment
2,650
Accounts Payable
300
Truck
15,000
Total Liabilities
13,300
$
Owners' Equity:
Capital Stock
8,000
Total
21,300
$
Total
21,300
$
Liabilities and Owners' Equity
On May 25, ABC Lawns pays JJ’s $75 as a
partial settlement of its accounts
receivable.
2-20
JJ's Lawn Care Service
Balance Sheet
May 28, 2009
Assets
Cash
3,425
$
Liabilities:
Accounts Receivable
75
Notes Payable
13,000
$
Tools & Equipment
2,650
Accounts Payable
150
Truck
15,000
Total Liabilities
13,150
Owners' Equity:
Capital Stock
8,000
Total
21,150
$
Total
21,150
$
Liabilities and Owners' Equity
On May 28, JJ’s pays $150 of its accounts
payable.
2-21
JJ's Lawn Care Service
Balance Sheet
May 29, 2009
Assets
Cash
4,175
$
Liabilities:
Accounts Receivable
75
Notes Payable
13,000
$
Tools & Equipment
2,650
Accounts Payable
150
Truck
15,000
Total Liabilities
13,150
Owners' Equity:
Capital Stock
8,000
Retained Earnings
750
Total
21,900
$
Total
21,900
$
Liabilities and Owners' Equity
On May 29, JJ’s recorded lawn care
services provided during May of $750. All
clients were paid in cash.
2-22
JJ's Lawn Care Service
Balance Sheet
May 31, 2009
Assets
Cash
4,125
$
Liabilities:
Accounts Receivable
75
Notes Payable
13,000
$
Tools & Equipment
2,650
Accounts Payable
150
Truck
15,000
Total Liabilities
13,150
Owners' Equity:
Capital Stock
8,000
Retained Earnings
700
Total
21,850
$
Total
21,850
$
Liabilities and Owners' Equity
Now, let’s review how JJ’s transactions
affected the accounting equation.
On May 31, JJ’s purchased gasoline for
the lawn mower and the truck for $50 cash.
2-23
Assets
=
Liabilities
+
Cash
+
Accts.
Rec.
+
Tools &
Equip.
+
Truck
=
Notes
Payable +
Accts.
Pay.
+
Capital
Stock
+
Retained
Earnings
May 1
$ 8,000
8,000
$
Balances
$ 8,000
8,000
$
May 2
(2,500)
2,500
$
Balances
$ 5,500
$ 2,500
8,000
$
May 8
(2,000)
$ 15,000
13,000
$
Balances
$ 3,500
$ 2,500
$ 15,000
$ 13,000
8,000
$
May 11
300
300
$
Balances
$ 3,500
$ 2,800
$ 15,000
$ 13,000
$ 300
8,000
$
May 18
$ 150
(150)
Balances
$ 3,500
$ 150
$ 2,650
$ 15,000
$ 13,000
$ 300
8,000
$
May 25
75
(75)
Balances
$ 3,575
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 300
8,000
$
May 28
(150)
(150)
Balances
$ 3,425
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 150
8,000
$
May 29
750
750
Balances
$ 4,175
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 150
$ 8,000
750
$
May 31
(50)
(50)
Balances
$ 4,125
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 150
$ 8,000
700
$
Owners' Equity
2-24
Assets
=
Liabilities
+
Cash
+
Accts.
Rec.
+
Tools &
Equip.
+
Truck
=
Notes
Payable +
Accts.
Pay.
+
Capital
Stock
+
Retained
Earnings
May 1
$ 8,000
8,000
$
Balances
$ 8,000
8,000
$
May 2
(2,500)
2,500
$
Balances
$ 5,500
$ 2,500
8,000
$
May 8
(2,000)
$ 15,000
13,000
$
Balances
$ 3,500
$ 2,500
$ 15,000
$ 13,000
8,000
$
May 11
300
300
$
Balances
$ 3,500
$ 2,800
$ 15,000
$ 13,000
$ 300
8,000
$
May 18
$ 150
(150)
Balances
$ 3,500
$ 150
$ 2,650
$ 15,000
$ 13,000
$ 300
8,000
$
May 25
75
(75)
Balances
$ 3,575
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 300
8,000
$
May 28
(150)
(150)
Balances
$ 3,425
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 150
8,000
$
May 29
750
750
Balances
$ 4,175
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 150
$ 8,000
750
$
May 31
(50)
(50)
Balances
$ 4,125
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 150
$ 8,000
700
$
Owners' Equity
These transactions
impact the
Statement of Cash
Flows.
These transactions
impact the
Statement of Cash
Flows.
These transactions
impact the Income
Statement.
These transactions
impact the Income
Statement.
Let’s prepare the Income Statement and
Statement of Cash Flows for JJ’s Lawn Care
Service for the month ending May 31, 2009.
2-25
JJ's Lawn Care Service
Income Statement
For the Month Ended May 31, 2009
Sales Revenue
750
$
Operating Expense:
Gasoline Expense
50
Net Income
700
$
Investments by and payments to the owners
are not included on the Income Statement.
Investments by and payments to the owners
are not included on the Income Statement.
2-26
JJ's Lawn Care Service
Statement of Cash Flows
For the Month Ended May 31, 2009
Cash flows from operating activities:
Cash received from revenue transactions
750
$
Cash paid for expenses
(50)
Net cash provided by operating activities
700
$
Cash flows from investing activities:
Purchase of lawn mower
(2,500)
$
Purchase of truck
(2,000)
Collection for sale of repair parts
75
Payment for repair parts
(150)
Net cash used by investing activities
(4,575)
Cash flows from financing activities:
Investment by owners
8,000
Increase in cash for month
4,125
$
Cash balance, May 1, 2009
-
Cash balance, May 31, 2009
$ 4,125
2-27
JJ's Lawn Care Service
Statement of Cash Flows
For the Month Ended May 31, 2009
Cash flows from operating activities:
Cash received from revenue transactions
750
$
Cash paid for expenses
(50)
Net cash provided by operating activities
700
$
Cash flows from investing activities:
Purchase of lawn mower
(2,500)
$
Purchase of truck
(2,000)
Collection for sale of repair parts
75
Payment for repair parts
(150)
Net cash used by investing activities
(4,575)
Cash flows from financing activities:
Investment by owners
8,000
Increase in cash for month
4,125
$
Cash balance, May 1, 2009
-
Cash balance, May 31, 2009
4,125
$
Operating activities include the cash
effects of revenue and expense
transactions.
Operating activities include the cash
effects of revenue and expense
transactions.
2-28
JJ's Lawn Care Service
Statement of Cash Flows
For the Month Ended May 31, 2009
Cash flows from operating activities:
Cash received from revenue transactions
750
$
Cash paid for expenses
(50)
Net cash provided by operating activities
700
$
Cash flows from investing activities:
Purchase of lawn mower
(2,500)
$
Purchase of truck
(2,000)
Collection for sale of repair parts
75
Payment for repair parts
(150)
Net cash used by investing activities
(4,575)
Cash flows from financing activities:
Investment by owners
8,000
Increase in cash for month
4,125
$
Cash balance, May 1, 2009
-
Cash balance, May 31, 2009
4,125
$
Investing activities include the cash
effects of purchasing and selling
assets.
Investing activities include the cash
effects of purchasing and selling
assets.
2-29
JJ's Lawn Care Service
Statement of Cash Flows
For the Month Ended May 31, 2009
Cash flows from operating activities:
Cash received from revenue transactions
750
$
Cash paid for expenses
(50)
Net cash provided by operating activities
700
$
Cash flows from investing activities:
Purchase of lawn mower
(2,500)
$
Purchase of truck
(2,000)
Collection for sale of repair parts
75
Payment for repair parts
(150)
Net cash used by investing activities
(4,575)
Cash flows from financing activities:
Investment by owners
8,000
Increase in cash for month
4,125
$
Cash balance, May 1, 2009
-
Cash balance, May 31, 2009
4,125
$
Financing activities include the cash
effects of transactions with the owners
and creditors.
Financing activities include the cash
effects of transactions with the owners
and creditors.
2-30
Assets
=
Liabilities
+
Cash
+
Accts.
Rec.
+
Tools &
Equip.
+
Truck
=
Notes
Payable +
Accts.
Pay.
+
Capital
Stock
+
Retained
Earnings
May 1
$ 8,000
8,000
$
Balances
$ 8,000
8,000
$
May 2
(2,500)
2,500
$
Balances
$ 5,500
$ 2,500
8,000
$
May 8
(2,000)
$ 15,000
13,000
$
Balances
$ 3,500
$ 2,500
$ 15,000
$ 13,000
8,000
$
May 11
300
300
$
Balances
$ 3,500
$ 2,800
$ 15,000
$ 13,000
$ 300
8,000
$
May 18
$ 150
(150)
Balances
$ 3,500
$ 150
$ 2,650
$ 15,000
$ 13,000
$ 300
8,000
$
May 25
75
(75)
Balances
$ 3,575
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 300
8,000
$
May 28
(150)
(150)
Balances
$ 3,425
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 150
8,000
$
May 29
750
750
Balances
$ 4,175
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 150
$ 8,000
750
$
May 31
(50)
(50)
Balances
$ 4,125
$ 75
$ 2,650
$ 15,000
$ 13,000
$ 150
$ 8,000
700
$
Owners' Equity
Now, let’s prepare the Balance Sheet for JJ’s
Lawn Care Service for May 31, 2009.
These balances will
appear on the
Balance Sheet.
These balances will
appear on the
Balance Sheet.
2-31
Cash
$ 4,125
Notes payable
13,000
$
Accounts receivable
75
Accounts payable
150
Tools & equipment
2,650
Truck
15,000
Capital stock
8,000
Retained earnings
700
Total assets
21,850
$
Total liabilities & equity
21,850
$
Assets
Liabilities
Owners' Equity
JJ's Lawn Care Service
Balance Sheet
May 31, 2009
Assets = Liabilities + Owners’ Equity
$21,850 = $13,150 + $8,700
Assets = Liabilities + Owners’ Equity
$21,850 = $13,150 + $8,700
2-32
Relationships Among
Relationships Among
Financial Statements
Financial Statements
Date at
beginning of
period
Date at
end of
period
Balance
Sheet
Balance
Sheet
Time
Income Statement
Statement of Cash Flows
2-33
JJ's Lawn Care Service
Statement of Cash Flows
For the Month Ended May 31, 2009
Cash flows from operating activities:
Cash received from revenue transactions
750
$
Cash paid for expenses
(50)
Net cash provided by operating activities
700
$
Cash flows from investing activities:
Purchase of lawn mower
(2,500)
$
Purchase of truck
(2,000)
Collection for sale of repair parts
75
Payment for repair parts
(150)
Net cash used by investing activities
(4,575)
Cash flows from financing activities:
Investment by owners
8,000
Increase in cash for month
4,125
$
Cash balance, May 1, 2009
-
Cash balance, May 31, 2009
4,125
$
Cash
$ 4,125
Notes payable
13,000
$
Accounts receivable
75
Accounts payable
150
Tools & equipment
2,650
Truck
15,000
Capital stock
8,000
Retained earnings
700
Total assets
21,850
$
Total liabilities & equity
21,850
$
Assets
Liabilities
Owners' Equity
JJ's Lawn Care Service
Balance Sheet
May 31, 2009
JJ's Lawn Care Service
Income Statement
Sales Revenue
750
$
Operating Expense:
Gasoline Expense
50
Net Income
700
$
For the Month Ended May 31, 2009
Financial Statement
Financial Statement
Articulation
Articulation
2-34
Statement
of Cash
Flows
Balance
Sheet
Income
Statement
Other Information:
•Industry
•Competitors
•National economy
Financial Reporting and
Financial Reporting and
Financial Statements
Financial Statements
Financial statements are
just one source of
financial accounting
information.
Financial statements are
just one source of
financial accounting
information.
2-35
Forms of Business
Forms of Business
Organization
Organization
Sole
Proprietorships
Sole
Proprietorships
Partnerships
Partnerships
Corporations
Corporations
2-36
Reporting Ownership Equity in
Reporting Ownership Equity in
the Statement of Financial
the Statement of Financial
Position
Position
Owner's equity:
Jill Jones, capital
8,000
$
Sole
Proprietorships
Sole
Proprietorships
Partners' equity
Jill Jones, capital
4,000
$
Bill Jones, capital
4,000
Total partners' equity
8,000
$
Partnerships
Partnerships
Owners' equity
Capital stock
7,000
$
Retained earnings
1,000
Total stockholders' equity
8,000
$
Corporations
Corporations
2-37
The Use of Financial
The Use of Financial
Statements by External
Statements by External
Parties
Parties
Creditors
Investors
Two concerns:
Liquidity
Profitability
Two concerns:
Liquidity
Profitability
2-38
The Need for Adequate
The Need for Adequate
Disclosure
Disclosure
Income Statement
Balance Sheet
Statement of Cash Flows
Notes to the
financial
statements
often provide
facts necessary
for the proper
interpretation of
the statements.
Notes to the
financial
statements
often provide
facts necessary
for the proper
interpretation of
the statements.
2-39
Management’s Interest in
Management’s Interest in
Financial Statements
Financial Statements
Creditors are more likely to extend credit if
financial statements show a strong statement of
financial position—that is, relatively little debt
and large amounts of liquid assets.
Window dressing occurs when management
takes measures to make the company appear
as strong as possible in it financial statements.
2-40
End of Chapter 2
End of Chapter 2