
ACO 201 Chapter 7, Spring 2013
Notre Dame University–Louaize · Principles of Accounting I · 40 pages


Showing the first 10 of 40 pages. Download the PDF to see all of it.
More ACO 201 files
- Chapter 1 · Spring 2013ChapterView
- Chapter 2 · Spring 2013ChapterView
- Chapter 3 · Spring 2013ChapterView
- Chapter 4 · Spring 2013ChapterView
- Chapter 5 · Spring 2013ChapterView
- Chapter 6 · Spring 2013ChapterView
- Problems Chapter 2 Solution · Spring 2013Chapter · with solutionView
- Problems Chapter 3 Solution · Spring 2013Chapter · with solutionView
Show the text of this chapter
Copyright © 2010 by The McGraw-Hill Companies, Inc. All rights reserved.
McGraw-Hill/Irwin
Financial Assets
Financial Assets
Chapter 7
7-2
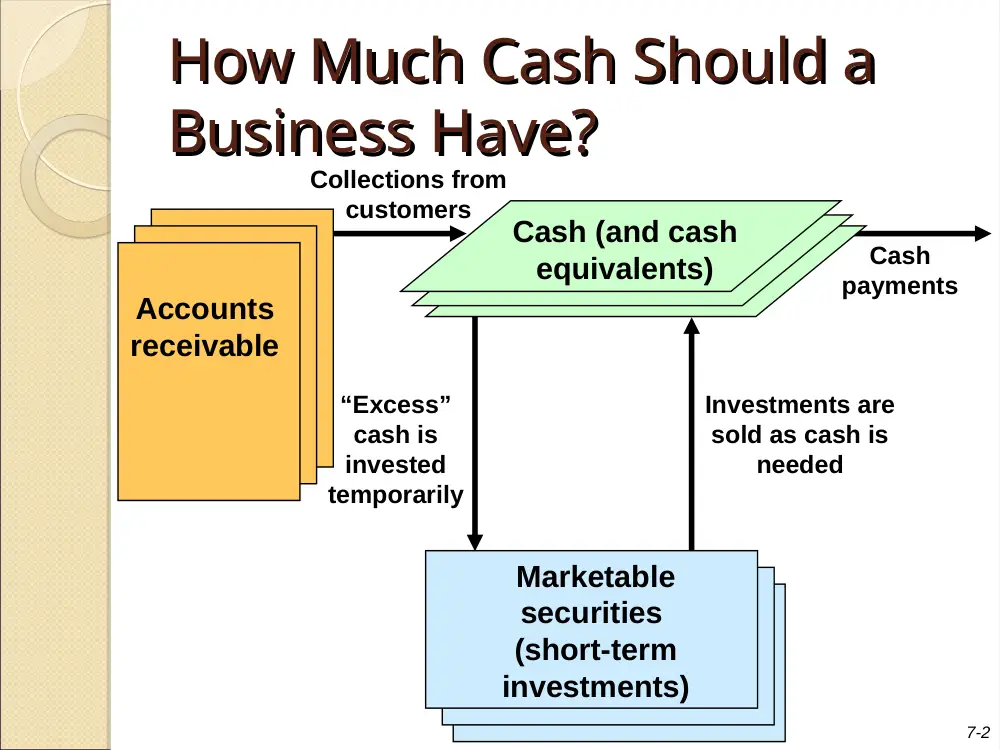
How Much Cash Should a
How Much Cash Should a
Business Have?
Business Have?
Accounts
receivable
Marketable
securities
(short-term
investments)
Cash (and cash
equivalents)
Collections from
customers
Cash
payments
“Excess”
cash is
invested
temporarily
Investments are
sold as cash is
needed
7-3
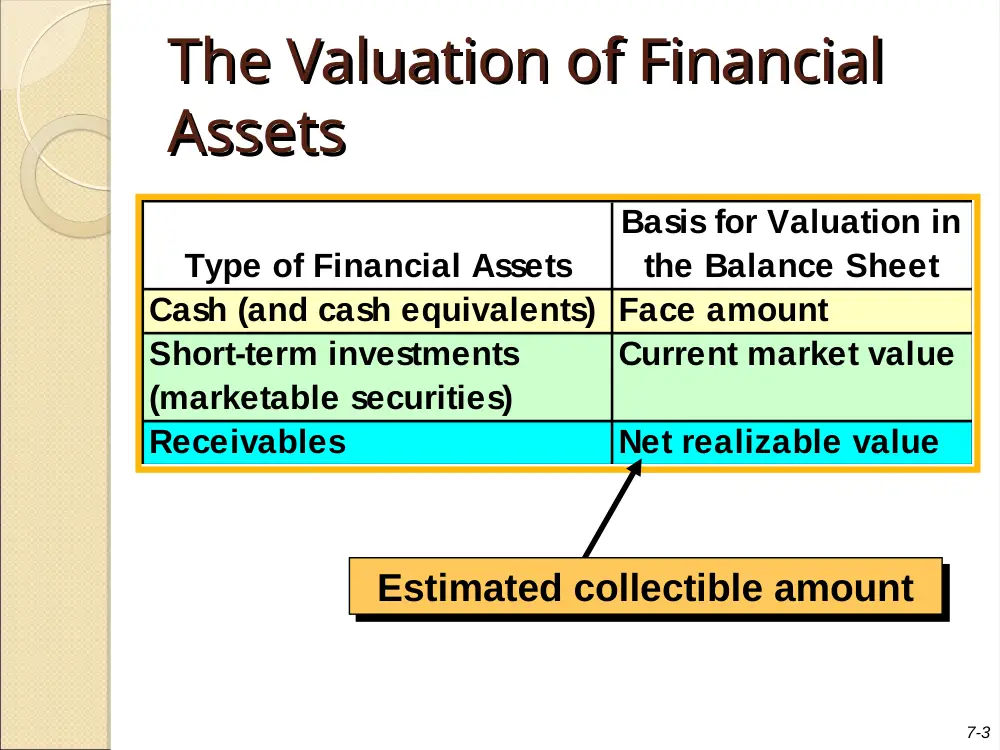
The Valuation of Financial
The Valuation of Financial
Assets
Assets
Type of Financial Assets
Basis for Valuation in
the Balance Sheet
Cash (and cash equivalents) Face amount
Short-term investments
(marketable securities)
Current market value
Receivables
Net realizable value
Estimated collectible amount
Estimated collectible amount
7-4
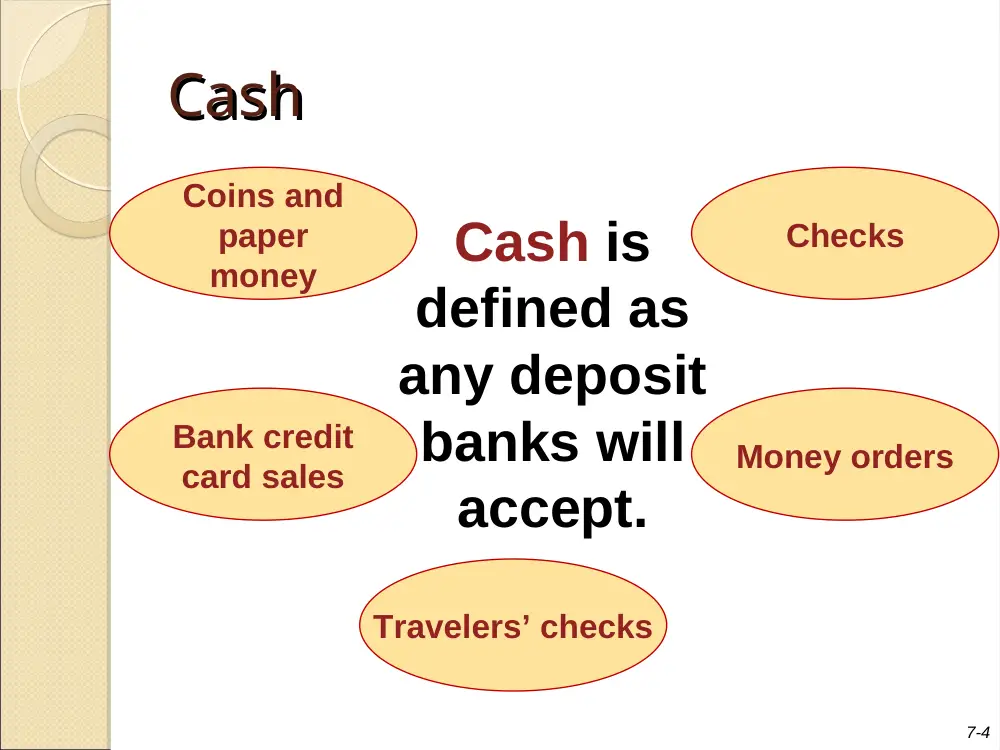
Cash
Cash
Coins and
paper
money
Checks
Money orders
Travelers’ checks
Bank credit
card sales
Cash is
defined as
any deposit
banks will
accept.
7-5
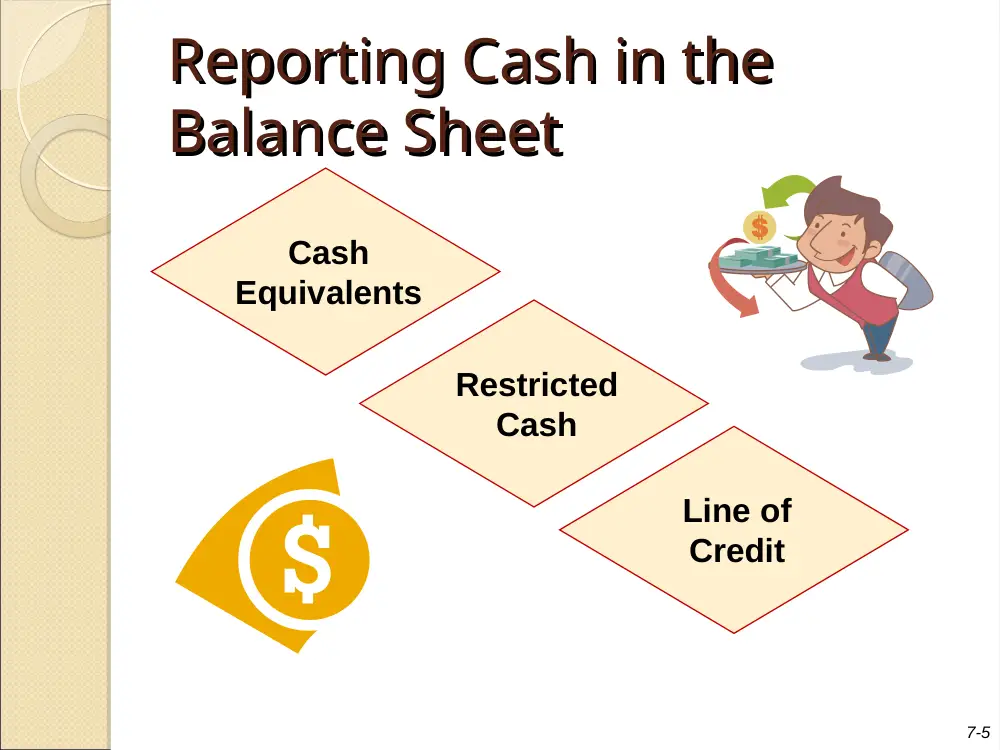
Reporting Cash in the
Reporting Cash in the
Balance Sheet
Balance Sheet
Cash
Equivalents
Restricted
Cash
Line of
Credit
7-6
Cash Management
Cash Management
Accurately account for cash.
Prevent theft and fraud.
Assure the availability of adequate
amounts of cash.
Prevent unnecessarily large
amounts of idle cash.
Accurately account for cash.
Prevent theft and fraud.
Assure the availability of adequate
amounts of cash.
Prevent unnecessarily large
amounts of idle cash.
7-7
Internal Control Over Cash
Internal Control Over Cash
• Segregate authorization, custody and
recording of cash.
• Prepare a cash budget (or forecast).
• Prepare a control listing of cash receipts.
• Require daily deposits.
• Make all payments by check.
• Require that every expenditure be
verified before payment.
• Promptly reconcile bank statements.
• Segregate authorization, custody and
recording of cash.
• Prepare a cash budget (or forecast).
• Prepare a control listing of cash receipts.
• Require daily deposits.
• Make all payments by check.
• Require that every expenditure be
verified before payment.
• Promptly reconcile bank statements.
7-8
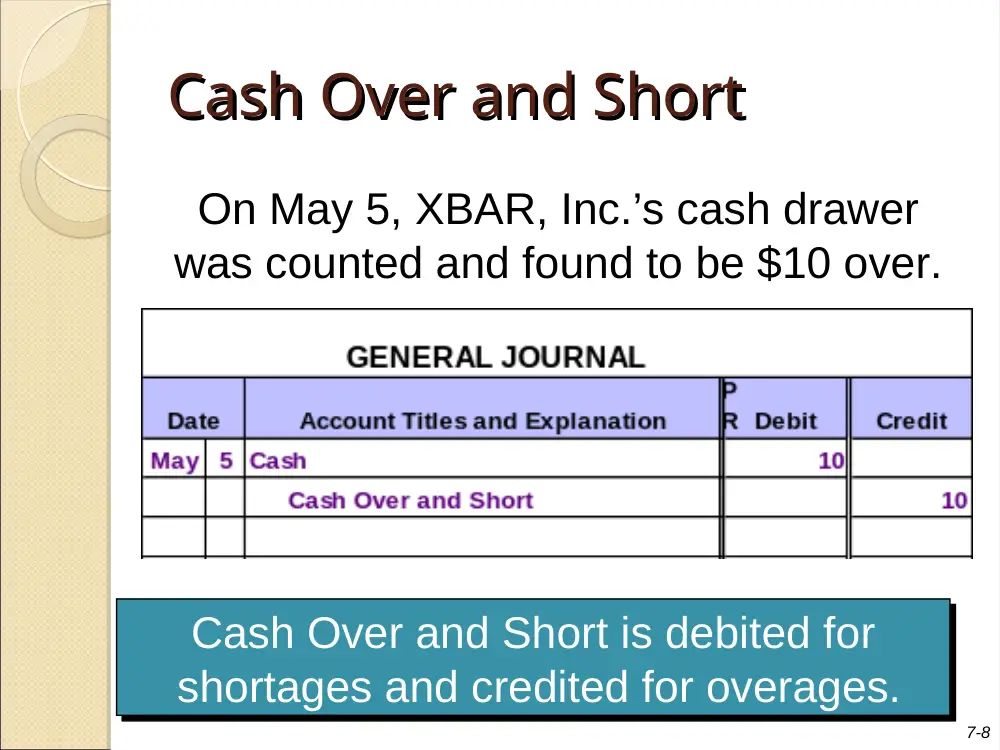
Cash Over and Short
Cash Over and Short
Cash Over and Short is debited for
shortages and credited for overages.
Cash Over and Short is debited for
shortages and credited for overages.
On May 5, XBAR, Inc.’s cash drawer
was counted and found to be $10 over.
7-9
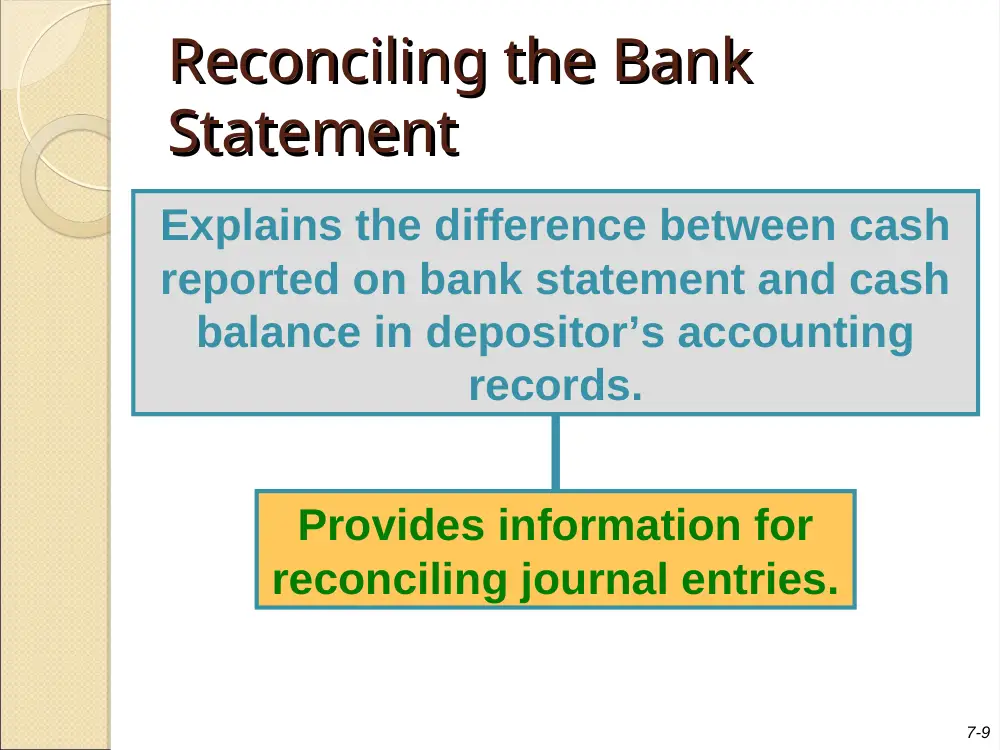
Reconciling the Bank
Reconciling the Bank
Statement
Statement
Explains the difference between cash
reported on bank statement and cash
balance in depositor’s accounting
records.
Provides information for
reconciling journal entries.
7-10
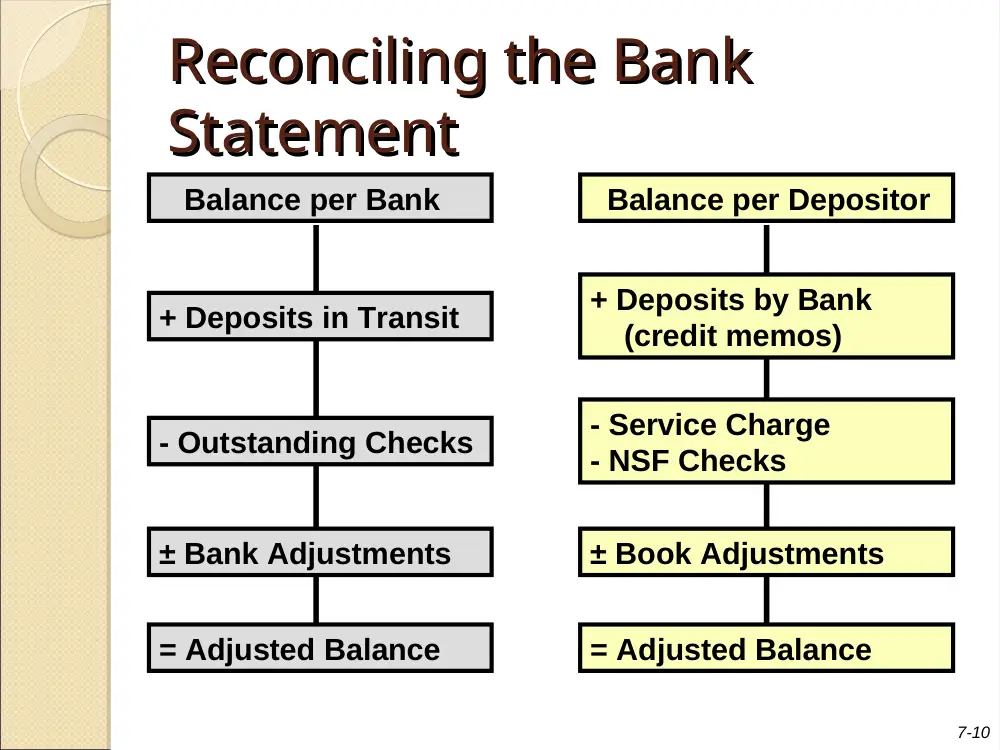
Reconciling the Bank
Reconciling the Bank
Statement
Statement
Balance per Bank
+ Deposits in Transit
- Outstanding Checks
± Bank Adjustments
= Adjusted Balance
Balance per Depositor
+ Deposits by Bank
(credit memos)
- Service Charge
- NSF Checks
± Book Adjustments
= Adjusted Balance
7-11
Reconciling the Bank
Reconciling the Bank
Statement
Statement
• The July 31 bank statement for Simmons Company
indicated a cash balance of $9,610
• The cash ledger account on that date shows a balance
of $7,430.
• Outstanding checks totaled $2,417.
• A $500 check mailed to the bank for deposit had not
reached the bank at the statement date.
• The bank returned a customer’s NSF check for $225
received as payment of an account receivable.
• The bank statement showed $30 interest earned on the
bank balance for the month of July.
• Check 781 for supplies cleared the bank for $268 but
was erroneously recorded in our books as $240.
• A $486 deposit by Acme Company was erroneously
credited to our account by the bank.
7-12
Reconciling the Bank
Reconciling the Bank
Statement
Statement
Balance per bank statement, July 31
9,610
$
Additions:
Deposit in transit
500
Deductions:
Bank error
486
$
Outstanding checks
2,417
2,903
Adjusted cash balance
7,207
$
Balance per depositor's records, July 31
7,430
$
Additions:
Interest
30
Deductions:
Recording error
28
$
NSF check
225
253
Adjusted cash balance
7,207
$
7-13
Reconciling the Bank
Reconciling the Bank
Statement
Statement
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Jul
31 Cash
30
Interest Revenue
30
31 Supplies Inventory
28
Accounts Receivable
225
Cash
253
7-14
Used for minor
expenditures.
Petty Cash Funds
Petty Cash Funds
Has one
custodian.
Replenished
periodically.
Petty Cash
Funds
7-15
Short-Term Investments
Short-Term Investments
Bond
Investments
Capital
Stock
Investments
Current Assets
Almost As
Liquid As
Cash
Readily
Marketable
Marketable
Securities
are . . .
7-16
Purchase of Marketable Securities
Purchase of Marketable Securities
Foster Corporation purchases as a short-term
investment 4,000 shares of The Coca-Cola
Company on December 1. Foster paid
$48.98 per share, plus a brokerage
commission of $80.
Foster Corporation purchases as a short-term
investment 4,000 shares of The Coca-Cola
Company on December 1. Foster paid
$48.98 per share, plus a brokerage
commission of $80.
Total Cost: (4,000 × $48.98) + $80 = $196,000
Cost per Share: $196,000 ÷ 4,000 = $49.00
7-17
Recognition of Investment
Recognition of Investment
Revenue
Revenue
On December 15, Foster Corporation
receives a $0.30 per share dividend
on its 4,000 shares of Coca-Cola.
On December 15, Foster Corporation
receives a $0.30 per share dividend
on its 4,000 shares of Coca-Cola.
4,000 × $0.30 = $1,200
7-18
Sales of Investments
Sales of Investments
On December 18, Foster Corporation sells 500
shares of its Coca-Cola stock for $50.04 per
share, less a $20 brokerage commission.
On December 18, Foster Corporation sells 500
shares of its Coca-Cola stock for $50.04 per
share, less a $20 brokerage commission.
Sales Proceeds: (500 × $50.04) - $20 = $25,000
Cost Basis: 500 × $49 = $24,500
Gain on Sale: $25,000 - $24,500 = $500
7-19
Adjusting Marketable
Adjusting Marketable
Securities to Market Value
Securities to Market Value
On December 31, Foster Corporation’s remaining
shares of Coca-Cola capital stock have a current
market value of $47,000. Prior to any
adjustment, the company’s Marketable
Securities account has a balance of $49,000
(1,000 × $49 per share).
On December 31, Foster Corporation’s remaining
shares of Coca-Cola capital stock have a current
market value of $47,000. Prior to any
adjustment, the company’s Marketable
Securities account has a balance of $49,000
(1,000 × $49 per share).
Unrealized Loss: $47,000 - $49,000 = ($2,000)
7-20
Reflecting Uncollectible
Reflecting Uncollectible
Accounts in the Financial
Accounts in the Financial
Statements
Statements
At the end of each period, record an
estimate of the uncollectible
accounts.
At the end of each period, record an
estimate of the uncollectible
accounts.
Contra-asset account
Contra-asset account
Selling expense
Selling expense
7-21
The Allowance for Doubtful
The Allowance for Doubtful
Accounts
Accounts
The net realizable value is the
amount of accounts receivable that
the business expects to collect.
Accounts receivable
Less: Allowance for doubtful accounts
Net realizable value of accounts receivable
7-22
Writing Off an Uncollectible
Writing Off an Uncollectible
Account Receivable
Account Receivable
When an account is determined to be
uncollectible, it no longer qualifies
as an asset and should be written
off.
When an account is determined to be
uncollectible, it no longer qualifies
as an asset and should be written
off.
7-23
Before
Write-Off
After
Write-Off
Accounts receivable
$ 10,000
9,500
$
Less: Allow. for doubtful accts.
2,500
2,000
Net realizable value
$ 7,500
7,500
$
Notice that the $500 write-off did not change
the net realizable value nor did it affect any
income statement accounts.
Writing Off an Uncollectible
Writing Off an Uncollectible
Account Receivable
Account Receivable
7-24
Monthly Estimates of Credit
Monthly Estimates of Credit
Losses
Losses
At the end of each
month, management
should estimate the
probable amount of
uncollectible accounts
and adjust the
Allowance for Doubtful
Accounts to this new
estimate.
At the end of each
month, management
should estimate the
probable amount of
uncollectible accounts
and adjust the
Allowance for Doubtful
Accounts to this new
estimate.
Two Approaches to Estimating
Credit Losses:
1.
Balance Sheet Approach
2.
Income Statement Approach
7-25
Estimating Credit Losses —
Estimating Credit Losses —
The Balance Sheet Approach
The Balance Sheet Approach
Year-end Accounts Receivable is
broken down into age
classifications.
Year-end Accounts Receivable is
broken down into age
classifications.
Each age grouping has a
different likelihood of being
uncollectible.
Each age grouping has a
different likelihood of being
uncollectible.
Compute a separate allowance for
each age grouping.
Compute a separate allowance for
each age grouping.
7-26
Estimating Credit Losses —
Estimating Credit Losses —
The Balance Sheet Approach
The Balance Sheet Approach
At December 31, the receivables for EastCo,
Inc. were categorized as follows:
7-27
EastCo’s unadjusted
balance in the allowance
account is $500.
Per the previous
computation, the desired
balance is $1,350.
EastCo’s unadjusted
balance in the allowance
account is $500.
Per the previous
computation, the desired
balance is $1,350.
Estimating Credit Losses —
Estimating Credit Losses —
The Balance Sheet Approach
The Balance Sheet Approach
7-28
Estimating Credit Losses —
Estimating Credit Losses —
The Income Statement
The Income Statement
Approach
Approach
Net Credit Sales
% Estimated Uncollectible
Amount of Journal Entry
Net Credit Sales
% Estimated Uncollectible
Amount of Journal Entry
Uncollectible accounts’ percentage is based
on actual uncollectible accounts from prior
years’ credit sales.
7-29
Estimating Credit Losses —
Estimating Credit Losses —
The Income Statement
The Income Statement
Approach
Approach
In 2009, EastCo had credit sales of
$60,000. Historically, 1% of EastCo’s
credit sales has been uncollectible. For
2009, the estimate of uncollectible
accounts expense is $600.
($60,000 × .01 = $600)
In 2009, EastCo had credit sales of
$60,000. Historically, 1% of EastCo’s
credit sales has been uncollectible. For
2009, the estimate of uncollectible
accounts expense is $600.
($60,000 × .01 = $600)
7-30
Recovery of an Account
Recovery of an Account
Receivable Previously Written
Receivable Previously Written
Off
Off
Subsequent collections require that
the original write-off entry be reversed
before the cash collection is recorded.
Subsequent collections require that
the original write-off entry be reversed
before the cash collection is recorded.
GENERAL JOURNAL
Date
Account Titles and Explanation
P
R Debit
Credit
Accounts Receivable (X Customer)
$$$$
Allowance for Doubtful Accounts
$$$$
Cash
$$$$
Accounts Receivable (X Customer)
$$$$
7-31
Direct Write-Off Method
Direct Write-Off Method
This method makes no attempt to
match revenues with the expense of
uncollectible accounts.
7-32
Internal Controls for
Internal Controls for
Receivables
Receivables
Maintenance of the accounts receivable
subsidiary ledger.
Custody of cash receipts.
Authorization of accounts receivable write-
offs.
Maintenance of the accounts receivable
subsidiary ledger.
Custody of cash receipts.
Authorization of accounts receivable write-
offs.
Separate the following duties:
7-33
Management of Accounts
Management of Accounts
Receivable
Receivable
Extending credit encourages customers to
buy from us but it ties up resources in
accounts receivable.
Factoring
Accounts
Receivable
Credit Card
Sales
7-34
A promissory note is an unconditional
promise in writing to pay on demand or at
a future date a definite sum of money.
A promissory note is an unconditional
promise in writing to pay on demand or at
a future date a definite sum of money.
Notes Receivable and
Notes Receivable and
Interest Revenue
Interest Revenue
Maker—the person who
signs the note and
thereby promises to pay.
Payee—the person to
whom payment is to be
made.
Maker—the person who
signs the note and
thereby promises to pay.
Payee—the person to
whom payment is to be
made.
7-35
Notes Receivable and
Notes Receivable and
Interest Revenue
Interest Revenue
The interest formula includes
three variables:
The interest formula includes
three variables:
Interest = Principal × Interest Rate × Time
When computing interest for one year, “Time”
equals 1. When the computation period is less
than one year, then “Time” is a fraction.
When computing interest for one year, “Time”
equals 1. When the computation period is less
than one year, then “Time” is a fraction.
For example, if we needed to compute interest for
3 months, “Time” would be 3/12.
For example, if we needed to compute interest for
3 months, “Time” would be 3/12.
7-36
On November 1, Hall Company loans $10,000 to
Porter Company on a 90-day note earning 12
percent interest. On December 31st, Hall Company
needs an adjusting entry to record the interest
revenue on the Porter Company note.
On November 1, Hall Company loans $10,000 to
Porter Company on a 90-day note earning 12
percent interest. On December 31st, Hall Company
needs an adjusting entry to record the interest
revenue on the Porter Company note.
Notes Receivable and
Notes Receivable and
Interest Revenue
Interest Revenue
$10,00012% 60/360 =
$200
$10,00012% 60/360 =
$200
7-37
What entry would Hall Company
make on the maturity date?
What entry would Hall Company
make on the maturity date?
Notes Receivable and
Notes Receivable and
Interest Revenue
Interest Revenue
$10,00012% 90/360 =
$300
$10,00012% 90/360 =
$300
7-38
Financial Analysis and
Financial Analysis and
Decision Making
Decision Making
Accounts Receivable Turnover Rate
This ratio provides useful information for
evaluating how efficient management has
been in granting credit to produce
revenue.
Accounts Receivable Turnover Rate
This ratio provides useful information for
evaluating how efficient management has
been in granting credit to produce
revenue.
Net Sales
Average Accounts Receivable
7-39
Financial Analysis and
Financial Analysis and
Decision Making
Decision Making
Avg. Number of Days to Collect A/R
This ratio helps judge the liquidity of
a company’s accounts receivable.
Avg. Number of Days to Collect A/R
This ratio helps judge the liquidity of
a company’s accounts receivable.
Days in Year
Accounts Receivable Turnover Ratio
7-40
End of Chapter 7
End of Chapter 7