
ACO 201 Chapter 5, Spring 2013
Notre Dame University–Louaize · Principles of Accounting I · 25 pages





Showing the first 10 of 25 pages. Download the PDF to see all of it.
More ACO 201 files
- Chapter 1 · Spring 2013ChapterView
- Chapter 2 · Spring 2013ChapterView
- Chapter 3 · Spring 2013ChapterView
- Chapter 4 · Spring 2013ChapterView
- Chapter 6 · Spring 2013ChapterView
- Chapter 7 · Spring 2013ChapterView
- Problems Chapter 2 Solution · Spring 2013Chapter · with solutionView
- Problems Chapter 3 Solution · Spring 2013Chapter · with solutionView
Show the text of this chapter
Copyright © 2010 by The McGraw-Hill Companies, Inc. All rights reserved.
McGraw-Hill/Irwin
The Accounting Cycle:
The Accounting Cycle:
Reporting Financial Results
Reporting Financial Results
Chapter 5
McGraw-Hill/Irwin
5-2
Preparing Financial
Preparing Financial
Statements
Statements
Publicly owned companies – those with shares listed
on a stock exchange – have obligations to release
annual and quarterly information to their
stockholders and to the public.
Publicly owned companies – those with shares listed
on a stock exchange – have obligations to release
annual and quarterly information to their
stockholders and to the public.
The annual report includes comparative financial
statements and other information relating to the
company’s financial position, business operations, and
future prospects.
The financial statements contained in the annual
report must be audited by a firm of certified public
accountants (CPAs).
McGraw-Hill/Irwin
5-3
JJ's Lawn Care Service
Adjusted Trial Balance
May 31, 2009
Cash
3,925
$
Accounts receivable
75
Tools & equipment
2,650
Accumulated depreciation: tools &
equipment
50
$
Truck
15,000
Accumumlated depreciation: truck
250
Notes payable
13,000
Accounts payable
150
Capital stock
8,000
Dividends
200
Sales revenue
750
Gasoline expense
50
Depreciation expense: tools & equipment
50
Depreciation expense: truck
250
Total
22,200
$
22,200
$
Now, let’s prepare the financial statements for
JJ’s Lawn Care Service for May.
Now, let’s prepare the financial statements for
JJ’s Lawn Care Service for May.
5-4
JJ's Lawn Care Service
Income Statement
For the month ending May 31, 2009
Sales revenue
750
$
Operating expenses:
Gasoline expense
50
$
Depreciation: tools & equipment
50
Depreciation: truck
250
350
Net income
400
$
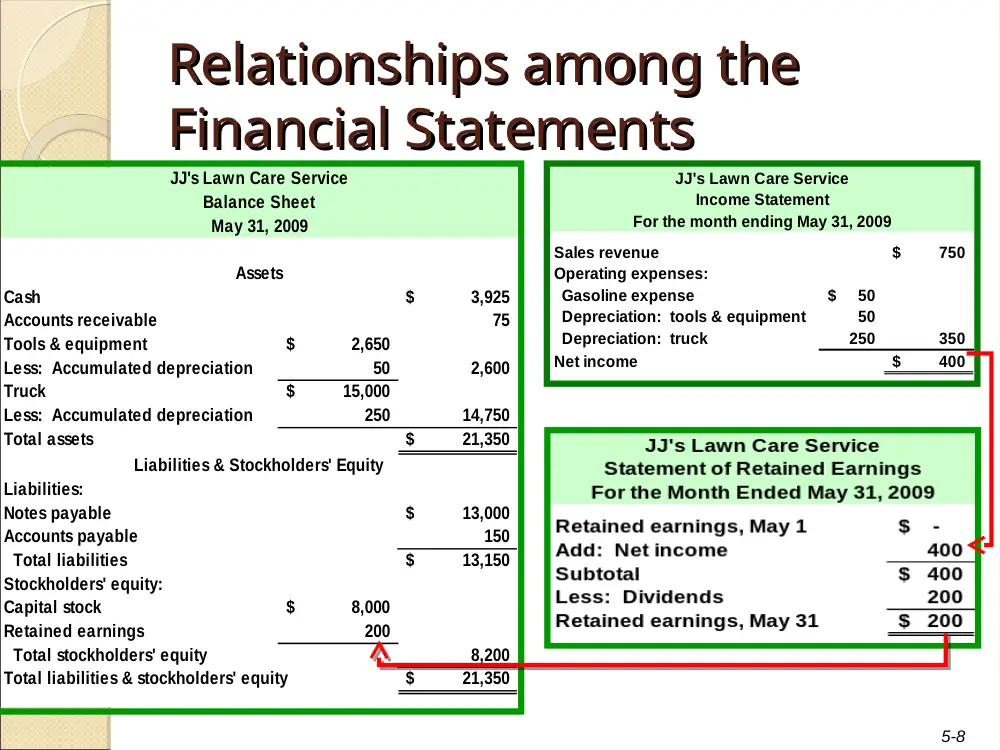
Net income also appears on the
Statement of Retained Earnings.
Net income also appears on the
Statement of Retained Earnings.
The Income Statement
The Income Statement
5-5
Business
Earnings
Dividends
Business
Losses
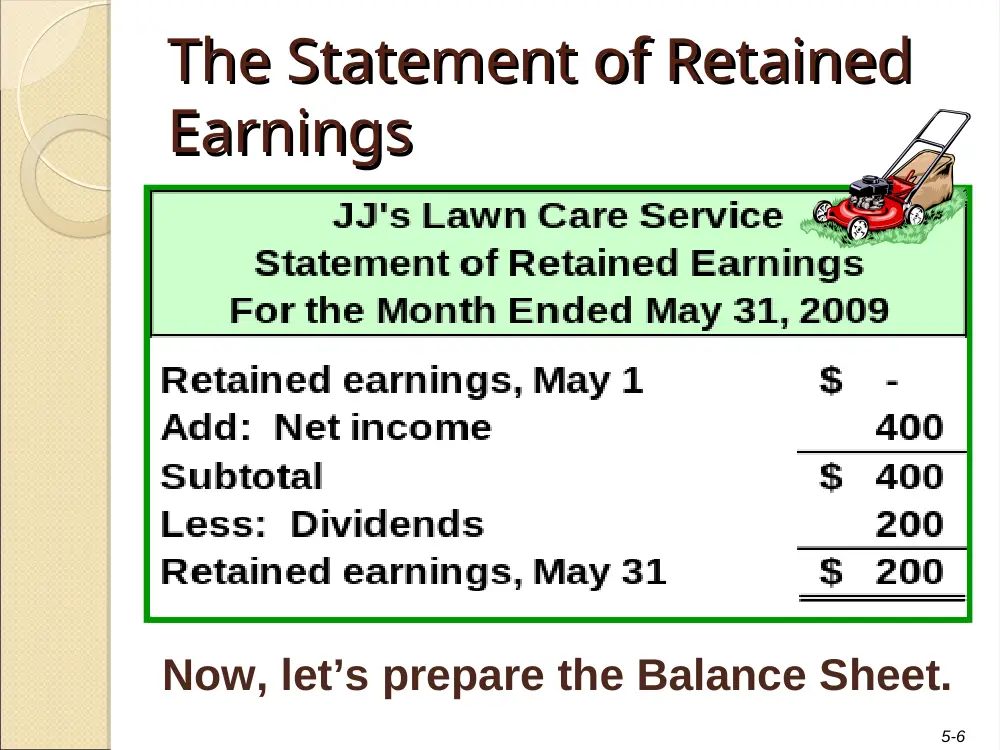
Summarizes the increases and decreases in
Retained Earnings during the period.
The Statement of Retained
The Statement of Retained
Earnings
Earnings
5-6
Now, let’s prepare the Balance Sheet.
The Statement of Retained
The Statement of Retained
Earnings
Earnings
5-7
JJ's Lawn Care Service
Balance Sheet
May 31, 2009
Assets
Cash
3,925
$
Accounts receivable
75
Tools & equipment
2,650
$
Less: Accumulated depreciation
50
2,600
Truck
15,000
$
Less: Accumulated depreciation
250
14,750
Total assets
21,350
$
Liabilities & Stockholders' Equity
Liabilities:
Notes payable
13,000
$
Accounts payable
150
Total liabilities
13,150
$
Stockholders' equity:
Capital stock
8,000
$
Retained earnings
200
Total stockholders' equity
8,200
Total liabilities & stockholders' equity
21,350
$
The Balance Sheet
The Balance Sheet
5-8
Relationships among the
Relationships among the
Financial Statements
Financial Statements
JJ's Lawn Care Service
Income Statement
For the month ending May 31, 2009
Sales revenue
750
$
Operating expenses:
Gasoline expense
50
$
Depreciation: tools & equipment
50
Depreciation: truck
250
350
Net income
$ 400
JJ's Lawn Care Service
Balance Sheet
May 31, 2009
Assets
Cash
3,925
$
Accounts receivable
75
Tools & equipment
2,650
$
Less: Accumulated depreciation
50
2,600
Truck
15,000
$
Less: Accumulated depreciation
250
14,750
Total assets
21,350
$
Liabilities & Stockholders' Equity
Liabilities:
Notes payable
13,000
$
Accounts payable
150
Total liabilities
13,150
$
Stockholders' equity:
Capital stock
8,000
$
Retained earnings
200
Total stockholders' equity
8,200
Total liabilities & stockholders' equity
21,350
$
5-9
Notes to the
Financial Statements
Examples of Items Disclosed
Lawsuits pending
Scheduled plant closings
Governmental investigations
Significant events occurring
after the balance sheet date
Specific customers that
account for a large portion of
revenue
Unusual transactions and
related party transactions
Examples of Items Disclosed
Lawsuits pending
Scheduled plant closings
Governmental investigations
Significant events occurring
after the balance sheet date
Specific customers that
account for a large portion of
revenue
Unusual transactions and
related party transactions
Drafting the Notes that
Drafting the Notes that
Accompany Financial
Accompany Financial
Statements
Statements
McGraw-Hill/Irwin
5-10
Closing the Temporary
Closing the Temporary
Accounts
Accounts
Close Revenue accounts
to Income Summary.
Close Expense accounts
to Income Summary.
Close Income Summary
account to Retained
Earnings.
Close Dividends to
Retained Earnings.
The closing process
gets the temporary
accounts ready for the
next accounting
period.
McGraw-Hill/Irwin
5-11
JJ's Lawn Care Service
Adjusted Trial Balance
May 31, 2009
Cash
3,925
$
Accounts receivable
75
Tools & equipment
2,650
Accum. depreciation: tools & eq.
50
$
Truck
15,000
Accum. depreciation: truck
250
Notes payable
13,000
Accounts payable
150
Capital stock
8,000
Dividends
200
Sales revenue
750
Gasoline expense
50
Depreciation exp.: tools & eq.
50
Depreciation exp.: truck
250
Total
22,200
$
22,200
$
Closing the Temporary
Closing the Temporary
Accounts
Accounts
5-12
GENERAL JOURNAL
Date
Account Titles and Explanation
P
RDebit
Credit
May 31 Sales Reveune
750
Income Summary
750
To close the revenue account.
Since Sales Revenue has a credit balance,
the closing entry requires a debit to the Sales
Revenue account.
Since Sales Revenue has a credit balance,
the closing entry requires a debit to the Sales
Revenue account.
Closing Entries for Revenue
Closing Entries for Revenue
Accounts
Accounts
5-13
Income Summary
750
750
Sales Revenue
750
750
-
Closing Entries for Revenue
Closing Entries for Revenue
Accounts
Accounts
5-14
GENERAL JOURNAL
Date
Account Titles and Explanation
P
RDebit
Credit
May 31 Income Summary
350
Gasoline Expense
50
Depreciation Exp.: Tools & Equipment
50
Depreciation Exp.: Truck
250
To close the expense accounts.
Since expense accounts have a debit
balance, the closing entry requires a credit to
the expense accounts.
Since expense accounts have a debit
balance, the closing entry requires a credit to
the expense accounts.
Closing Entries for Expense
Closing Entries for Expense
Accounts
Accounts
5-15
Closing Entries for Expense
Closing Entries for Expense
Accounts
Accounts
Income Summary
350
750
400
Net Income
Gasoline Exp.
50
50
-
Depr. Exp.: Truck
250
250
-
Depr. Exp.: Tools &
Equipment
50
50
-
5-16
Since Income Summary has a $400 credit
balance, the closing entry requires a debit to
Income Summary.
Since Income Summary has a $400 credit
balance, the closing entry requires a debit to
Income Summary.
GENERAL JOURNAL
Date
Account Titles and Explanation
P
RDebit Credit
May 31 Income Summary
400
Retained Earnings
400
To close Income Summary.
Closing the Income
Closing the Income
Summary Account
Summary Account
5-17
Retained Earnings
400
400
Income Summary
350
750
400
-
The balance in Income
Summary is now zero.
Closing the Income
Closing the Income
Summary Account
Summary Account
McGraw-Hill/Irwin
5-18
Since the Dividends account has a debit
balance, the closing entry requires a credit to
the Dividends account.
Since the Dividends account has a debit
balance, the closing entry requires a credit to
the Dividends account.
GENERAL JOURNAL
Date
Account Titles and Explanation
P
RDebit Credit
May 31 Retained Earnings
200
Dividends
200
To close the Dividends account.
Closing the Dividends
Closing the Dividends
Account
Account
McGraw-Hill/Irwin
5-19
Closing the Dividends
Closing the Dividends
Account
Account
Retained Earnings
200
400
200
Dividends
200
200
-
5-20
JJ's Lawn Care Service
After-Closing Trial Balance
May 31, 2009
Cash
3,925
$
Accounts receivable
75
Tools & equipment
2,650
Accum. depreciation: tools & eq.
50
$
Truck
15,000
Accum. depreciation: truck
250
Notes payable
13,000
Accounts payable
150
Capital stock
8,000
Retained earnings
200
Total
$ 21,650
21,650
$
After-Closing Trial Balance
After-Closing Trial Balance
5-21
Evaluating
Profitability
Evaluating
Profitability
Evaluating
Liquidity
Evaluating
Liquidity
Evaluating the Business
Evaluating the Business
Net Income
Percentage
Net Income
Total Revenue
=
Return on
Equity
Net Income
Avg. Stockholders’
Equity
=
Current
Ratio
Current Assets
Current Liabilities
=
Working
Capital
Current Assets –
= Current Liabilities
5-22
Monthly
Quarterly
Jan. 1
Dec. 31
Annually
Many companies prepare financial
statements at various points throughout
the year.
Many companies prepare financial
statements at various points throughout
the year.
Interim
Financial
Statements
Preparing Financial
Preparing Financial
Statements Covering Different
Statements Covering Different
Periods of Time
Periods of Time
5-23
Ethics, Fraud, and
Ethics, Fraud, and
Corporate Governance
Corporate Governance
A company should disclose any facts that an
intelligent person would consider necessary for
the statements to be interpreted properly.
Public companies are required to file annual
reports with the Securities and Exchange
Commission (SEC). The SEC requires that
companies include a section labeled
“Management Discussion and Analysis” (MD&A)
because the financial statements and related
notes may be inadequate for assessing the
quantity and sustainability of a company’s
earnings.
5-24
Supplemental Topic: The
Supplemental Topic: The
Worksheet
Worksheet
Balance Sheet Accounts
Dr
Cr
Dr
Cr
Dr
Cr
Dr
Cr
Dr
Cr
Cash
18,592
18,592
18,592
Accounts Receivable
6,500
(h)
750
7,250
7,250
Shop Supplies
1,800
(a)
600
1,200
1,200
Notes Payable
4,000
4,000
4,000
Accounts Payable
2,690
2,690
2,690
Income Statement Accounts
Repair Service Revenue
171,250
(h)
750
172,000
172,000
Advertising Expense
3,900
3,900
3,900
Wages Expense
56,800
(f)
1,950
58,750
58,750
272,000
272,000
12,200
12,200
279,100
279,100
135,058
175,000
144,042
104,100
Net Income
39,942
39,942
Totals
175,000
175,000
144,042
144,042
OVERNIGHT AUTO SERVICES
Worksheet
For the Year Ended December 31, 2009
Trial Balance
Adjustments
Adjusted Trial
Balance
Income Statement
Balance Sheet
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .. . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . . .
5-25
End of Chapter 5
End of Chapter 5