
ACCT 215 Final, Fall 2004
American University of Beirut · Management Accounting · 3 pages

More ACCT 215 files
- Syllabus · Spring 2012LabView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
Show the text of this final exam
AMERICAN UNIVERSIT
LIBRARY |
OF PLIRUT
American University of Beirut
Olayan School of Business
Final Exam — ACCT 215
Time: 2 hrs. January 19, 2005
Multiple Choice: 20 points
5 Rit
1. The following sales budget has been prepared:
Month Cash Sales Credit Sales
September $100,000 $200,000 6:
October 125,000 180,000 4 RPO
November 130,000 210,000 ®¢,,03-
December 135,000 190,000
Collections of credit sales are 50. percent in the month of sale, 40 percent in the
month following the sale, and !0 percent two months following the sale. No oc
uncollectible accounts are anticipated. B30
Casn cate» Go
What is the expected balance of Accounts Receivable as of October 31? PLEO
“a. $110,000 = 24 ee
b. $180,000
c. $118,000
d. $72,500
2. Preparing the master budget begins by establishing
a. a targeted balance sheet.
b. a targeted income statement.
c. the expected cash.
~pd. the expected sales.
3. A major drawback of using historical results for judging current performance is that
a. past results may be incorrect.
b. results may refer to a different manager.
c. inefficiencies maybe concealed in the past performance.
-p d. all of the above. ;
a
4. The master budget typically includes forecasted amounts for all of the following EXCEPT
a. sales.
~Wb. number of employees.
c. balance sheets.
d..-cash disbursements.
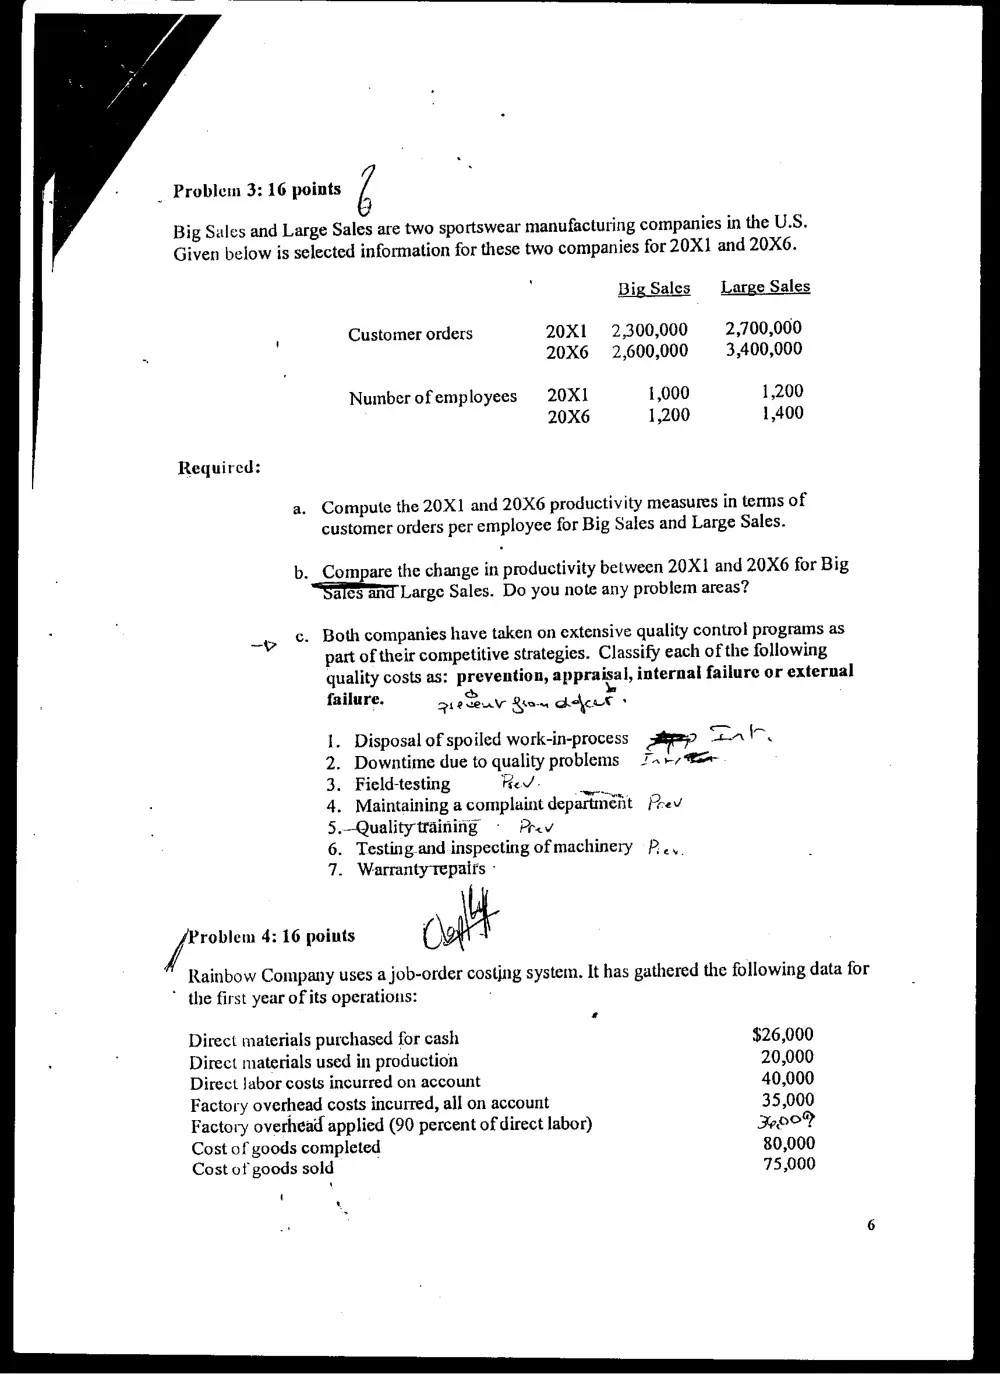
_ Problem 3: 16 points i
Big Sales and Large Sales are two sportswear manufacturing companies in the U.S.
Given below is selected information for these two companies for 20X1 and 20X6.
BigSales Large Sales
Customer orders 20X1 2,300,000 2,700,000
20X6 2,600,000 3,400,000
Number ofemployees 20X1 1,000 1,200
20X6 1,200 1,400
Required:
a. Compute the 20X1 and 20X6 productivity measures in terms of
customer orders per employee for Big Sales and Large Sales.
b. Compare the change in productivity between 20X1 and 20X6 for Big
Sales and Large Sales. Do you note any problem areas?
-p & Both companies have taken on extensive quality control programs as
part of their competitive strategies. Classify each of the following
quality costs as: prevention, appraisal, internal failure or external
failure. 36 ecu Reon Adc :
1. Disposal of spoiled work-in-process AFP aan
2. Downtime due to quality problems 74+,
3. Field-testing Rev-
4. Maintaining a complaint department Prev
5.—Quality raining ~ Prev
6. Testing.and.inspecting ofmachinery =P. .y.
7. Warranty Tepaits -
roblem 4: 16 points 0
Rainbow Company uses a job-order costjng system. It has gathered the following data for
* the first year of its operations: ;
Direct materials purchased for cash $26,000
Direct materials used in production 20,000
Direct Jabor costs incurred on account 40,000
Factory overhead costs incurred, all on account 35,000
Factory overhead applied (90 percent of direct labor) HOY
Cost of goods completed 80,000
Cost of goods sold 75,000
‘
©
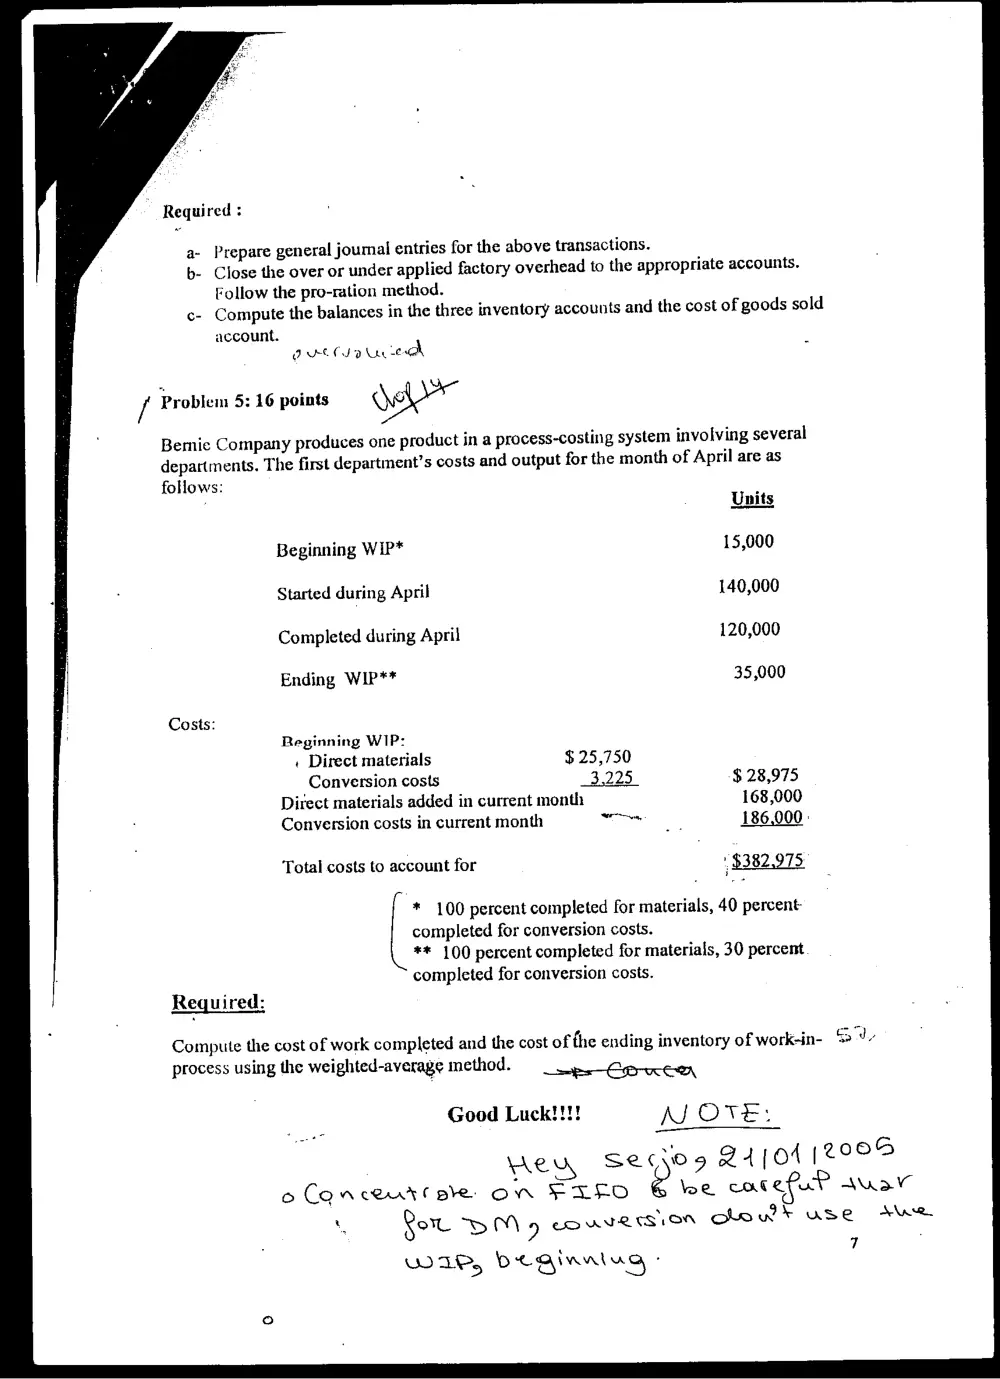
Required :
Prepare general joumal entries for the above transactions.
Close the over or under applied factory overhead to the appropriate accounts.
Follow the pro-ration method.
Compute the balances in the three inventory accounts and the cost of goods sold
account.
Ore sa eo
/ Problem 5: 16 points Oder
Bemic Company produces one product in a process-costing system involving several
departments. The first department’s costs and output for the month of April are as
follows:
Beginning WIP*
Started during April 140,000
Completed during April 120,000
Ending WIP** 35,000
Beginning WIP:
+ Direct materials $25,750
Conversion costs 3,225 $ 28,975
Direct materials added in current month 168,000
Conversion costs in current month ae 186,000 -
Total costs to account for
$382,975
* 100 percent completed for materials, 40 percent
completed for conversion costs.
** 100 percent completed for materials, 30 percent
completed for conversion costs.
Required:
Compute the cost of work completed and the cost of the ending inventory of work-in- Sy
process using the weighted-average method. = _ ap pcan
Good Luck!!! AJ OVE:
ACY, Se 609 24104 (2008
o Cancer are On FTLO oe carer? AWS
‘. fo DM 9 CO AVR ES TON chew use Awe
WIP, DI Qinnlug . 7