
ACCT 215 Problems Solutions, Fall 2011
American University of Beirut · Management Accounting · 24 pages · with solution


Showing the first 10 of 24 pages. Download the PDF to see all of it.
More ACCT 215 files
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
Show the text of this problems
Chapter 02 Managerial Accounting and Cost Concepts
Chapter 2
Managerial Accounting and Cost Concepts
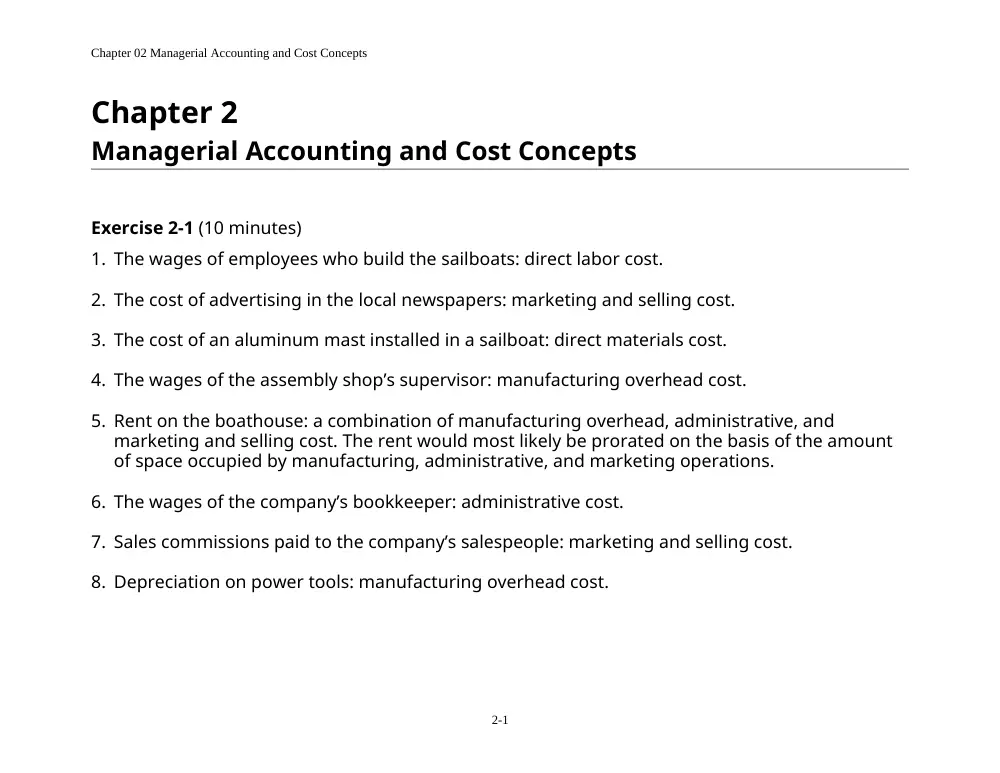
Exercise 2-1 (10 minutes)
1. The wages of employees who build the sailboats: direct labor cost.
2. The cost of advertising in the local newspapers: marketing and selling cost.
3. The cost of an aluminum mast installed in a sailboat: direct materials cost.
4. The wages of the assembly shop’s supervisor: manufacturing overhead cost.
5. Rent on the boathouse: a combination of manufacturing overhead, administrative, and
marketing and selling cost. The rent would most likely be prorated on the basis of the amount
of space occupied by manufacturing, administrative, and marketing operations.
6. The wages of the company’s bookkeeper: administrative cost.
7. Sales commissions paid to the company’s salespeople: marketing and selling cost.
8. Depreciation on power tools: manufacturing overhead cost.
2-1
Chapter 02 Managerial Accounting and Cost Concepts
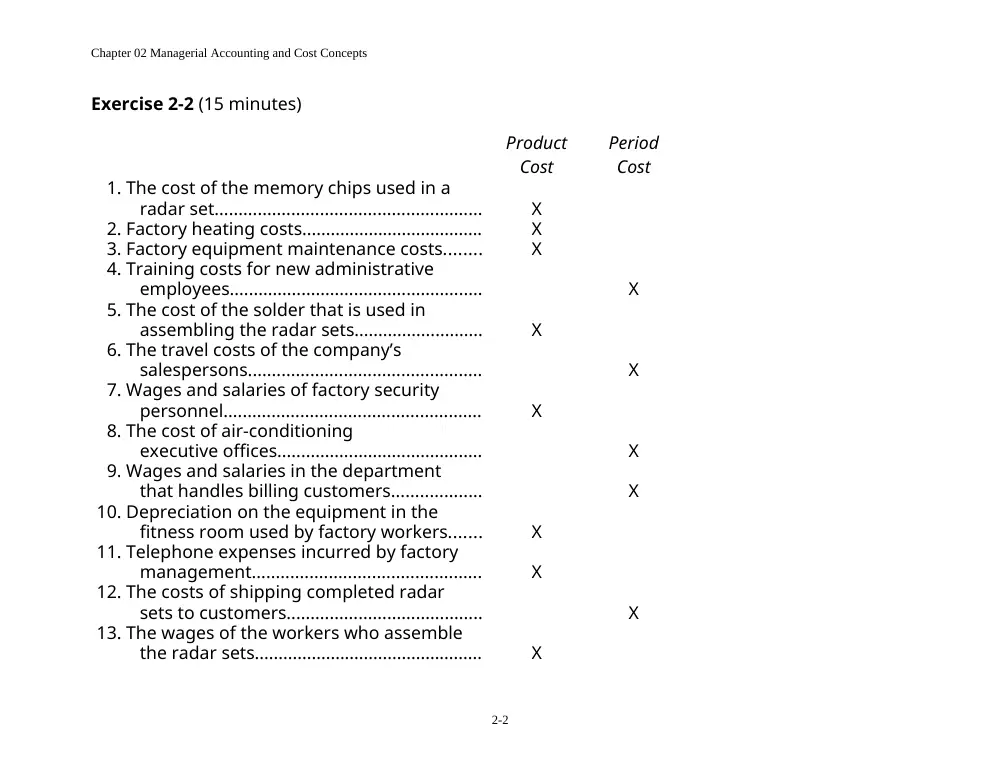
Exercise 2-2 (15 minutes)
Product
Cost
Period
Cost
1. The cost of the memory chips used in a
radar set........................................................
X
2. Factory heating costs......................................
X
3. Factory equipment maintenance costs........
X
4. Training costs for new administrative
employees.....................................................
X
5. The cost of the solder that is used in
assembling the radar sets...........................
X
6. The travel costs of the company’s
salespersons.................................................
X
7. Wages and salaries of factory security
personnel......................................................
X
8. The cost of air-conditioning
executive offices...........................................
X
9. Wages and salaries in the department
that handles billing customers...................
X
10. Depreciation on the equipment in the
fitness room used by factory workers.......
X
11. Telephone expenses incurred by factory
management................................................
X
12. The costs of shipping completed radar
sets to customers.........................................
X
13. The wages of the workers who assemble
the radar sets................................................
X
2-2
Chapter 02 Managerial Accounting and Cost Concepts
14. The president’s salary.....................................
X
15. Health insurance premiums for factory
personnel......................................................
X
2-3
Chapter 02 Managerial Accounting and Cost Concepts
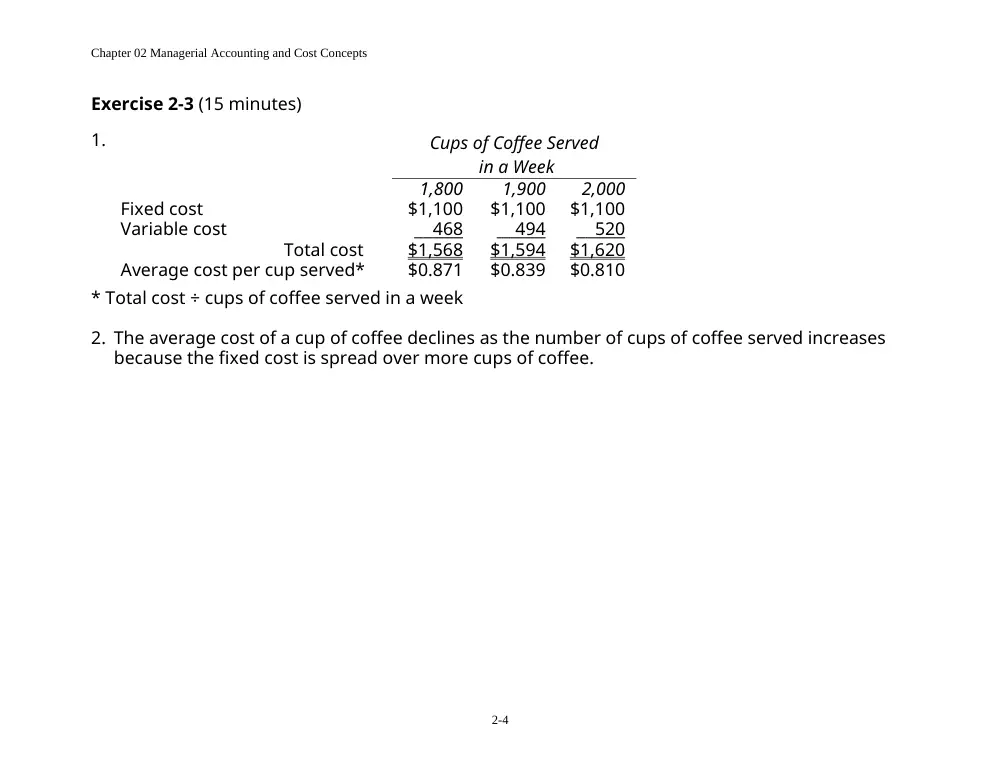
Exercise 2-3 (15 minutes)
1.
Cups of Coffee Served
in a Week
1,800
1,900
2,000
Fixed cost
$1,100
$1,100
$1,100
Variable cost
468
494
520
Total cost
$1,568
$1,594
$1,620
Average cost per cup served*
$0.871
$0.839
$0.810
* Total cost ÷ cups of coffee served in a week
2. The average cost of a cup of coffee declines as the number of cups of coffee served increases
because the fixed cost is spread over more cups of coffee.
2-4
Chapter 02 Managerial Accounting and Cost Concepts
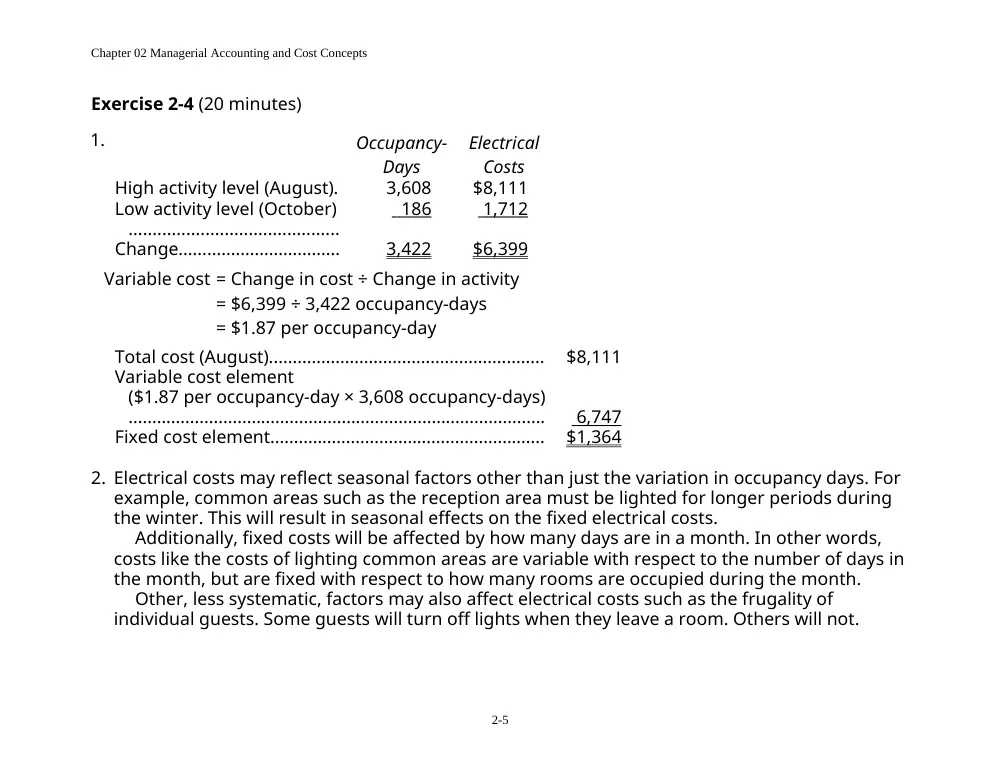
Exercise 2-4 (20 minutes)
1.
Occupancy-
Days
Electrical
Costs
High activity level (August).
3,608
$8,111
Low activity level (October)
............................................
186
1,712
Change..................................
3,422
$6,399
Variable cost = Change in cost ÷ Change in activity
= $6,399 ÷ 3,422 occupancy-days
= $1.87 per occupancy-day
Total cost (August)..........................................................
$8,111
Variable cost element
($1.87 per occupancy-day × 3,608 occupancy-days)
........................................................................................
6,747
Fixed cost element..........................................................
$1,364
2. Electrical costs may reflect seasonal factors other than just the variation in occupancy days. For
example, common areas such as the reception area must be lighted for longer periods during
the winter. This will result in seasonal effects on the fixed electrical costs.
Additionally, fixed costs will be affected by how many days are in a month. In other words,
costs like the costs of lighting common areas are variable with respect to the number of days in
the month, but are fixed with respect to how many rooms are occupied during the month.
Other, less systematic, factors may also affect electrical costs such as the frugality of
individual guests. Some guests will turn off lights when they leave a room. Others will not.
2-5
Chapter 02 Managerial Accounting and Cost Concepts
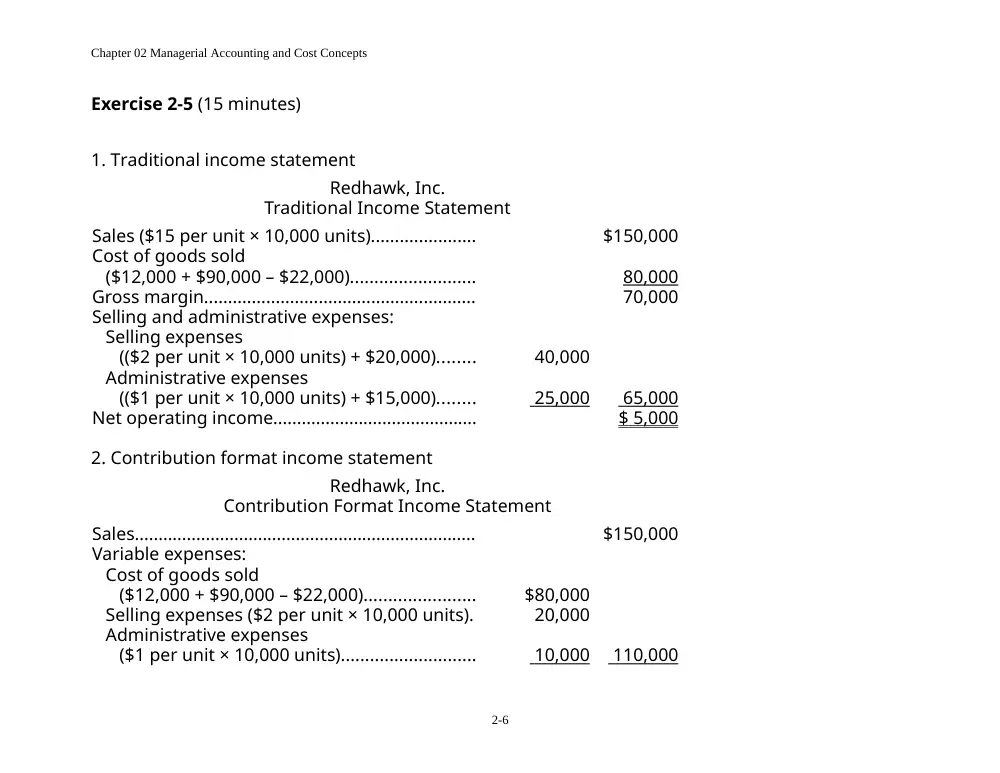
Exercise 2-5 (15 minutes)
1. Traditional income statement
Redhawk, Inc.
Traditional Income Statement
Sales ($15 per unit × 10,000 units)......................
$150,000
Cost of goods sold
($12,000 + $90,000 – $22,000)..........................
80,000
Gross margin.........................................................
70,000
Selling and administrative expenses:
Selling expenses
(($2 per unit × 10,000 units) + $20,000)........
40,000
Administrative expenses
(($1 per unit × 10,000 units) + $15,000)........
25,000
65,000
Net operating income...........................................
$ 5,000
2. Contribution format income statement
Redhawk, Inc.
Contribution Format Income Statement
Sales........................................................................
$150,000
Variable expenses:
Cost of goods sold
($12,000 + $90,000 – $22,000).......................
$80,000
Selling expenses ($2 per unit × 10,000 units).
20,000
Administrative expenses
($1 per unit × 10,000 units)............................
10,000
110,000
2-6
Chapter 02 Managerial Accounting and Cost Concepts
Contribution margin.............................................
40,000
Fixed expenses:
Selling expenses.................................................
20,000
Administrative expenses...................................
15,000
35,000
Net operating income...........................................
$ 5,000
2-7
Chapter 02 Managerial Accounting and Cost Concepts
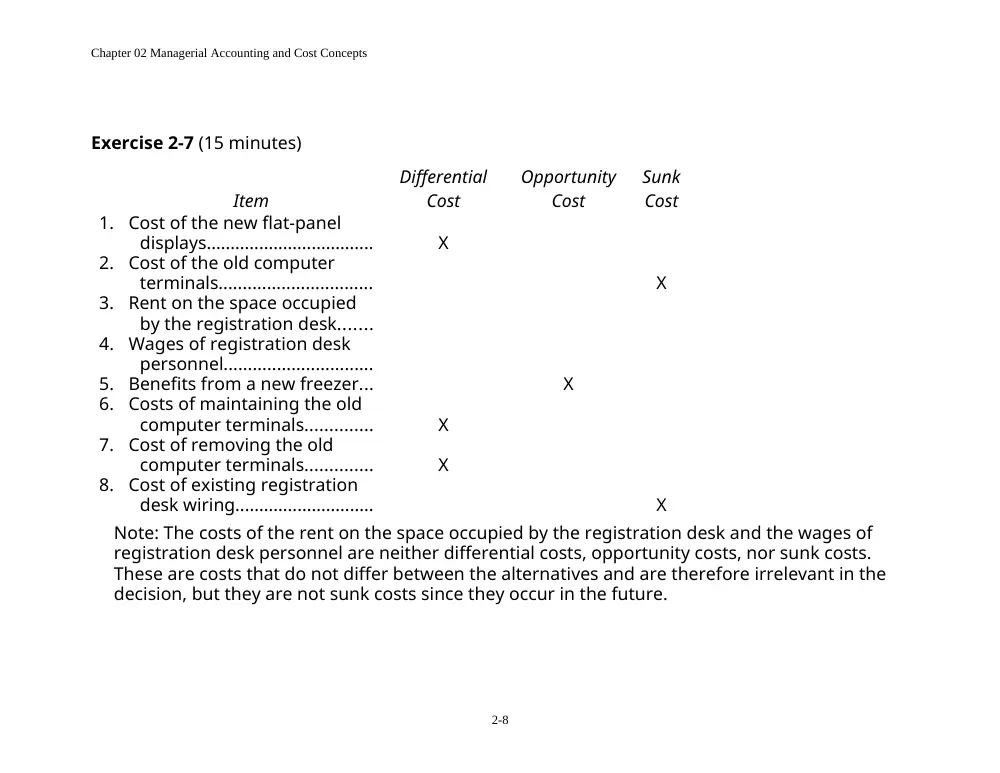
Exercise 2-7 (15 minutes)
Differential
Opportunity
Sunk
Item
Cost
Cost
Cost
1.
Cost of the new flat-panel
displays...................................
X
2.
Cost of the old computer
terminals................................
X
3.
Rent on the space occupied
by the registration desk.......
4.
Wages of registration desk
personnel...............................
5.
Benefits from a new freezer...
X
6.
Costs of maintaining the old
computer terminals..............
X
7.
Cost of removing the old
computer terminals..............
X
8.
Cost of existing registration
desk wiring.............................
X
Note: The costs of the rent on the space occupied by the registration desk and the wages of
registration desk personnel are neither differential costs, opportunity costs, nor sunk costs.
These are costs that do not differ between the alternatives and are therefore irrelevant in the
decision, but they are not sunk costs since they occur in the future.
2-8
Chapter 02 Managerial Accounting and Cost Concepts
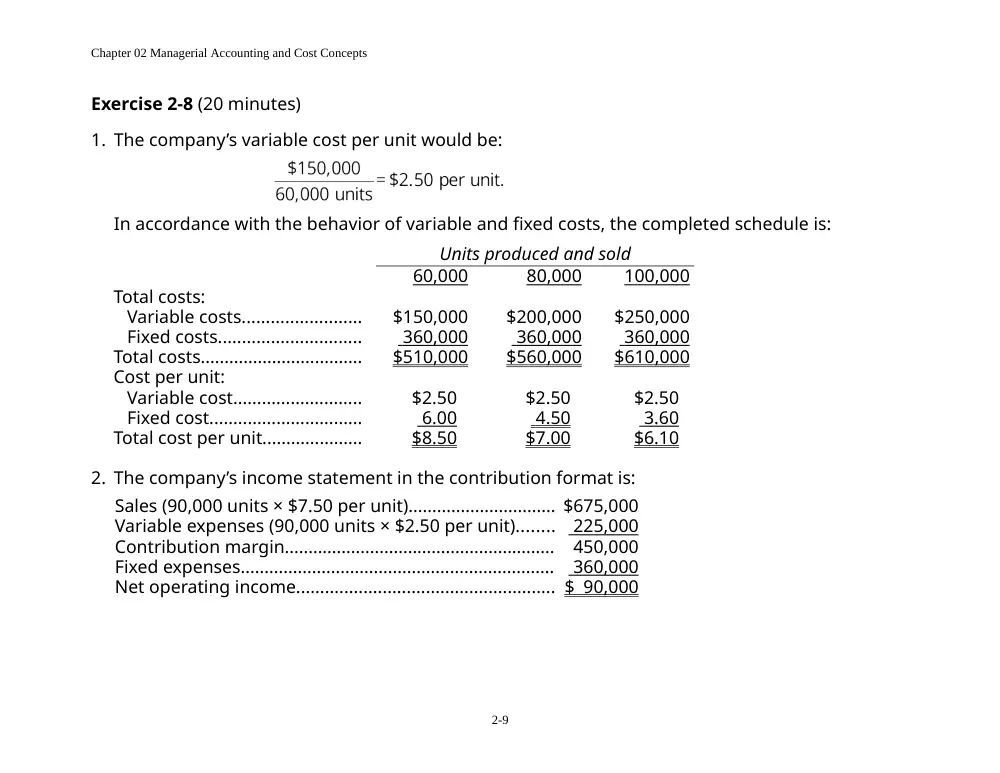
Exercise 2-8 (20 minutes)
1. The company’s variable cost per unit would be:
In accordance with the behavior of variable and fixed costs, the completed schedule is:
Units produced and sold
60,000
80,000
100,000
Total costs:
Variable costs.........................
$150,000
$200,000
$250,000
Fixed costs..............................
360,000
360,000
360,000
Total costs..................................
$510,000
$560,000
$610,000
Cost per unit:
Variable cost...........................
$2.50
$2.50
$2.50
Fixed cost................................
6.00
4.50
3.60
Total cost per unit.....................
$8.50
$7.00
$6.10
2. The company’s income statement in the contribution format is:
Sales (90,000 units × $7.50 per unit)............................... $675,000
Variable expenses (90,000 units × $2.50 per unit)........ 225,000
Contribution margin.........................................................
450,000
Fixed expenses..................................................................
360,000
Net operating income...................................................... $ 90,000
2-9
Chapter 02 Managerial Accounting and Cost Concepts
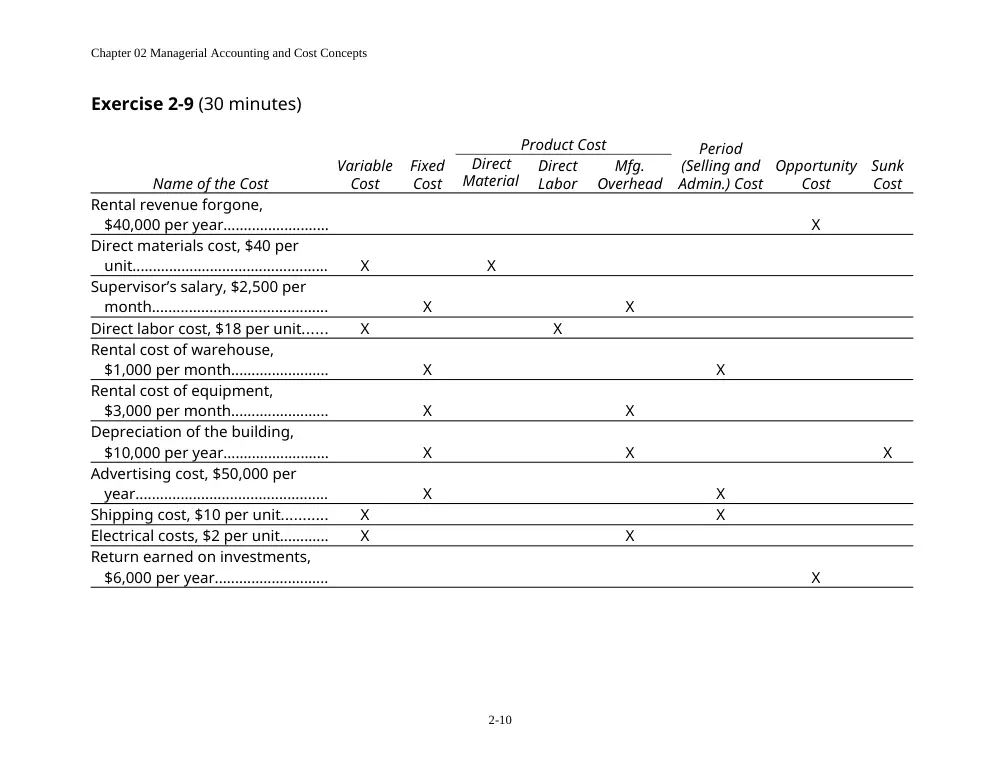
Exercise 2-9 (30 minutes)
Name of the Cost
Variable
Cost
Fixed
Cost
Product Cost
Period
(Selling and
Admin.) Cost
Opportunity
Cost
Sunk
Cost
Direct
Material
s
Direct
Labor
Mfg.
Overhead
Rental revenue forgone,
$40,000 per year..........................
X
Direct materials cost, $40 per
unit................................................
X
X
Supervisor’s salary, $2,500 per
month...........................................
X
X
Direct labor cost, $18 per unit......
X
X
Rental cost of warehouse,
$1,000 per month........................
X
X
Rental cost of equipment,
$3,000 per month........................
X
X
Depreciation of the building,
$10,000 per year..........................
X
X
X
Advertising cost, $50,000 per
year...............................................
X
X
Shipping cost, $10 per unit...........
X
X
Electrical costs, $2 per unit............
X
X
Return earned on investments,
$6,000 per year............................
X
2-10
Chapter 02 Managerial Accounting and Cost Concepts
Exercise 2-12 (20 minutes)
1.
Miles
Driven
Total
Annual
Cost*
High level of activity............
120,000 $13,920
Low level of activity.............
80,000
10,880
Change..................................
40,000
$ 3,040
* 120,000 miles × $0.116 per mile = $13,920
80,000 miles × $0.136 per mile = $10,880
Variable cost per mile:
Fixed cost per year:
Total cost at 120,000 miles......................................
$13,920
Less variable cost element:
120,000 miles × $0.076 per mile..........................
9,120
Fixed cost per year...................................................
$ 4,800
2. Y = $4,800 + $0.076X
3. Fixed cost.......................................................................
$ 4,800
Variable cost: 100,000 miles × $0.076 per mile........
7,600
Total annual cost..........................................................
$12,400
2-11
Chapter 02 Managerial Accounting and Cost Concepts
Problem 2-14 (45 minutes)
1.
House Of Organs, Inc.
Traditional Income Statement
For the Month Ended November 30
Sales (60 organs × $2,500 per organ).................
$150,000
Cost of goods sold
(60 organs × $1,500 per organ)........................
90,000
Gross margin.........................................................
60,000
Selling and administrative expenses:
Selling expenses:
Advertising.......................................................
$ 950
Delivery of organs
(60 organs × $60 per organ)........................
3,600
Sales salaries and commissions
[$4,800 + (4% × $150,000)]..........................
10,800
Utilities..............................................................
650
Depreciation of sales facilities.......................
5,000
Total selling expenses........................................
21,000
Administrative expenses:
Executive salaries............................................
13,500
Depreciation of office equipment.................
900
Clerical
[$2,500 + (60 organs × $40 per organ)].....
4,900
Insurance..........................................................
700
2-12
Chapter 02 Managerial Accounting and Cost Concepts
Total administrative expenses..........................
20,000
Total selling and administrative expenses.........
41,000
Net operating income...........................................
$ 19,000
Problem 2-14 (continued)
2.
House Of Organs, Inc.
Contribution Format Income Statement
For the Month Ended November 30
2-13
Chapter 02 Managerial Accounting and Cost Concepts
Total
Per Unit
Sales (60 organs × $2,500 per organ).................
$150,000
$2,500
Variable expenses:
Cost of goods sold
(60 organs × $1,500 per organ).....................
90,000
1,500
Delivery of organs
(60 organs × $60 per organ)..........................
3,600
60
Sales commissions (4% × $150,000).................
6,000
100
Clerical (60 organs × $40 per organ)................
2,400
40
Total variable expenses..................................
102,000
1,700
Contribution margin.............................................
48,000
$ 800
Fixed expenses:
Advertising..........................................................
950
Sales salaries.......................................................
4,800
Utilities.................................................................
650
Depreciation of sales facilities..........................
5,000
Executive salaries...............................................
13,500
Depreciation of office equipment....................
900
Clerical.................................................................
2,500
Insurance............................................................
700
Total fixed expenses.............................................
29,000
Net operating income...........................................
$ 19,000
3. Fixed costs remain constant in total but vary on a per unit basis with changes in the activity
level. For example, as the activity level increases, fixed costs decrease on a per unit basis.
Showing fixed costs on a per unit basis on the income statement make them appear to be
variable costs. That is, management might be misled into thinking that the per unit fixed costs
2-14
Chapter 02 Managerial Accounting and Cost Concepts
would be the same regardless of how many organs were sold during the month. For this
reason, fixed costs should be shown only in totals on a contribution-type income statement.
2-15
Chapter 02 Managerial Accounting and Cost Concepts
Problem 2-15 (30 minutes)
1.
a.
6
b.
11
c.
1
d.
4
e.
2
f.
10
g.
3
h.
7
i.
9
2. Without an understanding of the underlying cost behavior patterns, it would be difficult, if not
impossible for a manager to properly analyze the firm’s cost structure. The reason is that all
costs don’t behave in the same way. One cost might move in one direction as a result of a
particular action, and another cost might move in an opposite direction. Unless the behavior
pattern of each cost is clearly understood, the impact of a firm’s activities on its costs will not be
known until after the activity has occurred.
2-16
Chapter 02 Managerial Accounting and Cost Concepts
Problem 2-16 (20 minutes)
Direct or Indirect
Cost of the
Immunization
Center
Direct or Indirect
Cost of Particular
Patients
Variable or Fixed
with Respect to the
Number of
Immunizations
Administered
Item
Description
Direct
Indirect
Direct
Indirect
Variable
Fixed
a.
The salary of the head nurse in the
Immunization Center.........................................
X
X
X
b.
Costs of incidental supplies consumed in the
Immunization Center such as paper towels...
X
X
X
c.
The cost of lighting and heating the
Immunization Center.........................................
X
X
X
d.
The cost of disposable syringes used in the
Immunization Center.........................................
X
X
X
e.
The salary of the Central Area Well-Baby
Clinic’s Information Systems manager............
X
X
X
f.
The costs of mailing letters soliciting
donations to the Central Area Well-Baby
Clinic.....................................................................
X
X
X
g.
The wages of nurses who work in the
Immunization Center*.......................................
X
X
X
h.
The cost of medical malpractice insurance for
the Central Area Well-Baby Clinic.....................
X
X
X
2-17
Chapter 02 Managerial Accounting and Cost Concepts
i.
Depreciation on the fixtures and equipment
in the Immunization Center..............................
X
X
X
* The wages of the nurses could be variable and a direct cost of serving particular patients.
Problem 2-17 (30 minutes)
1. Maintenance cost at the 80,000 machine-hour level of activity can be isolated as follows:
Level of Activity
60,000 MH
80,000 MH
Total factory overhead
cost.....................................
274,000 pesos
312,000 pesos
Deduct:
Indirect materials @
1.50 pesos per MH*.......
90,000
120,000
Rent....................................
130,000
130,000
Maintenance cost................
54,000
pesos
62,000
pesos
* 90,000 pesos ÷ 60,000 MHs = 1.50 pesos per MH
2. High-low analysis of maintenance cost:
Machine-Hours
Maintenance Cost
High activity level..............
80,000
62,000 pesos
Low activity level................
60,000
54,000
Change observed..............
20,000
8,000
pesos
2-18
Chapter 02 Managerial Accounting and Cost Concepts
2-19
Chapter 02 Managerial Accounting and Cost Concepts
Fixed cost element:
Total cost at the high level of activity..................
54,000 Pesos
Less variable cost element
(60,000 MHs × 0.40 pesos per MH)...................
24,000
Fixed cost element................................................
30,000 Pesos
Therefore, the cost formula is 30,000 pesos per year, plus 0.40 peso per
2-20
Chapter 02 Managerial Accounting and Cost Concepts
machine-hour or
Y = 30,000 pesos + 0.40 peso X.
Problem 2-17 (continued)
3. Total factory overhead cost at 65,000 machine-hours is:
Indirect materials (65,000 MHs ×
1.50 pesos per MH).........................
97,500 pesos
Rent......................................................
130,000
Maintenance:
Variable cost element (65,000
MHs × 0.40 peso per MH)............
26,000 pesos
Fixed cost element..........................
30,000
56,000
Total factory overhead cost..............
283,500 pesos
2-21
Chapter 02 Managerial Accounting and Cost Concepts
Problem 2-18 (45 minutes)
1. Cost of goods sold..................... Variable
Shipping expense...................... Mixed
Advertising expense.................. Fixed
Salaries and commissions........ Mixed
Insurance expense.................... Fixed
Depreciation expense............... Fixed
2. Analysis of the mixed expenses:
Units
Shipping
Expense
Salaries and
Comm. Expense
High level of activity.....
4,500
£56,000
£143,000
Low level of activity......
3,000
44,000
107,000
Change...........................
1,500
£12,000
£ 36,000
Variable cost element:
Fixed cost element:
Shipping
Salaries and
2-22
Chapter 02 Managerial Accounting and Cost Concepts
Expense
Comm. Expense
Cost at high level of activity. .
£56,000
£143,000
Less variable cost element:
4,500 units × £8 per unit.....
36,000
4,500 units × £24 per unit...
108,000
Fixed cost element.................
£20,000
£ 35,000
The cost formulas are:
Shipping expense: £20,000 per month plus £8 per unit or
Y = £20,000 + £8X.
Salaries and Comm. expense: £35,000 per month plus £24 per unit or
Y = £35,000 + £24X.
3.
Frankel Ltd.
2-23
Chapter 02 Managerial Accounting and Cost Concepts
Income Statement
For the Month Ended June 30
Sales revenue.................................................
£630,000
Variable expenses:
Cost of goods sold
(4,500 units × £56 per unit).....................
£252,000
Shipping expense
(4,500 units × £8 per unit).......................
36,000
Salaries and commissions expense
(4,500 units × £24 per unit).....................
108,000
396,000
Contribution margin......................................
234,000
Fixed expenses:
Shipping expense........................................
20,000
Advertising...................................................
70,000
Salaries and commissions..........................
35,000
Insurance.....................................................
9,000
Depreciation................................................
42,000
176,000
Net operating income...................................
£ 58,000
2-24