
ACCT 215 Problems Solutions, Fall 2011
American University of Beirut · Management Accounting · 11 pages · with solution
Showing the first 10 of 11 pages. Download the PDF to see all of it.
More ACCT 215 files
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
Show the text of this problems
Chapter 09 Flexible Budgets and Performance Analysis
Chapter 9
Flexible Budgets and Performance Analysis
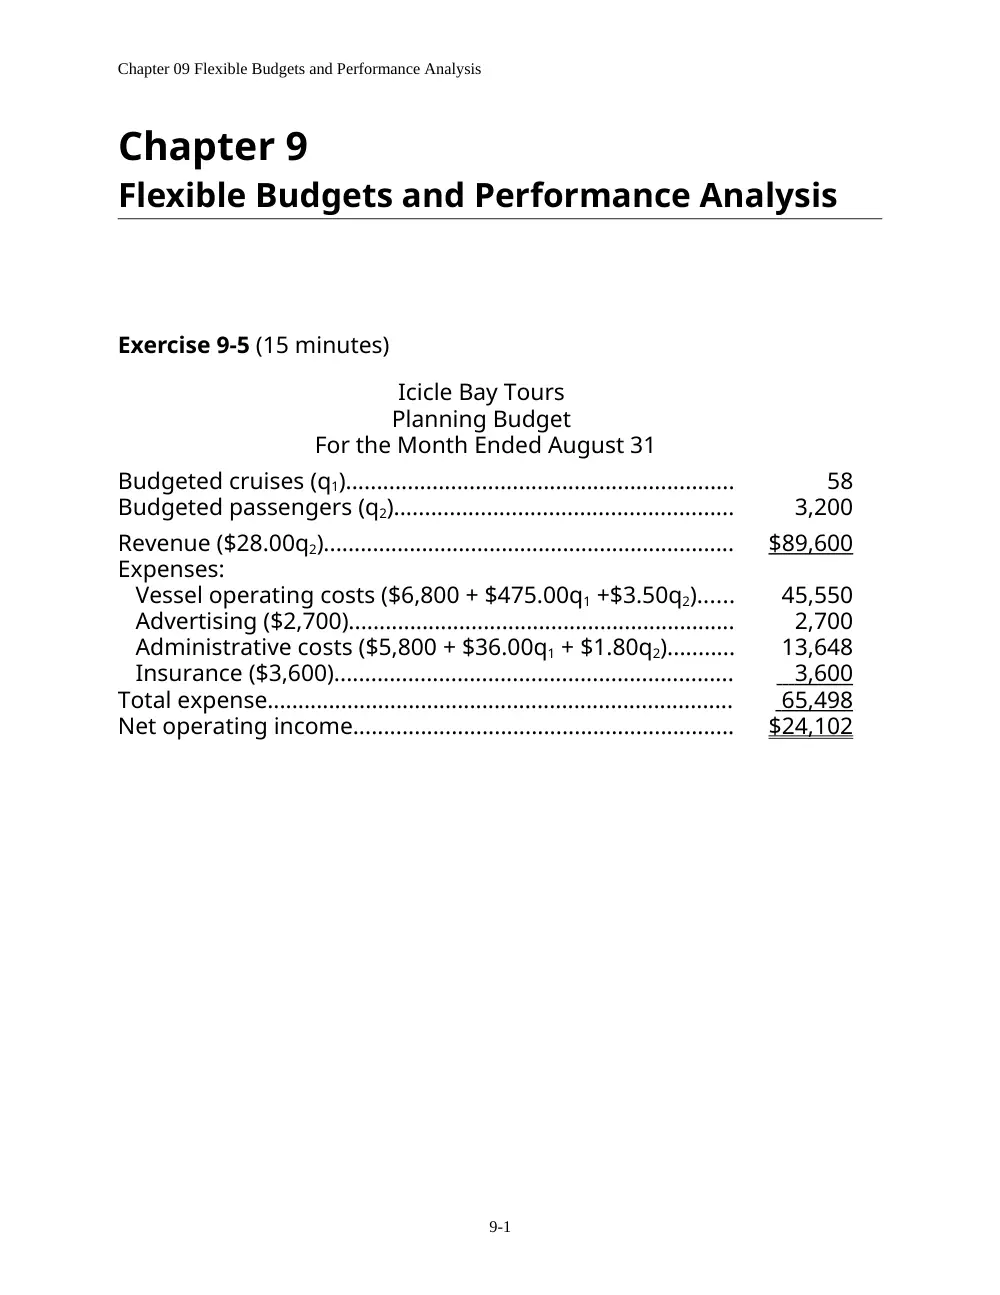
Exercise 9-5 (15 minutes)
Icicle Bay Tours
Planning Budget
For the Month Ended August 31
Budgeted cruises (q1)...............................................................
58
Budgeted passengers (q2).......................................................
3,200
Revenue ($28.00q2)...................................................................
$89,600
Expenses:
Vessel operating costs ($6,800 + $475.00q1 +$3.50q2)......
45,550
Advertising ($2,700)...............................................................
2,700
Administrative costs ($5,800 + $36.00q1 + $1.80q2)...........
13,648
Insurance ($3,600).................................................................
3,600
Total expense............................................................................
65,498
Net operating income..............................................................
$24,102
9-1
Chapter 09 Flexible Budgets and Performance Analysis
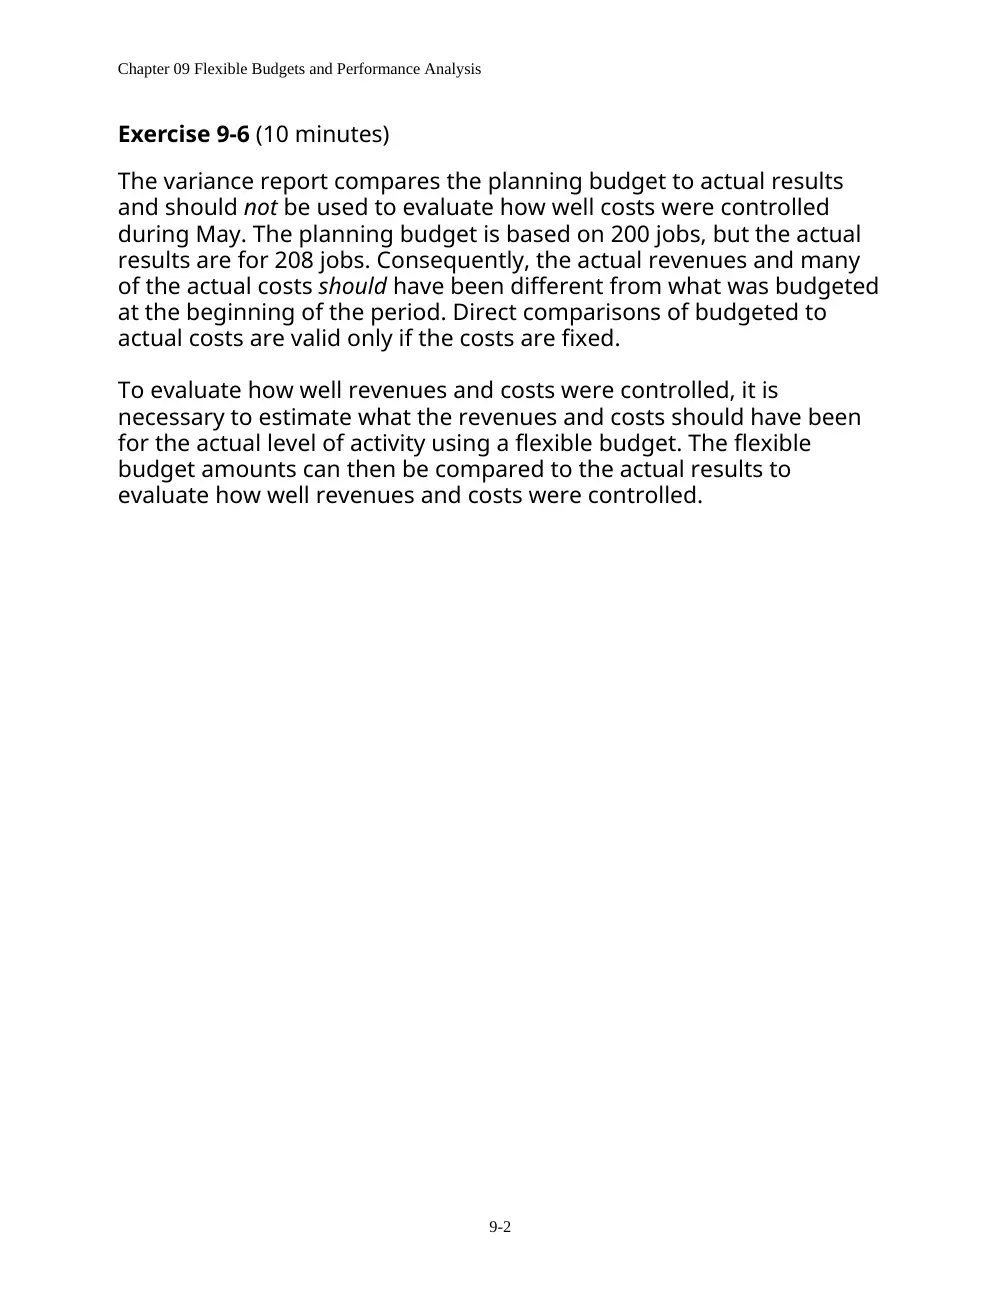
Exercise 9-6 (10 minutes)
The variance report compares the planning budget to actual results
and should not be used to evaluate how well costs were controlled
during May. The planning budget is based on 200 jobs, but the actual
results are for 208 jobs. Consequently, the actual revenues and many
of the actual costs should have been different from what was budgeted
at the beginning of the period. Direct comparisons of budgeted to
actual costs are valid only if the costs are fixed.
To evaluate how well revenues and costs were controlled, it is
necessary to estimate what the revenues and costs should have been
for the actual level of activity using a flexible budget. The flexible
budget amounts can then be compared to the actual results to
evaluate how well revenues and costs were controlled.
9-2
Chapter 09 Flexible Budgets and Performance Analysis
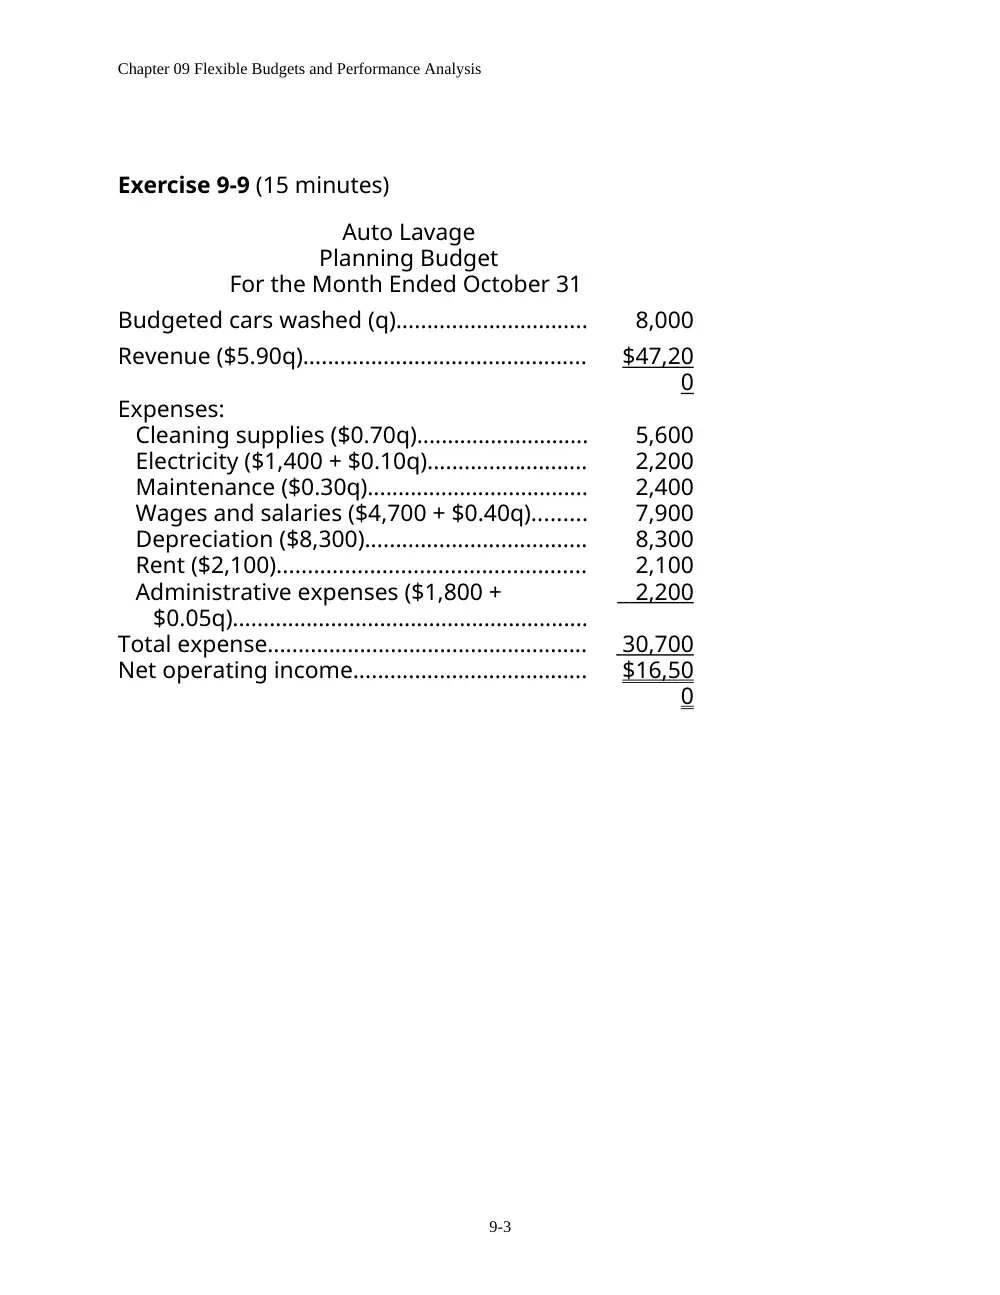
Exercise 9-9 (15 minutes)
Auto Lavage
Planning Budget
For the Month Ended October 31
Budgeted cars washed (q)...............................
8,000
Revenue ($5.90q)..............................................
$47,20
0
Expenses:
Cleaning supplies ($0.70q)............................
5,600
Electricity ($1,400 + $0.10q)..........................
2,200
Maintenance ($0.30q)....................................
2,400
Wages and salaries ($4,700 + $0.40q).........
7,900
Depreciation ($8,300)....................................
8,300
Rent ($2,100)..................................................
2,100
Administrative expenses ($1,800 +
$0.05q)..........................................................
2,200
Total expense....................................................
30,700
Net operating income......................................
$16,50
0
9-3
Chapter 09 Flexible Budgets and Performance Analysis
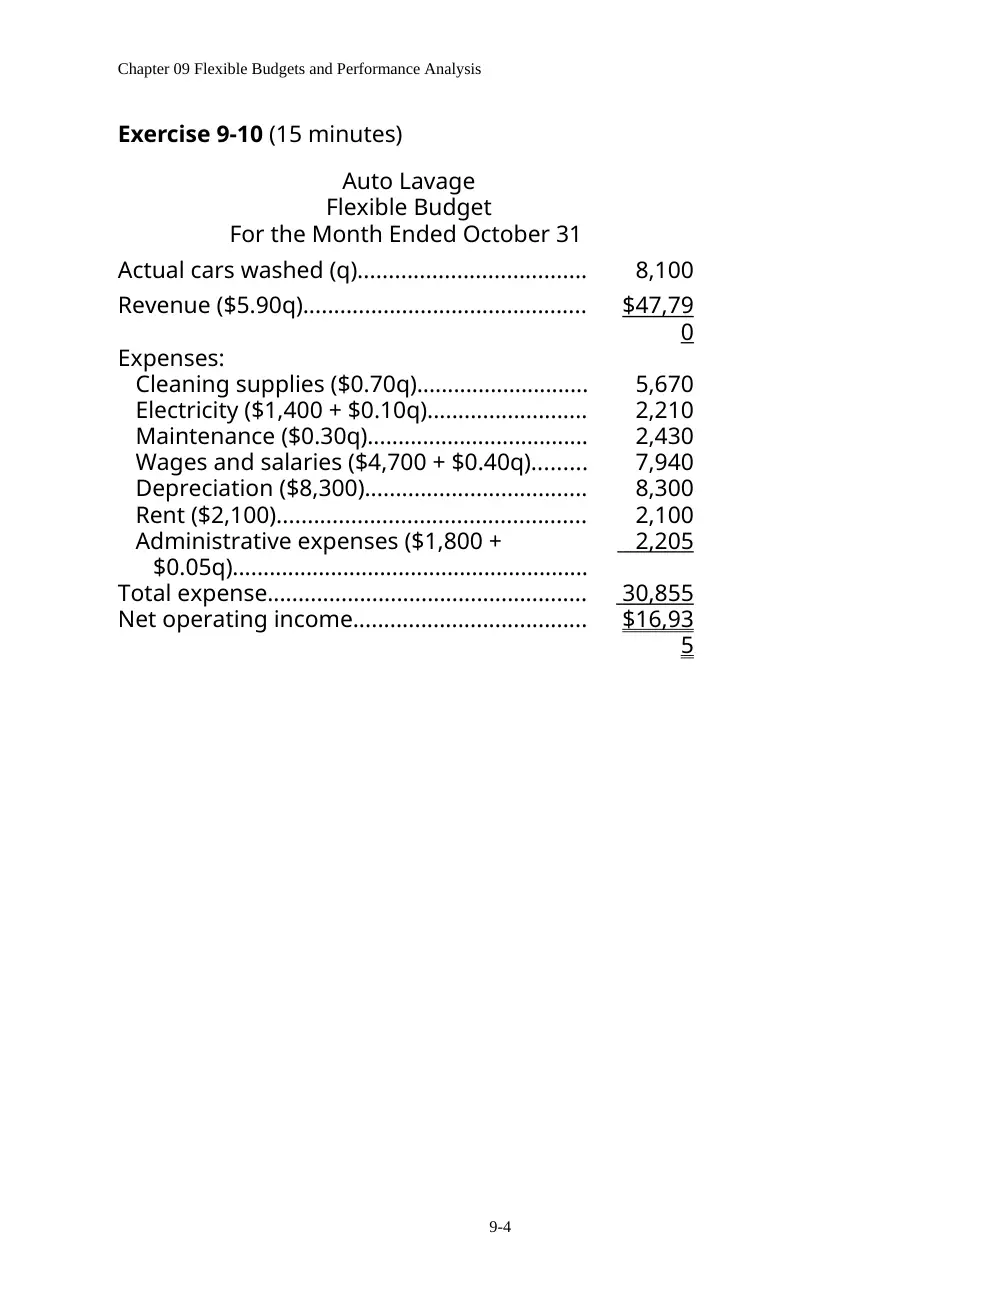
Exercise 9-10 (15 minutes)
Auto Lavage
Flexible Budget
For the Month Ended October 31
Actual cars washed (q).....................................
8,100
Revenue ($5.90q)..............................................
$47,79
0
Expenses:
Cleaning supplies ($0.70q)............................
5,670
Electricity ($1,400 + $0.10q)..........................
2,210
Maintenance ($0.30q)....................................
2,430
Wages and salaries ($4,700 + $0.40q).........
7,940
Depreciation ($8,300)....................................
8,300
Rent ($2,100)..................................................
2,100
Administrative expenses ($1,800 +
$0.05q)..........................................................
2,205
Total expense....................................................
30,855
Net operating income......................................
$16,93
5
9-4
Chapter 09 Flexible Budgets and Performance Analysis
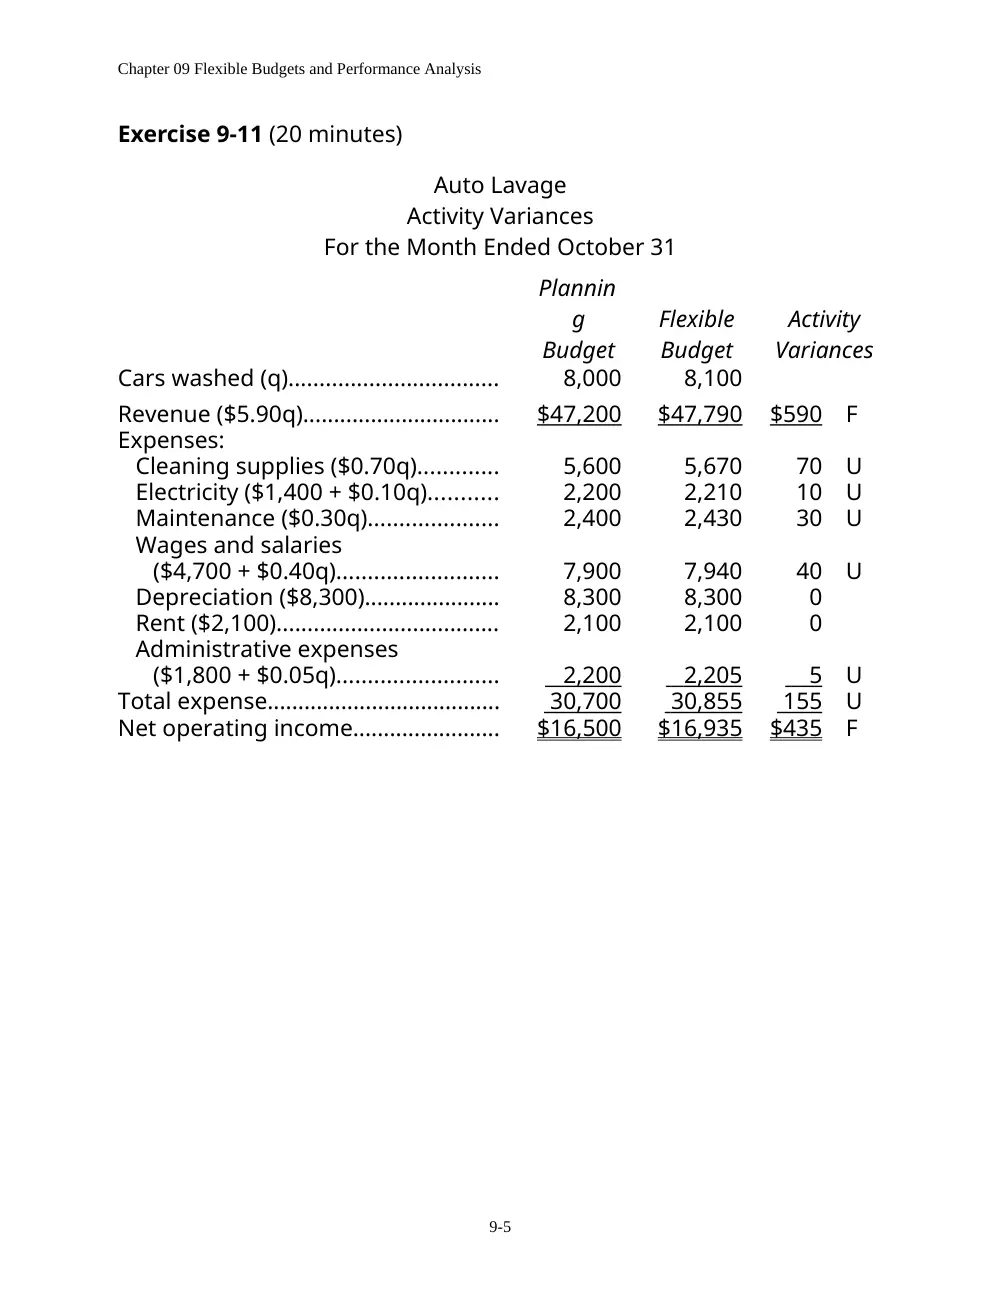
Exercise 9-11 (20 minutes)
Auto Lavage
Activity Variances
For the Month Ended October 31
Plannin
g
Budget
Flexible
Budget
Activity
Variances
Cars washed (q)..................................
8,000
8,100
Revenue ($5.90q)................................
$47,200
$47,790
$590
F
Expenses:
Cleaning supplies ($0.70q).............
5,600
5,670
70
U
Electricity ($1,400 + $0.10q)...........
2,200
2,210
10
U
Maintenance ($0.30q).....................
2,400
2,430
30
U
Wages and salaries
($4,700 + $0.40q)..........................
7,900
7,940
40
U
Depreciation ($8,300)......................
8,300
8,300
0
Rent ($2,100)....................................
2,100
2,100
0
Administrative expenses
($1,800 + $0.05q)..........................
2,200
2,205
5
U
Total expense......................................
30,700
30,855
155
U
Net operating income........................
$16,500
$16,935
$435
F
9-5
Chapter 09 Flexible Budgets and Performance Analysis
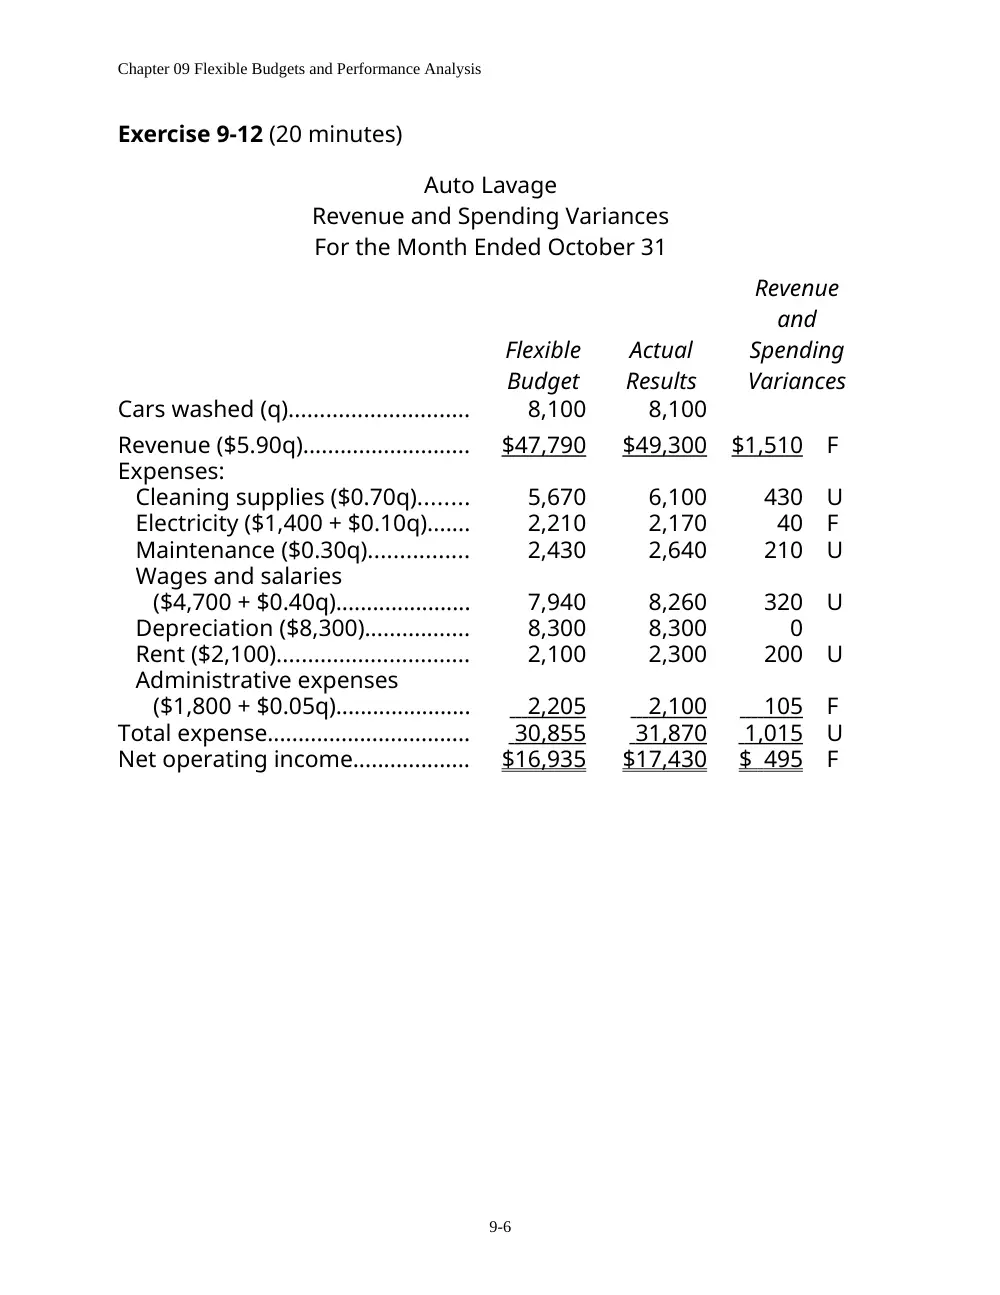
Exercise 9-12 (20 minutes)
Auto Lavage
Revenue and Spending Variances
For the Month Ended October 31
Flexible
Budget
Actual
Results
Revenue
and
Spending
Variances
Cars washed (q).............................
8,100
8,100
Revenue ($5.90q)...........................
$47,790
$49,300
$1,510
F
Expenses:
Cleaning supplies ($0.70q)........
5,670
6,100
430
U
Electricity ($1,400 + $0.10q).......
2,210
2,170
40
F
Maintenance ($0.30q)................
2,430
2,640
210
U
Wages and salaries
($4,700 + $0.40q)......................
7,940
8,260
320
U
Depreciation ($8,300).................
8,300
8,300
0
Rent ($2,100)...............................
2,100
2,300
200
U
Administrative expenses
($1,800 + $0.05q)......................
2,205
2,100
105
F
Total expense.................................
30,855
31,870
1,015
U
Net operating income...................
$16,935
$17,430
$ 495
F
9-6
Chapter 09 Flexible Budgets and Performance Analysis
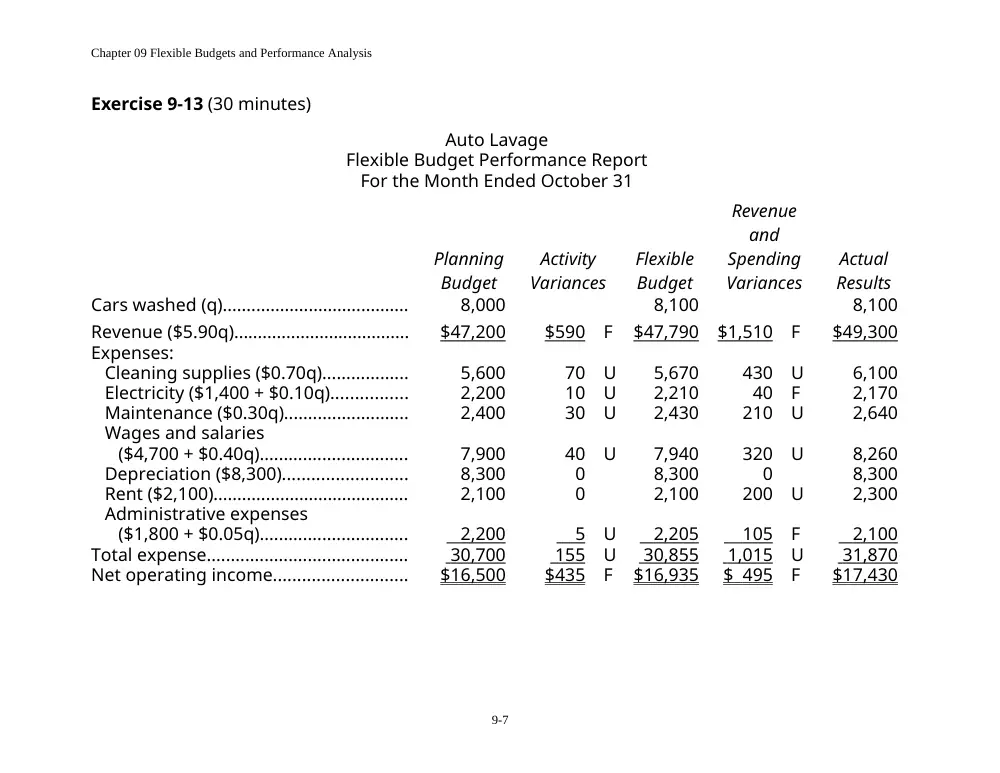
Exercise 9-13 (30 minutes)
Auto Lavage
Flexible Budget Performance Report
For the Month Ended October 31
Planning
Budget
Activity
Variances
Flexible
Budget
Revenue
and
Spending
Variances
Actual
Results
Cars washed (q).......................................
8,000
8,100
8,100
Revenue ($5.90q).....................................
$47,200
$590
F
$47,790
$1,510
F
$49,300
Expenses:
Cleaning supplies ($0.70q)..................
5,600
70
U
5,670
430
U
6,100
Electricity ($1,400 + $0.10q)................
2,200
10
U
2,210
40
F
2,170
Maintenance ($0.30q)..........................
2,400
30
U
2,430
210
U
2,640
Wages and salaries
($4,700 + $0.40q)...............................
7,900
40
U
7,940
320
U
8,260
Depreciation ($8,300)..........................
8,300
0
8,300
0
8,300
Rent ($2,100).........................................
2,100
0
2,100
200
U
2,300
Administrative expenses
($1,800 + $0.05q)...............................
2,200
5
U
2,205
105
F
2,100
Total expense..........................................
30,700
155
U
30,855
1,015
U
31,870
Net operating income............................
$16,500
$435
F
$16,935
$ 495
F
$17,430
9-7
Chapter 09 Flexible Budgets and Performance Analysis
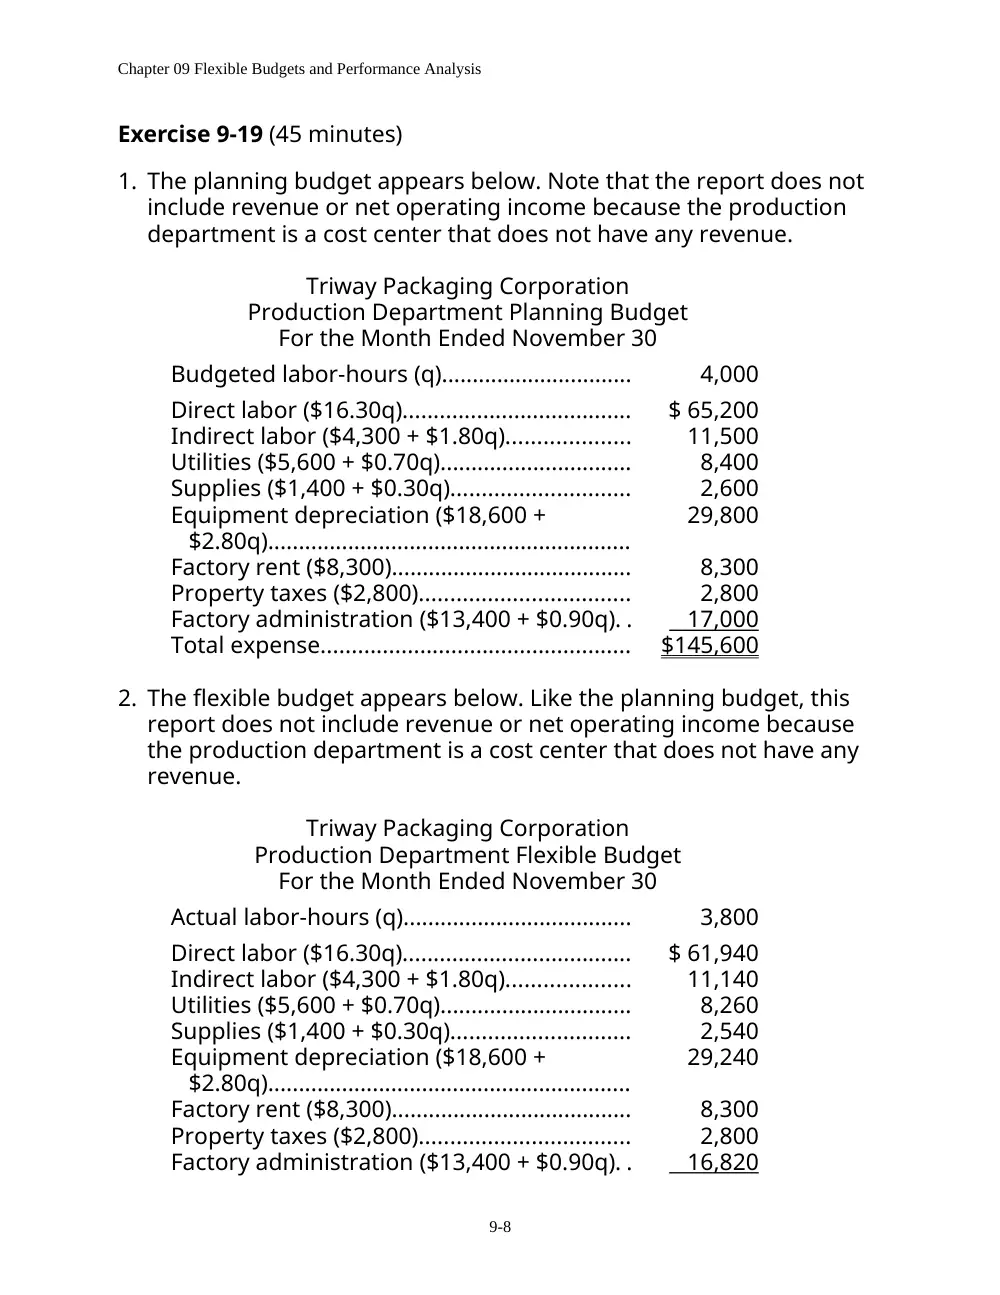
Exercise 9-19 (45 minutes)
1. The planning budget appears below. Note that the report does not
include revenue or net operating income because the production
department is a cost center that does not have any revenue.
Triway Packaging Corporation
Production Department Planning Budget
For the Month Ended November 30
Budgeted labor-hours (q)...............................
4,000
Direct labor ($16.30q).....................................
$ 65,200
Indirect labor ($4,300 + $1.80q)....................
11,500
Utilities ($5,600 + $0.70q)...............................
8,400
Supplies ($1,400 + $0.30q).............................
2,600
Equipment depreciation ($18,600 +
$2.80q)...........................................................
29,800
Factory rent ($8,300).......................................
8,300
Property taxes ($2,800)..................................
2,800
Factory administration ($13,400 + $0.90q). .
17,000
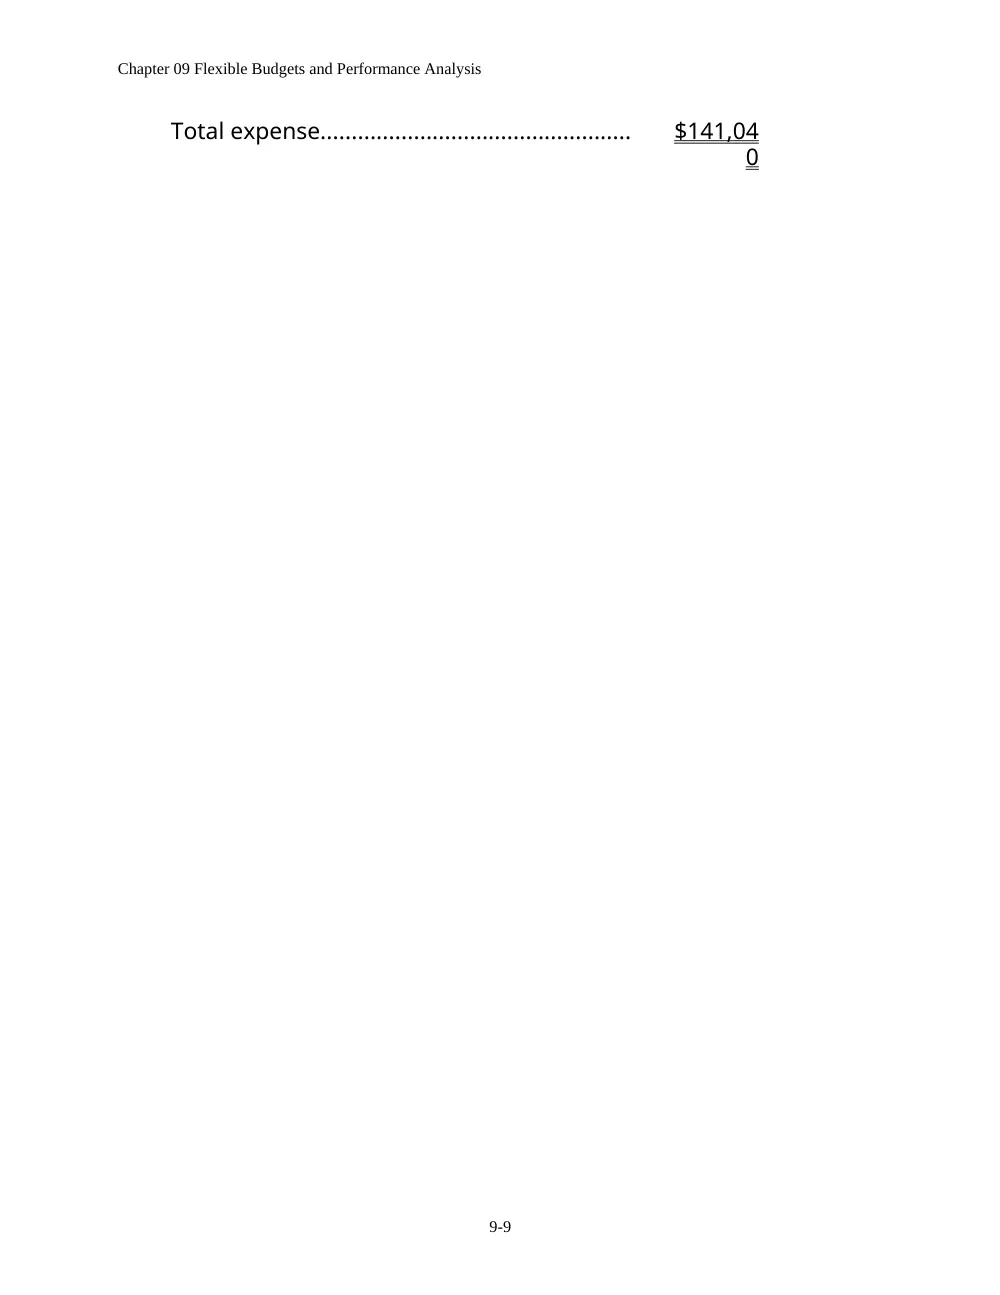
Total expense..................................................
$145,600
2. The flexible budget appears below. Like the planning budget, this
report does not include revenue or net operating income because
the production department is a cost center that does not have any
revenue.
Triway Packaging Corporation
Production Department Flexible Budget
For the Month Ended November 30
Actual labor-hours (q).....................................
3,800
Direct labor ($16.30q).....................................
$ 61,940
Indirect labor ($4,300 + $1.80q)....................
11,140
Utilities ($5,600 + $0.70q)...............................
8,260
Supplies ($1,400 + $0.30q).............................
2,540
Equipment depreciation ($18,600 +
$2.80q)...........................................................
29,240
Factory rent ($8,300).......................................
8,300
Property taxes ($2,800)..................................
2,800
Factory administration ($13,400 + $0.90q). .
16,820
9-8
Chapter 09 Flexible Budgets and Performance Analysis
Total expense..................................................
$141,04
0
9-9
Chapter 09 Flexible Budgets and Performance Analysis
Exercise 9-19 (continued)
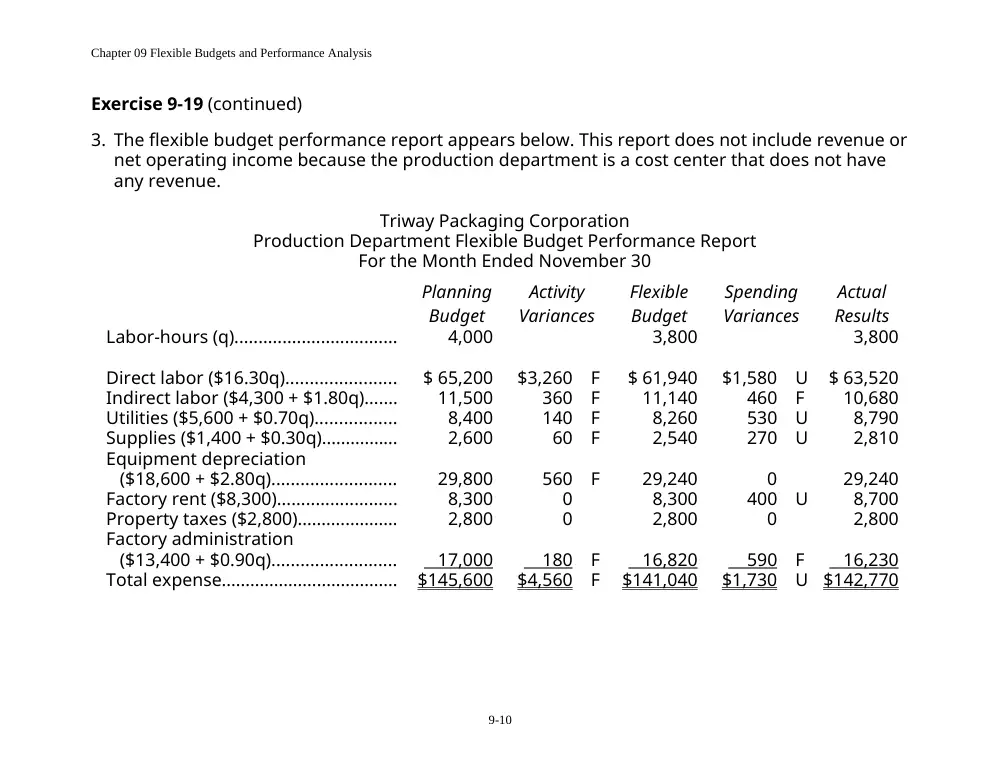
3. The flexible budget performance report appears below. This report does not include revenue or
net operating income because the production department is a cost center that does not have
any revenue.
Triway Packaging Corporation
Production Department Flexible Budget Performance Report
For the Month Ended November 30
Planning
Budget
Activity
Variances
Flexible
Budget
Spending
Variances
Actual
Results
Labor-hours (q)..................................
4,000
3,800
3,800
Direct labor ($16.30q).......................
$ 65,200
$3,260
F
$ 61,940
$1,580
U
$ 63,520
Indirect labor ($4,300 + $1.80q).......
11,500
360
F
11,140
460
F
10,680
Utilities ($5,600 + $0.70q).................
8,400
140
F
8,260
530
U
8,790
Supplies ($1,400 + $0.30q)................
2,600
60
F
2,540
270
U
2,810
Equipment depreciation
($18,600 + $2.80q)..........................
29,800
560
F
29,240
0
29,240
Factory rent ($8,300).........................
8,300
0
8,300
400
U
8,700
Property taxes ($2,800).....................
2,800
0
2,800
0
2,800
Factory administration
($13,400 + $0.90q)..........................
17,000
180
F
16,820
590
F
16,230
Total expense.....................................
$145,600
$4,560
F
$141,040
$1,730
U
$142,770
9-10
Chapter 09 Flexible Budgets and Performance Analysis
Exercise 9-19 (continued)
4. The overall favorable activity variance of $4,560 occurred because the actual level of activity was
less than the budgeted level of activity. Because of this decreased level of activity, some of the
costs should have been lower than budgeted. Consequently, calling this a favorable variance is
a bit misleading. On the other hand, the overall unfavorable spending variance of $1,730 may
be of concern to management. Why did the unfavorable—and favorable—variances occur?
Even the relatively small unfavorable spending variance for supplies of $270 should probably be
investigated because, as a percentage of what the cost should have been ($270/$2,540 =
10.7%), this variance is fairly large.
9-11