
ACCT 215 Midterm, Fall 2004
American University of Beirut · Management Accounting · 6 pages


More ACCT 215 files
- Syllabus · Spring 2012LabView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
Show the text of this exam
American University of Beirut
Olayan School of Business
;~
ACCT 215 puns
. MIDTERM —
os Fall 2004 - 2005
November 23, 2004
Name: © dnwomd N gacoy
ID #:_NOOU OAIG4
Section:_|-h =3h14
Instructor:_ Mrs. R : N “LAAAL
Time: 2 Hours
The examination is comprised of seven pages and the following questions:
Question | Type Points Minutes
1 Multiple choice 20 -5 30
Break-Even Analysis 20 20
Joint Products 15 15
Cost Management 15 15
Keep/Drop a Product Line 15 15
Measurement of Cost 15 15
Behaviour
Cushion 10
Total 100 120
INSTRUCTIONS:
PLEASE ANSWER ALL QUESTIONS (INCLUDING MULTIPLE
CHOICE) ON THE ANSWER BOOKLET. SHOW ALL SUPPORTING
COMPUTATIONS!
GOOD LUCK!
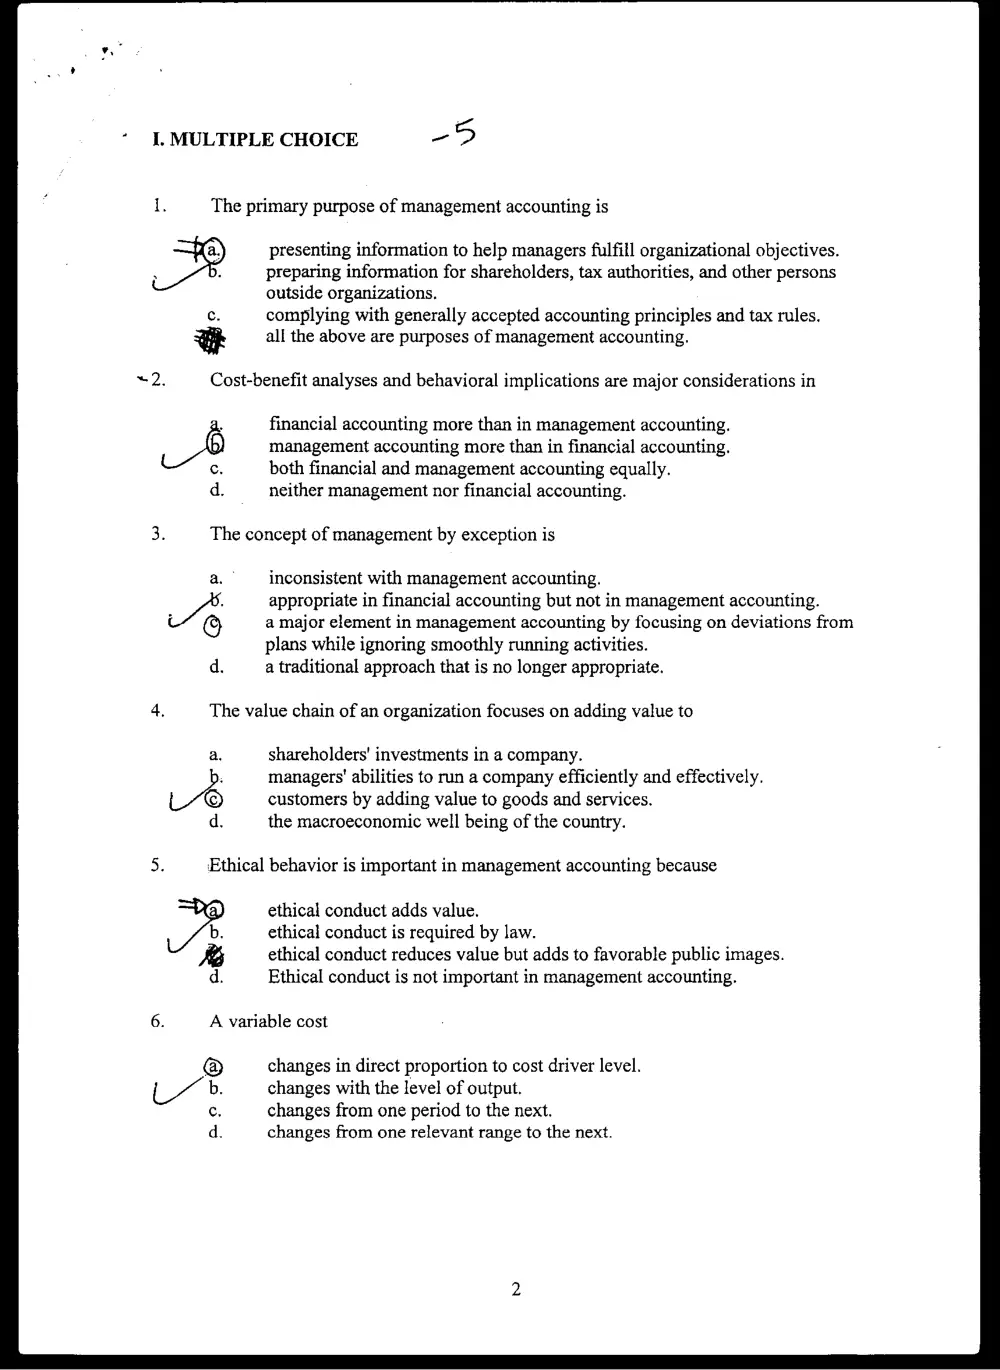
J. MULTIPLE CHOICE -“ 5
The primary purpose of management accounting is
a.) presenting information to help managers fulfill organizational objectives.
b. preparing information for shareholders, tax authorities, and other persons
outside organizations.
c. complying with generally accepted accounting principles and tax rules.
ig all the above are purposes of management accounting.
+2. Cost-benefit analyses and behavioral implications are major considerations in
management accounting more than in financial accounting.
both financial and management accounting equally.
d. neither management nor financial accounting.
A financial accounting more than in management accounting.
c
The concept of management by exception is
a. inconsistent with management accounting.
“2 : appropriate in financial accounting but not in management accounting.
d
a major element in management accounting by focusing on deviations from
plans while ignoring smoothly running activities.
a traditional approach that is no longer appropriate.
The value chain of an organization focuses on adding value to
a. shareholders’ investments in a company.
managers’ abilities to run a company efficiently and effectively.
customers by adding value to goods and services.
d. the macroeconomic well being of the country.
Ethical behavior is important in management accounting because
ethical conduct adds value.
ethical conduct is required by law.
ethical conduct reduces value but adds to favorable public images.
Ethical conduct is not important in management accounting.
variable cost
changes in direct proportion to cost driver level.
changes with the level of output.
changes from one period to the next.
changes from one relevant range to the next.
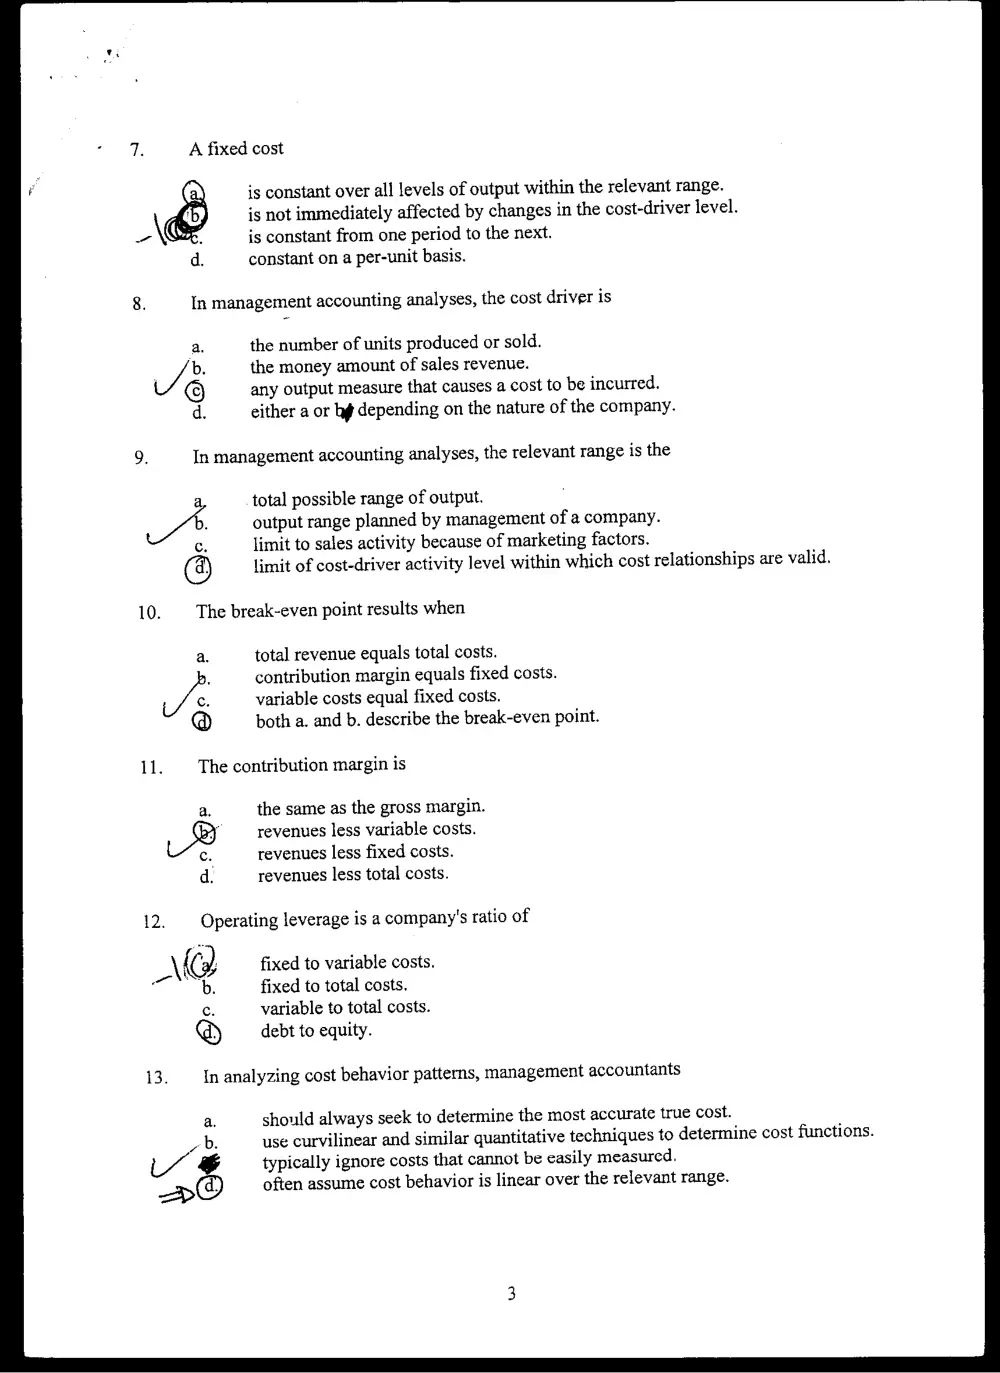
A fixed cost
is constant over all levels of output within the relevant range.
is not immediately affected by changes in the cost-driver level.
is constant from one period to the next.
d. constant on a per-unit basis.
In management accounting analyses, the cost driver is
the number of units produced or sold.
the money amount of sales revenue.
any output measure that causes a cost to be incurred.
either a or bg depending on the nature of the company.
In management accounting analyses, the relevant range is the
total possible range of output.
wa: output range planned by management of a company.
. limit to sales activity because of marketing factors.
limit of cost-driver activity level within which cost relationships are valid,
10. The break-even point results when
a. total revenue equals total costs.
VA contribution margin equals fixed costs.
c.
variable costs equal fixed costs.
both a. and b. describe the break-even point.
The contribution margin is
the same as the gross margin.
revenues less variable costs.
. revenues less fixed costs.
d. revenues less total costs.
12. Operating leverage is a company's ratio of
\@ fixed to variable costs.
a. fixed to total costs.
c
. variable to total costs.
® debt to equity.
13. In analyzing cost behavior patterns, management accountants
a. should always seek to determine the most accurate true cost.
_ bd. use curvilinear and similar quantitative techniques to determine cost functions.
i~ & typically ignore costs that cannot be easily measured.
ENC) often assume cost behavior is linear over the relevant range.
14. Costs that change abruptly at levels of activity are called
a. mixed costs.
1) step costs.
c. curvilinear costs.
d. irrelevant costs.
L~
15. A cost that is represents management's decision to meet an objective and can be
readily chariged is called a
a. variable cost.
b. capacity cost.
ay discretionary fixed cost.
d. committed fixed cost.
16. Cost estimating functions that are based primarily on professional judgment are
a. ‘engineering analysis.
@ accounting analysis.
visual fit analysis.
Cc,
_-\ both a. and b.
Which of the following methods does NOT use historical data to develop a cost
function
high-low.
visual fit.
ordinary least squares regression.
All the above use historical data to develop a cost function.
A measurement of how much of the fluctuation in cost is explained by changes in the
cost driver is
a. The t statistic.
Dy The coefficient of determination R”
c.: The alpha factor o
d. The variance sigma o
19: A cost object or objective is best described as
a. a unit of output produced or sold.
the total money amount of costs incurred.
b.
\ the factor that causes costs to be incurred.
_ anything for which a separate measurement of costs is desired.
—20, | Which scorecard function is associated with planning and control?
a. scorekeeping
tL ©) attention directing
c. problem solving
d
none of the above
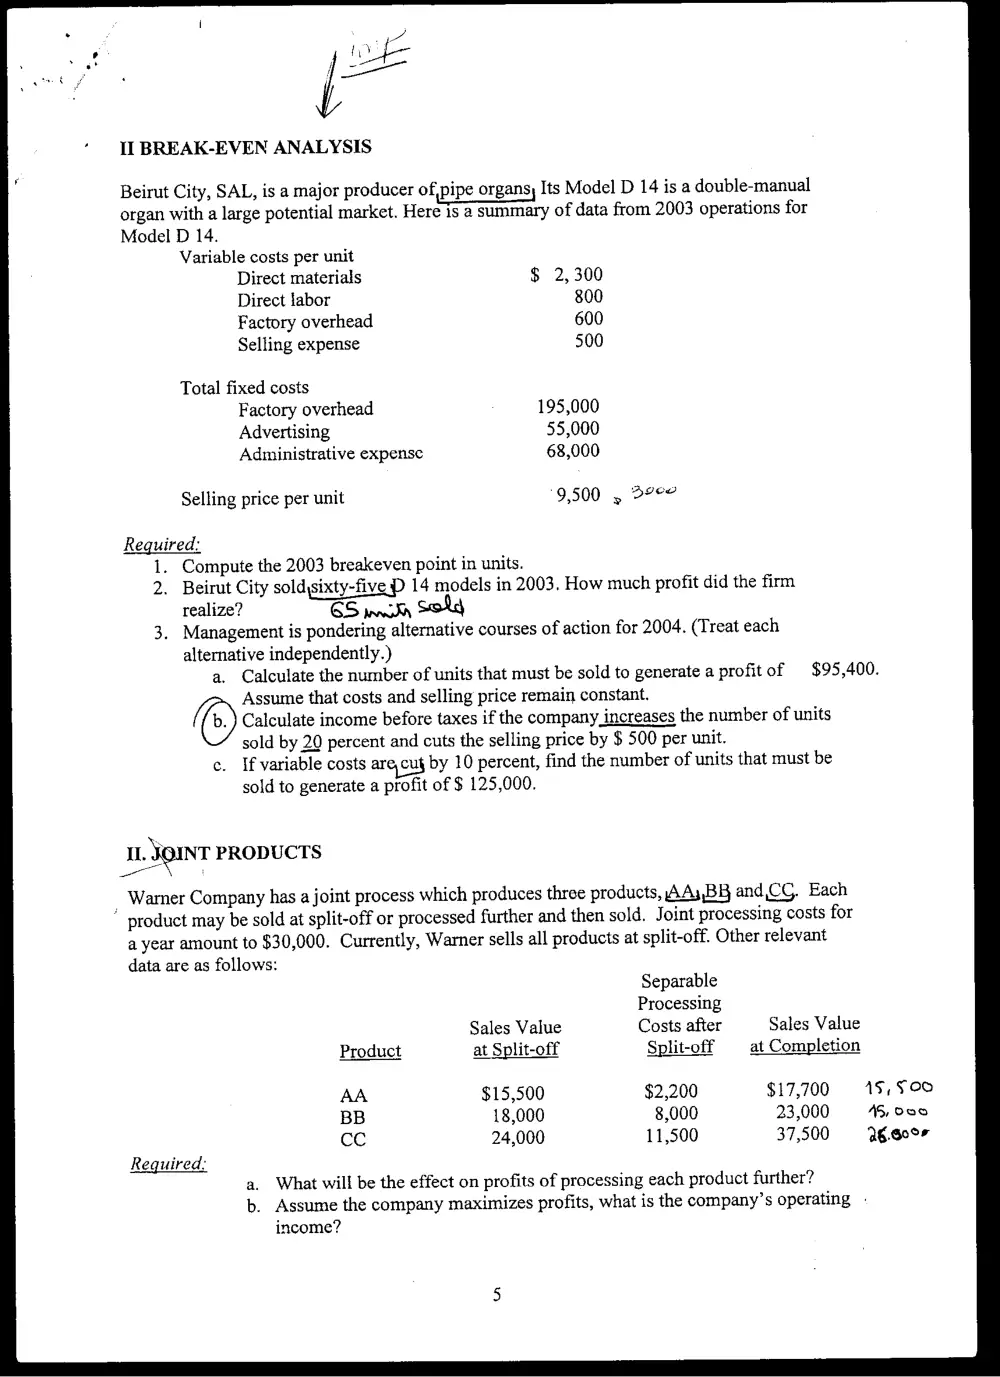
II BREAK-EVEN ANALYSIS
Beirut City, SAL, is a major producer ofipipe organs, Its Model D 14 is a double-manual
organ with a large potential market. Here is a summary of data from 2003 operations for
Model D 14.
Variable costs per unit
Direct materials $ 2,300
Direct labor 800
Factory overhead 600
Selling expense 500
Total fixed costs
Factory overhead 195,000
Advertising 55,000
Administrative expense 68,000
Selling price per unit “9,500 , B2e2
Required:
1. Compute the 2003 breakeven point in units.
2. Beirut City sold\sixty-five D 14 models in 2003. How much profit did the firm
realize? 65 wih soly
3, Management is pondering alternative courses of action for 2004. (Treat each
alternative independently.)
a. Calculate the number of units that must be sold to generate a profit of $95,400.
Calculate income before taxes if the company_increases the number of units
sold by 20 percent and cuts the selling price by $ 500 per unit.
c. If variable costs are,cug by 10 percent, find the number of units that must be
sold to generate a profit of $ 125,000.
() Assume that costs and selling price remain constant.
I, SINT PRODUCTS
a
_ Warner Company has a joint process which produces three products, AAyBB and,CG. Each
* product may be sold at split-off or processed further and then sold, Joint processing costs for
a year amount to $30,000. Currently, Warner sells all products at split-off. Other relevant
data are as follows:
Separable
Processing
Sales Value Costs after Sales Value
Product at Split-off Split-off at Completion
AA $15,500 $2,200 $17,700 15,500
BB 18,000 8,000 23,000 AG, ODO
cc 24,000 11,500 37,500 26.G0°°
Required:
a. What will be the effect on profits of processing each product further?
b. Assume the company maximizes profits, what is the company’s operating -
income?
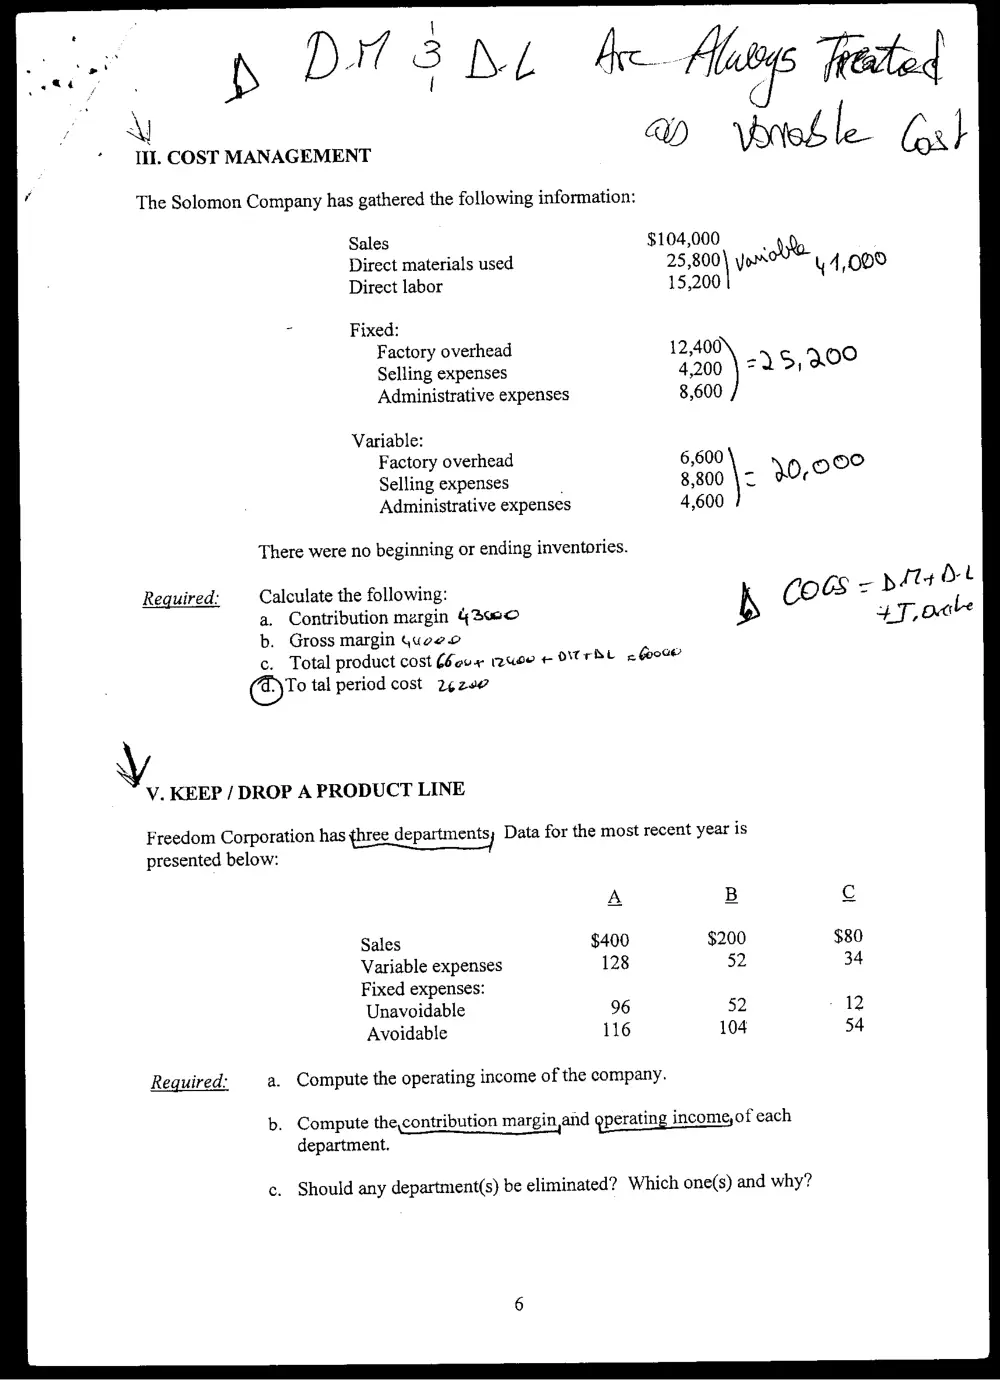
iN D.17 3 NL Ac Hlabys Feitad
IL COST MANAGEMENT D vpried le. (ot
The Solomon Company has gathered the following information:
Sales $104,000 AQ
Direct materials used 25,800) yor 44,008
Direct labor 15,200
Fixed:
Factory overhead 12,400
Selling expenses 4,200 |= 2S 00
Administrative expenses 8,600
Variable:
Factory overhead
Selling expenses ;
Administrative expenses
There were no beginning or ending inventories.
Required: Calculate the following:
a. Contribution margin 4300
b. Gross margin Guoeo
c. Total product cost (6ov% ruoe + OTT BL - Goce
(To tal period cost 242s
vy,
Freedom Corporation has three departments, Data for the most recent year is
presented below:
. KEEP / DROP A PRODUCT LINE
A B
Sales $400
Variable expenses 128 52
Fixed expenses:
Unavoidable 96 52
Avoidable 116
Compute the operating income of the company.
. Compute the,contribution margin,and gperating income,of each
department.
Should any department(s) be eliminated? Which one(s) and why?