
ACO 201 Problems Chapter 4 Solutions, Spring 2013
Notre Dame University–Louaize · Principles of Accounting I · 55 pages · with solution



Showing the first 10 of 55 pages. Download the PDF to see all of it.
More ACO 201 files
- Chapter 1 · Spring 2013ChapterView
- Chapter 2 · Spring 2013ChapterView
- Chapter 3 · Spring 2013ChapterView
- Chapter 4 · Spring 2013ChapterView
- Chapter 5 · Spring 2013ChapterView
- Chapter 6 · Spring 2013ChapterView
- Chapter 7 · Spring 2013ChapterView
- Problems Chapter 2 Solution · Spring 2013Chapter · with solutionView
Show the text of this chapter
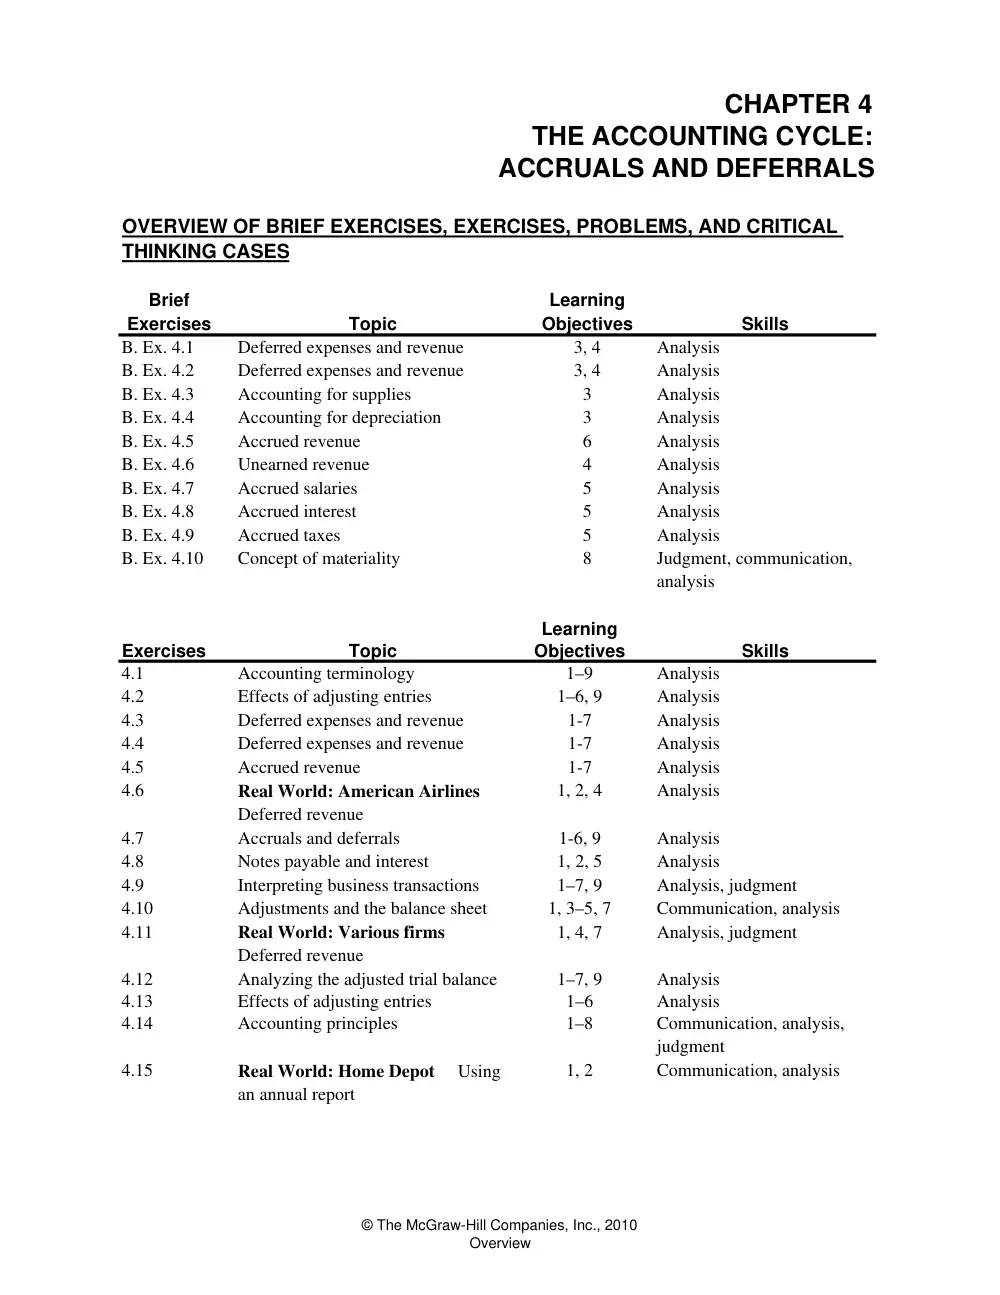
Brief
Exercises
B. Ex. 4.1
B. Ex. 4.2
B. Ex. 4.3
B. Ex. 4.4
Analysis
B. Ex. 4.5
B. Ex. 4.6
B. Ex. 4.7
B. Ex. 4.8
B. Ex. 4.9
B. Ex. 4.10
Learning
Objectives
4.1
1–9
4.2
1–6, 9
4.3
1-7
4.4
Deferred expenses and revenue
1-7
Analysis
4.5
Accrued revenue
1-7
Analysis
4.6
1, 2, 4
Analysis
4.7
Accruals and deferrals
1-6, 9
Analysis
4.8
Notes payable and interest
1, 2, 5
Analysis
4.9
1–7, 9
4.10
1, 3–5, 7
4.11
1, 4, 7
Deferred revenue
4.12
1–7, 9
4.13
Effects of adjusting entries
1–6
Analysis
4.14
1–8
4.15
1, 2
CHAPTER 4
THE ACCOUNTING CYCLE:
ACCRUALS AND DEFERRALS
Analysis, judgment
Real World: Home Depot Using
an annual report
Analyzing the adjusted trial balance
Analysis
Communication, analysis,
judgment
Communication, analysis
Analysis
Accounting terminology
Analysis
Skills
Topic
Deferred revenue
Exercises
Effects of adjusting entries
Adjustments and the balance sheet
Communication, analysis
Interpreting business transactions
Analysis, judgment
Real World: Various firms
Accounting principles
Analysis
Analysis
Topic
Objectives
Deferred expenses and revenue
3, 4
Analysis
Deferred expenses and revenue
3, 4
Accounting for supplies
Analysis
Accounting for depreciation
3
Accrued revenue
6
Analysis
Analysis
Accrued taxes
5
Analysis
Analysis
OVERVIEW OF BRIEF EXERCISES, EXERCISES, PROBLEMS, AND CRITICAL
THINKING CASES
Learning
Skills
Accrued interest
5
Unearned revenue
4
Accrued salaries
5
3
Judgment, communication,
analysis
Real World: American Airlines
Concept of materiality
8
Deferred expenses and revenue
Analysis
© The McGraw-Hill Companies, Inc., 2010
Overview
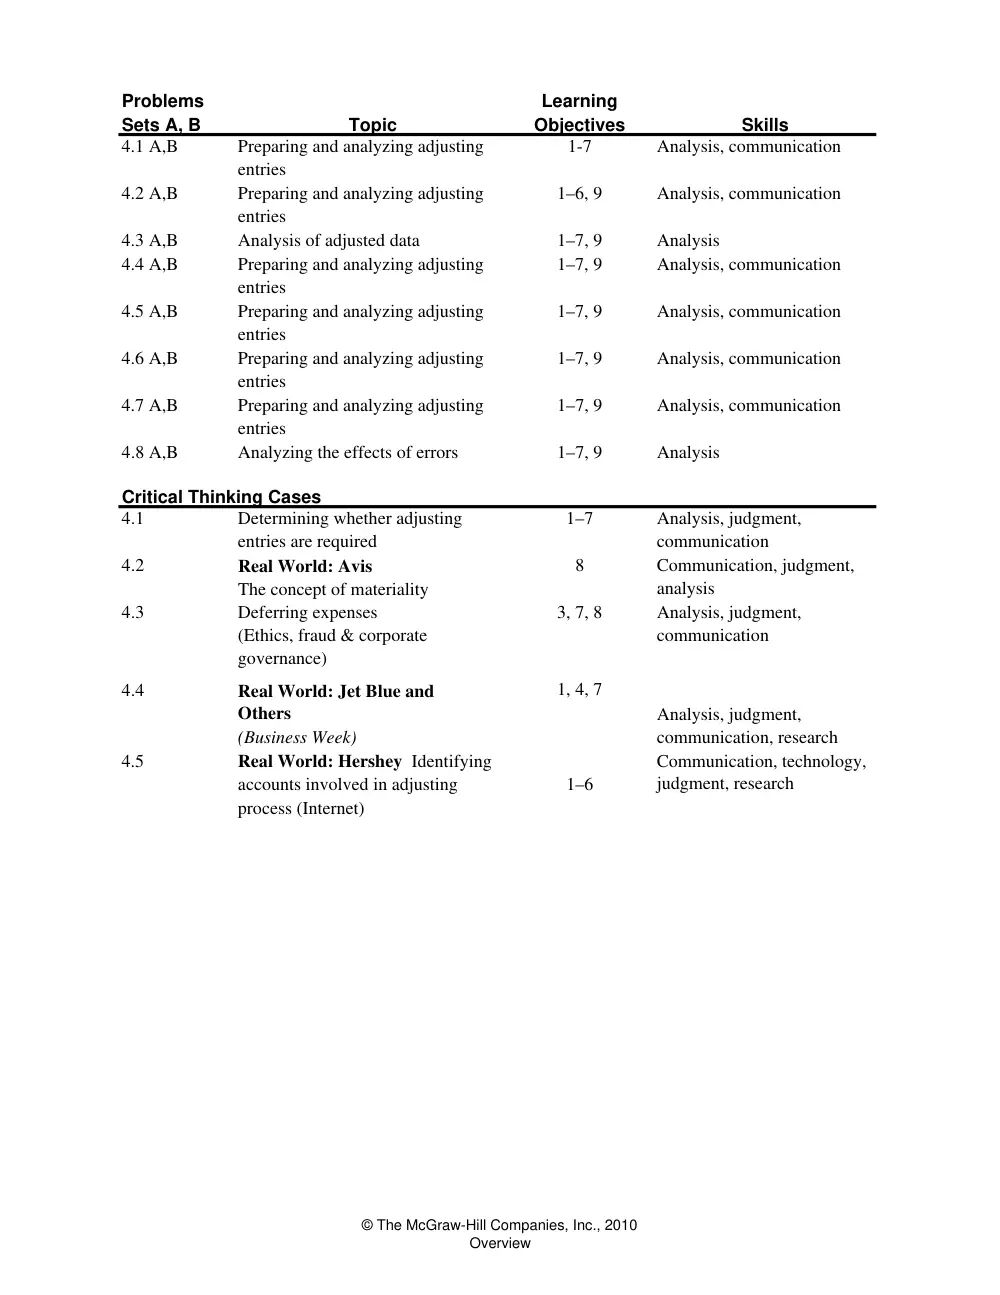
Problems
Learning
Sets A, B
Objectives
4.1 A,B
1-7
4.2 A,B
1–6, 9
4.3 A,B
Analysis of adjusted data
1–7, 9
4.4 A,B
1–7, 9
4.5 A,B
1–7, 9
4.6 A,B
Preparing and analyzing adjusting
entries
1–7, 9
4.7 A,B
Preparing and analyzing adjusting
entries
1–7, 9
4.8 A,B
1–7, 9
4.1
1–7
4.2
Real World: Avis
8
The concept of materiality
4.3
3, 7, 8
4.4
1, 4, 7
(Business Week)
4.5
accounts involved in adjusting
1–6
Analysis, communication
Analysis
Analysis, communication
Topic
Skills
process (Internet)
Deferring expenses
(Ethics, fraud & corporate
governance)
Real World: Hershey Identifying
Critical Thinking Cases
Preparing and analyzing adjusting
entries
Preparing and analyzing adjusting
entries
Preparing and analyzing adjusting
entries
Preparing and analyzing adjusting
entries
Communication, technology,
judgment, research
Analysis, communication
Analysis, communication
Determining whether adjusting
entries are required
Analysis, judgment,
communication
Analyzing the effects of errors
Communication, judgment,
analysis
Analysis, communication
Real World: Jet Blue and
Others
Analysis, judgment,
communication, research
Analysis, communication
Analysis, judgment,
communication
Analysis
© The McGraw-Hill Companies, Inc., 2010
Overview
DESCRIPTIONS OF PROBLEMS AND CRITICAL THINKING CASES
Problems (Sets A and B)
4.1 A,B
20 Easy
4.2 A,B
40 Medium
4.3 A,B
25 Strong
4.4 A,B
4.5 A,B
30 Medium
4.6 A,B
30 Medium
Requires students to prepare adjusting entries and interpret
financial information.
Below are brief descriptions of each problem and case. These descriptions are accompanied by the
estimated time (in minutes) required for completion and by a difficulty rating. The time estimates
assume use of the partially filled-in working papers.
30 Medium
Campus Theater/Off-Campus Playhouse
Requires students to prepare adjusting entries, analyze financial
information, and interpret differences between income taxes
expense and income taxes payable.
Gunflint Adventures/River Rat
Requires students to prepare adjusting entries, classify them as
accruals or deferrals, and discuss the difference between the
book value of an asset and its fair market value.
Requires students to prepare adjusting entries, classify them as
accruals or deferrals, analyze their effects on the financial
statements, and report assets at book value in the balance sheet.
Florida Palms Country Club/Georgia Gun Club
Enchanted Forest/Big Oaks
Alpine Expeditions/Mate Ease
Requires students to prepare adjusting entries, determine
amounts reported in the financial statements, and interpret
certain deferrals.
Terrific Temps/Marvelous Music
Requires students to prepare adjusting entries and determine
amounts reported in the financial statements.
© The McGraw-Hill Companies, Inc., 2010
Overview and Desc. of Cases
Problems (continued)
Ken Hensley Enterprises, Inc./Stillmore Investigations
60 Strong
Requires students to journalize adjusting entries, prepare an adjusted trial
balance, and understand various relationships among financial statement
elements.
Coyne Corporation/Stephen Corporation
Requires students to analyze the effects of errors on financial statement
elements.
Critical Thinking Cases
Judgments and Year-End Adjustments
The Concept of Materiality
Expense Manipulation
Ethics, Fraud & Corporate Governance
Deferred Revenue
15 Medium
Business Week
Identifying Accounts
Internet
4.4
4.3
Students are required to perform an adjusting entry for JetBlue
Corporation and determine from financial data the estimated number of
days that passengers purchase their tickets in advance.
30 Medium
4.2
25 Medium
4.1
4.7 A,B
4.8 A,B
20 Strong
Students are asked to identify accounts in Hershey’s balance sheet that
were most likely to have been involved in the company’s year-end
adjusting entry process.
4.5
10 Easy
Requires students to exercise judgment regarding the need for adjusting
entries.
Discusses the concept of materiality. The purchase of automobiles by
Avis for its rental fleet is used to illustrate how the cumulative effect of
many immaterial transactions can become material.
Students must determine whether the capitalization of advertising
expenditures was in compliance with generally accepted accounting
principles, and whether the decision to do so was ethical.
10 Easy
© The McGraw-Hill Companies, Inc., 2010
Desc. of Prob & Cases
SUGGESTED ANSWERS TO DISCUSSION QUESTIONS
1.
2.
3.
4.
5.
6.
7.
The purpose of making adjusting entries is to recognize certain revenue and expenses that
are not properly measured in the course of recording daily business transactions. These
entries help achieve the goals of accrual accounting by recognizing revenue when it is
earned and recognizing expenses when the related goods or services are used.
The only transactions that require end-of-period adjusting entries are those that affect the
revenue or expenses of more than one accounting period. Adjusting entries then are needed
to apportion the revenue or expense among the affected accounting periods.
All adjusting entries affect both an income statement account and a balance sheet account.
Every adjusting entry involves the recognition of either revenue or expense. Revenue and
expenses represent changes in owners’ equity, which appears in the balance sheet. However,
owners’ equity cannot change by itself; there must also be a corresponding change in either
assets or liabilities.
Making adjusting entries requires a better understanding of accrual accounting than does the
recording of routine business transactions because there is no "external evidence" (such as
bills or invoices) indicating the need for adjusting entries. Adjusting entries are necessary to
reflect recorded costs that have expired and recorded revenue that has been earned or to
recognize previously unrecorded business activities. Thus, the need for adjusting entries is
determined by the accountant’s understanding of the concepts of accrual accounting, not by
external source documents.
Under accrual accounting, an expense is defined as the cost of goods and services used in
the effort to generate revenue. Thus, an expense is incurred when the related goods and
services are used, not when the expense is paid. A 12-month insurance policy represents
insurance coverage that is used up over a 12-month period. The cost of such a policy should
be debited to an asset account and gradually recognized as an expense over the 12 months
that the policy is in force.
Accrual accounting requires that revenue be recognized in the accounting records when it is
earned. If revenue has been earned, but not yet recorded in the accounts, an adjusting entry
should be made to include this revenue in the income of the current period. This entry will
credit a revenue account; as the revenue has not yet been collected, the debit will be to an
account receivable.
The term, unearned revenue, describes amounts that have been collected from customers in
advance and that have not yet been earned. As the company has an obligation to render
services to these customers or to refund their advance payments, unearned revenue appears
in the liability section of the balance sheet. As services are performed for these customers,
the liability is reduced. Therefore, an adjusting entry is made transferring the balance of the
unearned revenue account into a revenue account.
© The McGraw-Hill Companies, Inc., 2010
Q1-7
8.
16,000
16,000
9.
10.
11.
12.
13.
14.
16.
The realization principle governs the timing of revenue recognition. The principle states that
revenue should be recognized (reported in the income statement) in the period in which it is
earned . This does not necessarily coincide with cash flow, however. Cash can be received
from customers in a period before revenue is earned or in a period after revenue is earned.
A $1,000 expenditure is not considered material to all businesses. Most large enterprises round
the dollar amounts shown in their financial statements to the nearest $1 thousand or nearest $1
million dollars.
Deferred expenses are those assets reported in the balance sheet that will later become
expenses reported in the income statement. They include, but are not limited to, office
supplies, prepared rent, prepaid insurance, buildings, equipment, etc.
15.
The matching principle governs the manner in which revenue is offset by the expenses
incurred in producing that revenue. Generally, expenses are matched to revenue in the periods
that resources are consumed in generating revenue earned. Expense recognition does not
necessarily coincide with the payment of cash.
Unprofitable companies recognize a "negative amount" of income tax expense. The adjusting
entry to record income tax expense for a period in which a net loss is incurred requires a debit
to Income Taxes Payable and a credit to Income Taxes Expense.
Salaries Payable ………………………….
Salaries Expense ……………………………………………
To record salaries expense and related liability to employees for the last four days of the year
(4/5 week x $20,000 = $16,000).
The concept of materiality permits accountants to handle items that are unlikely to influence
the decisions of users of the accounting information in the most convenient and economical
manner. Charging the costs of low-priced and short-lived assets immediately to an expense is
not likely to affect the decisions of users of the financial statements. On the other hand,
accounting for these items as assets and recording periodic depreciation would require time,
effort, and cost. Thus, low-priced and short-lived assets are routinely charged to an expense,
because charging them to asset accounts simply is “not worth the bother.”
In the income statement, the Insurance Expense account will be understated; hence total
expenses will be understated, and net income will be overstated. In the balance sheet, the asset
account, Unexpired Insurance, will be overstated, as will the amount for total assets. Offsetting
this overstatement of assets will be an overstatement of retained earnings; hence owners’
equity will be overstated.
Materiality refers to the relative importance of an item or an event to the users of financial
statements. An item is “material” if knowledge of it might reasonably influence the decisions
of financial statement users.
If an item is not material, by definition it is not relevant to decision makers. Therefore, the
item may be treated in the most convenient and economical manner by the preparer of the
financial statements. Thus, the concept of materiality permits departures from other generally
accepted accounting principles in accounting for items that are not material.
© The McGraw-Hill Companies, Inc., 2010
Q8-16
18.
19.
17.
Accrued but uncollected revenue is reported in the balance sheet as accounts receivable.
20.
Carnival Corporation accounts for customer deposits as deferred, or unearned, revenue. As
travelers pay for their cruises in advance, Carnival debits Cash and credits Customer Deposits
(a liability account). As cruises take place, Carnival debits Customer Deposits and credits
Cruise Revenue Earned.
Deferred revenue (also referred to as unearned revenue or customer deposits) is reported in the
balance sheet as a liability.
Accrued but unpaid expenses are reported in the balance sheet as liabilities. They include
items such as salaries payable, interest payable, and taxes payable.
© The McGraw-Hill Companies, Inc., 2010
Q17-20
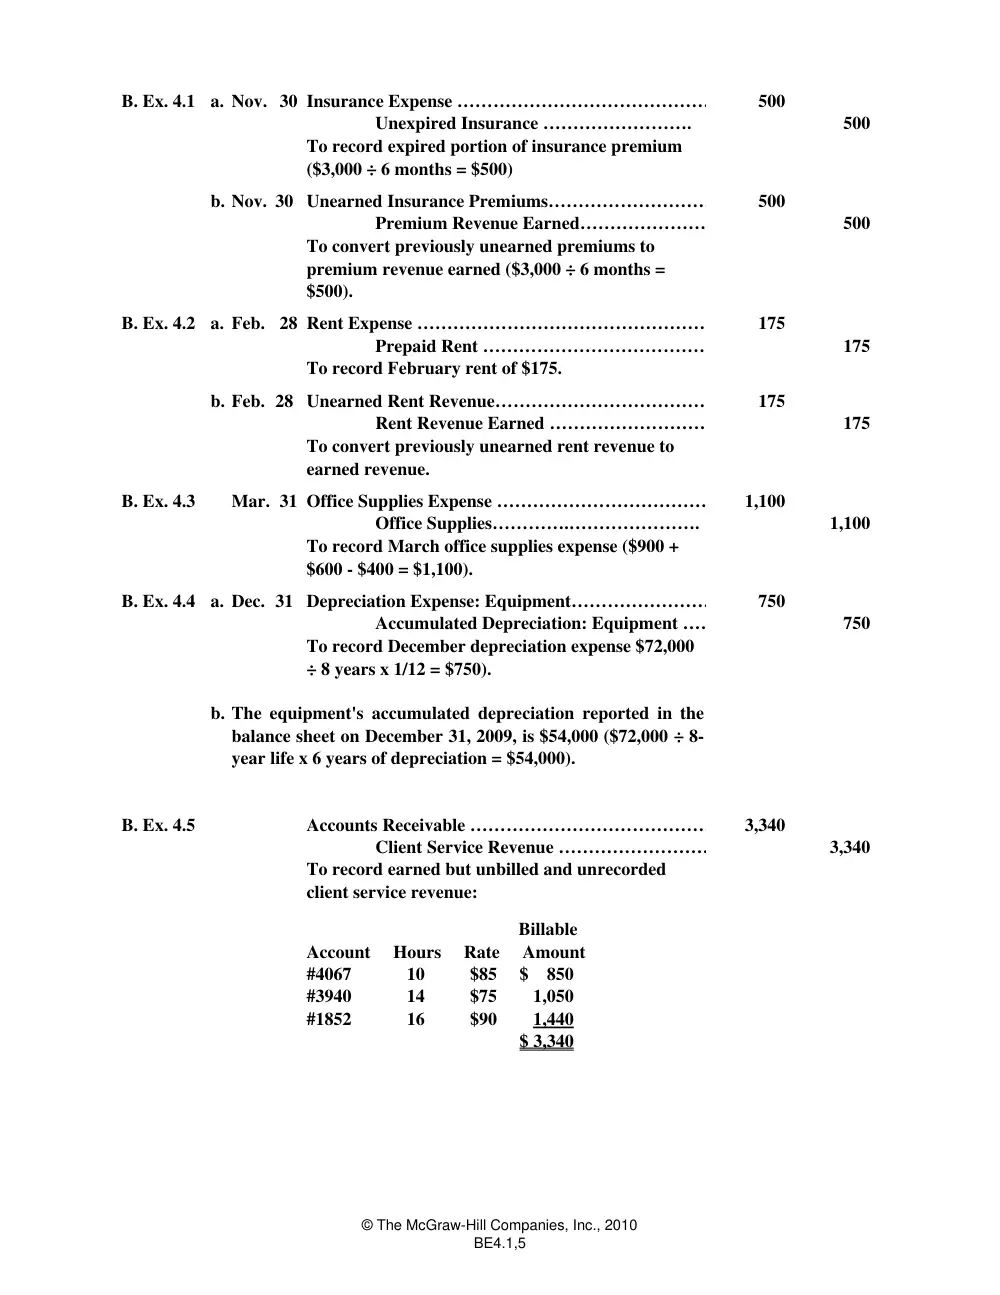
B. Ex. 4.1
a. Nov. 30
500
Unexpired Insurance …………………….
500
b. Nov. 30
500
Premium Revenue Earned…………………
500
B. Ex. 4.2
a. Feb. 28
175
Prepaid Rent …………………………………
175
To record February rent of $175.
b. Feb. 28
175
Rent Revenue Earned ………………………
175
B. Ex. 4.3
Mar. 31
1,100
Office Supplies………….………………….
1,100
B. Ex. 4.4
a. Dec. 31
750
Accumulated Depreciation: Equipment ……
750
b.
B. Ex. 4.5
3,340
Client Service Revenue ………………………
3,340
#4067
10 $85 $ 850
#3940
14 $75 1,050
#1852
16 $90 1,440
$ 3,340
The equipment's accumulated depreciation reported in the
balance sheet on December 31, 2009, is $54,000 ($72,000 ÷ 8-
year life x 6 years of depreciation = $54,000).
Billable
Account Hours Rate Amount
Office Supplies Expense ………………………………
Depreciation Expense: Equipment……………………
To record earned but unbilled and unrecorded
client service revenue:
Accounts Receivable ……………………………………
To record December depreciation expense $72,000
÷ 8 years x 1/12 = $750).
Insurance Expense ……………………………………
To convert previously unearned premiums to
premium revenue earned ($3,000 ÷ 6 months =
$500).
To record expired portion of insurance premium
($3,000 ÷ 6 months = $500)
Unearned Insurance Premiums………………………
Rent Expense …………………………………………
Unearned Rent Revenue………………………………
To convert previously unearned rent revenue to
earned revenue.
To record March office supplies expense ($900 +
$600 - $400 = $1,100).
© The McGraw-Hill Companies, Inc., 2010
BE4.1,5
B. Ex. 4.6
a.
2,800
Client Revenue Earned …………………
2,800
B. Ex. 4.7
a. Dec. 31
175,000
Salaries Payable ……………………………
175,000
To record accrued but unpaid salaries.
b. Jan. 15
180,000
175,000
Cash…………………………………………
355,000
B. Ex. 4.8
a. Dec. 31
160
Interest Payable………….………………….
160
b. Feb.
1
160
Interest Payable…………………………………….
160
Notes Payable……………………………………….
24,000
Cash…...…………………………………….
24,320
B. Ex. 4.9
a. Dec. 31
5,600
Income Taxes Payable………………………
5,600
b.
b.
Salaries Payable………………………………………
Income taxes payable reported in the company's
balance sheet dated December 31, 2009, total
$19,900 ($14,300 + $5,600 = $19,900).
Salaries Expense ………………………………………
Salaries Expense………………………………………
To record payment of salaries.
To record December interest expense ($24,000 x
8% x 1/12 = $160).
Interest Expense……...…………………………….
To accrue December income taxes expense ($62,800
- $57,200 = $5,600).
Income Taxes Expense …………………………………
To record January interest expense and repay the
bank the entire amount owed.
Unearned Client Revenue ……………………………
To convert previously unearned client revenue to
client revenue earned.
Client Revenue earned will be reported in the
company's income statement at $31,800 ($29,000 +
$2,800 = $31,800).
Interest Expense ………………………………………
© The McGraw-Hill Companies, Inc., 2010
BE4.6,9
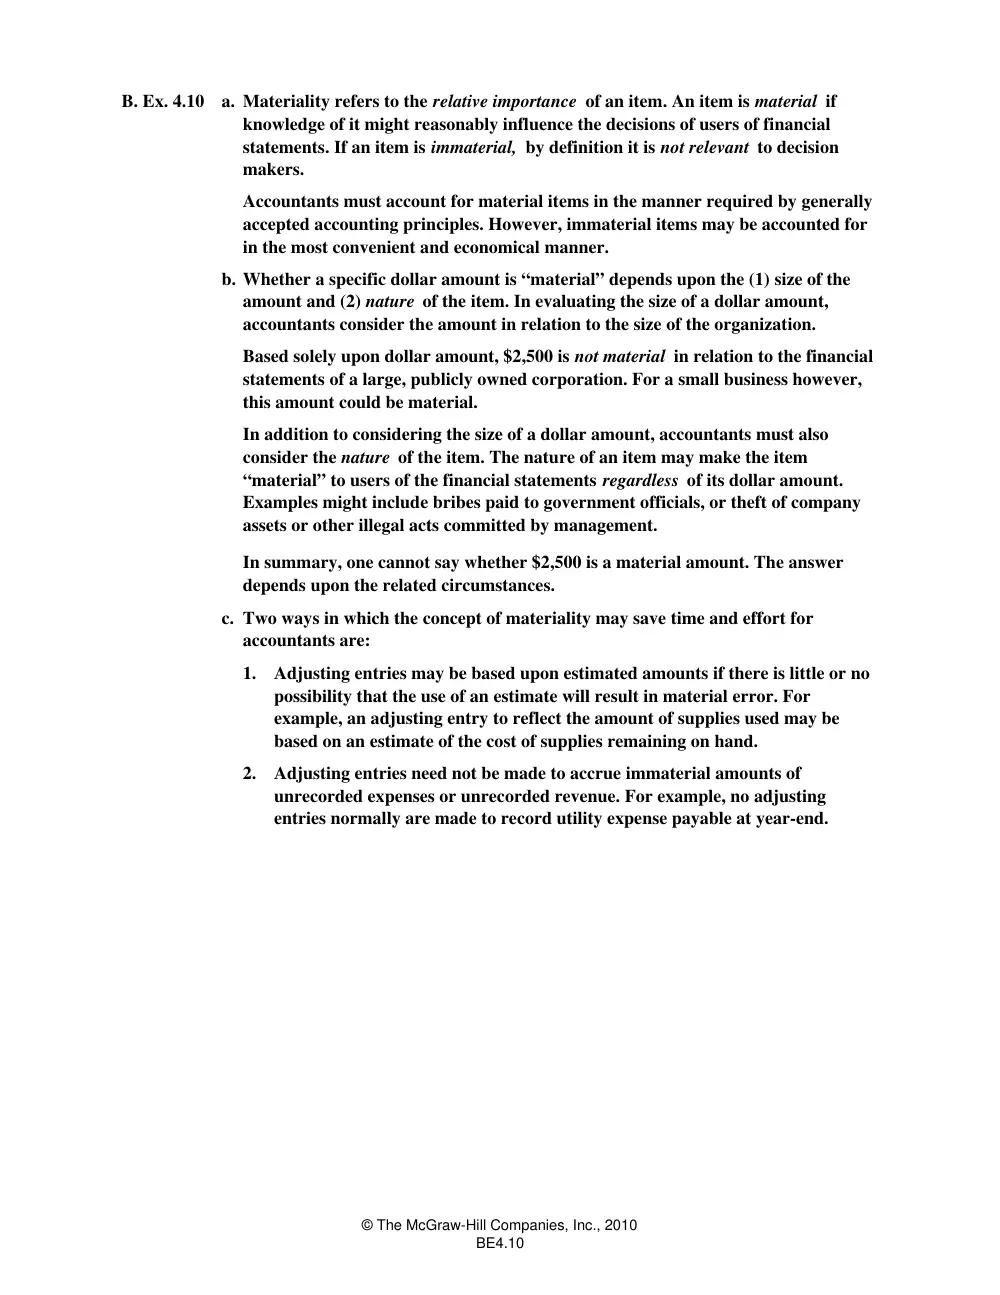
B. Ex. 4.10
a.
b.
c.
1.
2.
Adjusting entries need not be made to accrue immaterial amounts of
unrecorded expenses or unrecorded revenue. For example, no adjusting
entries normally are made to record utility expense payable at year-end.
In addition to considering the size of a dollar amount, accountants must also
consider the nature of the item. The nature of an item may make the item
“material” to users of the financial statements regardless of its dollar amount.
Examples might include bribes paid to government officials, or theft of company
assets or other illegal acts committed by management.
In summary, one cannot say whether $2,500 is a material amount. The answer
depends upon the related circumstances.
Two ways in which the concept of materiality may save time and effort for
accountants are:
Adjusting entries may be based upon estimated amounts if there is little or no
possibility that the use of an estimate will result in material error. For
example, an adjusting entry to reflect the amount of supplies used may be
based on an estimate of the cost of supplies remaining on hand.
Materiality refers to the relative importance of an item. An item is material if
knowledge of it might reasonably influence the decisions of users of financial
statements. If an item is immaterial, by definition it is not relevant to decision
makers.
Accountants must account for material items in the manner required by generally
accepted accounting principles. However, immaterial items may be accounted for
in the most convenient and economical manner.
Whether a specific dollar amount is “material” depends upon the (1) size of the
amount and (2) nature of the item. In evaluating the size of a dollar amount,
accountants consider the amount in relation to the size of the organization.
Based solely upon dollar amount, $2,500 is not material in relation to the financial
statements of a large, publicly owned corporation. For a small business however,
this amount could be material.
© The McGraw-Hill Companies, Inc., 2010
BE4.10
Ex 4.1
a.
b.
c.
d.
e.
f.
g.
h.
Ex. 4.2
Revenue Expenses =
Assets
Liabilities =
NE
I
D
D
NE
D
NE
I
D
NE
I
D
I
NE
I
I
NE
I
NE
I
D
NE
I
D
NE
I
D
D
NE
D
I
NE
I
NE
D
I
Ex. 4.3
1.
240,000
240,000
2.
148,800
148,800
Adjusting
Entry
Book value
Matching principle
Net
Income
Owners'
Equity
Income Statement
Balance Sheet
f.
d.
e.
a.
b.
c.
Ticket Revenue Earned ………………………………
To record earned portion of season ticket revenue relating
to May home games.
SOLUTIONS TO EXERCISES
Materiality
Unrecorded revenue
Adjusting entries
Unearned revenue
Prepaid expenses
None (This is an example of “depreciation expense.”)
Rent Expense ……………………………………………………
Prepaid Rent ……………………………………………
To record rent expense for May ($1,200,000 5 months =
$240,000 per month).
Unearned Ticket Revenue ……………………………………
© The McGraw-Hill Companies, Inc., 2010
E4.1,2,3
Ex. 4.4
a.
b.
18,000,000
18,000,000
c.
90,000,000
90,000,000
d.
Ex. 4.5
a.
(1)
375
375
(2)
10,000
10,000
b.
c.
Ex. 4.6
a.
b.
c.
200,000
200,000
Customer Deposits ……………………………………………
Cruise Revenue …………………………………………
Prepaid Advertising is reported in the balance sheet as an asset. Customer Deposits
are reported in the balance sheet as liabilities.
Advertising Expense …………………………………………
Prepaid Advertising ………………………………………
To record the mailing of brochures costing $18 million
to print.
Air Traffic Liability …………………………………………
To record passenger revenue earned from advance ticket
sales for flights completed.
Passenger Revenue Earned ………………………………
$50,000 x 9% annual rate x 1/12 = $375.
Accounts Receivable ……………………………………
$15,000 ($25,000 - $10,000 earned in December)
At the time cash is collected by American Airlines for advance ticket sales, the
entire amount is accounted for as unearned revenue. The liability created
represents the deferral (or the postponement) of earned revenue until flight services
are actually provided to passengers.
Airlines normally reduce the balance of this liability account by converting it to
passenger revenue as flight services are provided. On some occasions, however, the
liability may be reduced as a result of making cash refunds to customers due to
cancellations.
$2,250 ($50,000 x 9% x 6/12 = $2,250)
To record ten days of unbilled consulting fees at
$1,000 per day.
To record revenue earned for voyages completed.
Note to the instructor: In a recent income statement the company reported
depreciation expense of $1.1 billion.
Interest Expense …………………………………………
Interest Payable …………………………………
Consulting Fees Earned …………………………
The adjusting entry that results in the most significant expense in the
company’s income statement is the recording of depreciation expense on its
cruise ships.
© The McGraw-Hill Companies, Inc., 2010
E4.4,5,6
Ex. 4.7
1,200
1,200
1,100
1,100
64,000
64,000
150
150
3,500
3,500
2,400
2,400
Ex. 4.8
a.
b.
c.
120,000
Notes Payable ……………………………………
120,000
d.
900
Interest Payable …………………………….
900
e.
3.
Accounts Receivable ………………………………………………
Marketing Revenue Earned …………………………………
To record accrued marketing revenue earned in December.
2.
Depreciation Expense: Office Building …………………………
a. 1. Interest Expense …………………………………………………
Interest Payable ………………………………………………
To record interest accrued on bank loan during
December.
Accumulated Depreciation: Office Building …………………
To record depreciation on office building ($330,000/25 years)
x 1/12 = $1,100).
5.
Unearned Revenue ………………………………………………
4.
Insurance Expense ………………………………………………
Prepaid Insurance ……………………………………………
To record insurance expense ($1,800/12 months = $150).
Marketing Revenue Earned …………………………………
To record portion of unearned revenue that had become
earned in December.
6.
Salaries Expense …………………………………………………
Salaries Payable ………………………………………………
To record accrued salaries in December.
b.
$62,650 Increase ($64,000 + $3,500 $1,200 $1,100 $150 $2,400).
The monthly interest expense is $900 ($5,400/6 = $900).
The total interest expense over the life of the note is $5,400 ($120,000 x .09 x 6/12 =
$5,400).
The liability to the bank at December 31, 2009, is $121,800 (Principal, $120,000 +
$1,800 accrued interest).
2009
Obtain from bank six-month loan with interest at 9%
a year.
Oct.
31
Cash ………………………………………………………
Dec.
31
The liability to the bank at March 31, 2010, is $124,500, consisting of $120,000
principal plus $4,500 accrued interest for five months.
To accrue interest expense for December on note
payable ($120,000 x 9% x 1/12).
Interest Expense …………………………………………
© The McGraw-Hill Companies, Inc., 2010
E4.7,8
Ex. 4.9
a. May
1
300,000
Notes Payable …………………………….
300,000
May 31
3,000
Interest Payable ……………………………
3,000
b. May
1
180,000
Cash …………………………………………
180,000
Paid rent for six months at $30,000 per month.
May 31
30,000
Prepaid Rent …………………………………
30,000
c. May
2
910,000
Unearned Admissions Revenue ……………
910,000
May 31
260,000
Admissions Revenue …………………………
260,000
d. May
4
To record admissions revenue from the 20
racing days in May ($910,000 x 20/70 =
$260,000).
Unearned Admissions Revenue ………………………
No entry required.
Cash ……………………………………………………
To record interest expense for May on note
payable to National Bank ($300,000 x 12% x
1/12 = $3,000).
Obtained a three-month loan from National Bank
at 12% interest per year.
Interest Expense ………………………………………
Prepaid Rent ……………………………………………
Rent Expense …………………………………………
To record rent expense for the month of May.
Sold season tickets to the 70-day racing season.
Cash ………………………………………………….…
© The McGraw-Hill Companies, Inc., 2010
E4.9
b.
c.
b. America West Corporation: As passengers complete their flights.
The New York Times Company: As newspapers are delivered.
Carnival Corporation: As passengers complete their cruises.
AFLAC Incorporated: Unearned Premiums
Bally Total Fitness Corporation: Deferred Membership Dues
$8.37 billion ($3.35 book value + $5.02 accumulated depreciation)
Carnival Corporation: Customer Deposits
Devry, Inc.: Deferred Tuition Revenue
Clear Channel Communications, Inc.: Deferred Advertising Income
Ex. 4.10
Ex. 4.11
a.
The New York Times Company: Unexpired Subscriptions
Type III (Accrued compensation is a liability arising from the accrual of unpaid
salaries and wages expense)
When the company receives cash from its customer prior to earning any revenue it
debits Cash and credits either Short-Term Unearned Revenue or Long-Term
Unearned Revenue. As goods are delivered to customers, the company debits the
appropriate unearned revenue account and credits Sales (revenue earned). If the
unearned revenue is expected to convert to earned revenue in the near future
America West Corporation: Air Traffic Liability
a.
Devry, Inc.: As students complete their courses.
Clear Channel Communications, Inc.: As advertisements are aired.
AFLAC Incorporated: As policies expire.
Bally Total Fitness Corporation: As members use the facilities.
© The McGraw-Hill Companies, Inc., 2010
E4.10,11
Ex. 4.12
5,000
Fees Earned………………………………
5,000
600
Unexpired Insurance……………………..
600
To record expired portion of insurance policies.
1,800
Prepaid Rent …………………………………
1,800
300
Office Supplies……………………………..
300
1,000
Accumulated Depreciation: Equip………..
1,000
2,100
Salaries Payable…………………………..
2,100
50
Interest Payable…………………………..
50
600
Income Taxes Payable…………………….
600
3,000
Fees Earned…………..…………………….
3,000
Accounts Receivable……………………………………
To record accrued but uncollected revenue.
To record December office supplies expense.
To record accrued but unpaid interest expense.
Interest Expense……………………………………
To record depreciation of equipment.
Depreciation Expense: Equip……………………..
Salaries Expense…………………………………….
To record accrued but unpaid salaries.
Office Supplies Expense……………………………
To convert previously unearned revenue to earned
revenue.
To record accrued but unpaid income taxes.
Income Taxes Expense…………………………….
Insurance Expense…………………………………
Rent Expense …………………………………………
To record rent expense for December.
Unearned Revenue……………………………………
© The McGraw-Hill Companies, Inc., 2010
E4.12
Ex. 4.13
Adjustment
Net
Owners'
Type
Revenue
Expenses
Income
Assets Liabilities
Equity
Type I
NE
I
D
D
NE
D
Type II
I
NE
I
NE
D
I
Type III
NE
I
D
NE
I
D
Type IV
I
NE
I
I
NE
I
Ex. 4.14
a.
b. Matching.
c. Realization.
Ex. 4.15
•
•
•
•
•
•
•
•
•
•
•
•
•
•
•
• Deferred income taxes
Note to the instructor: The adjustments required for many of the accounts
listed above are discussed in subsequent chapters. Some are beyond the scope
of an introductory text.
Deferred revenue
Income taxes payable
Current installments of long-term debt
Other accrued expenses
Construction in progress
Capital leases
Accrued salaries and related expenses
Sales taxes payable
None (or Materiality). Accounting for immaterial items is not "wrong" or a
"violation" of generally accepted accounting principles; it is merely a waste
of time. The bookkeeper is failing to take advantage of the concept of
materiality, which permits charging immaterial costs directly to expense,
thus eliminating the need to record depreciation in the later periods.
Accounts requiring adjusting entries may include:
Short-term investments
Receivables
Furniture, fixtures and equipment
Leasehold improvements
Merchandise inventories
Other current assets
Buildings
© The McGraw-Hill Companies, Inc., 2010
E4.13,14,15
20 Minutes, Easy
a.
Dec. 31
9,600
Salaries Payable
9,600
31
1,800
Green Fee Revenue
1,800
31
106,000
Membership Dues Earned
106,000
31
1,000
Accumulated Depreciation: Carts
1,000
31
300
Interest Payable
300
31
650
Unexpired Insurance
650
31
31
19,000
Income Taxes Payable
19,000
(6)
(7)
when it is earned. Entering into a contract does not
(8)
To record December insurance expense
($45,000 x 8% x 1/12).
20__
Insurance Expense
To record December depreciation expense
To record accrued interest expense in December
Salaries Expense
To record accrued salaries at December 31.
Accounts Receivable
To record green fees owed by the Tampa Univ. golf
(4)
FLORIDA PALMS COUNTRY CLUB
Interest Expense
Unearned Membership Dues
To record the portion of annual membership dues
Depreciation Expense: Carts
earned in December.
($180,000 ÷ 15 years x 1/12).
(5)
golf team.
Income Taxes Expense
constitute the earning of revenue.
No adjusting entry required. Revenue is recognized
($7,800 x 1/12).
PROBLEM 4.1A
To record income taxes accrued in December.
SOLUTIONS TO PROBLEMS SET A
FLORIDA PALMS COUNTRY CLUB
(Adjusting Entries)
(1)
(2)
(3)
General Journal
© The McGraw-Hill Companies, Inc., 2010
P4.1A
b.
1.
2.
3.
4.
5.
6.
7.
8.
c.
Accruing unpaid expenses.
Accruing uncollected revenue.
PROBLEM 4.1A
FLORIDA PALMS COUNTRY CLUB (concluded)
Converting liabilities to revenue.
Converting assets to expenses.
Accruing unpaid expenses.
Converting assets to expenses.
No adjusting entry required.
Accruing unpaid expenses.
The clubhouse was built in 1925 and has been fully depreciated for financial accounting
purposes. The net book value of an asset reported in the balance sheet does not reflect the
asset’s fair market value. Likewise, depreciation expense reported in the income statement
does not reflect a decline in fair market value, physical obsolescence, or wear-and-tear.
© The McGraw-Hill Companies, Inc., 2010
P4.1A(p.2)
40 Minutes, Medium
Dec. 31
400
Interest Revenue
400
31
85
Interest Payable
85
31
2,000
Accumulated Depreciation: Buildings
2,000
31
31
1,250
Salaries Payable
1,250
31
2,400
Camper Revenue
2,400
31
900
Camper Revenue
900
31
1,000
Accounts Payable
1,000
31
8,400
Income Taxes Payable
8,400
($40 per day x 25 days).
(9)
Income Taxes Expense
To record accrued bus rental expense in December
To record income taxes accrued in December.
a.
(Adjusting Entries)
(1)
(2)
(3)
General Journal
No adjusting entry required. Revenue is recognized
($600,000 ÷ 25 years x 1/12).
(5)
Bus Rental Expense
To record revenue earned from campers that paid in
Unearned Camper Revenue
advance ($5,400 ÷ 6 months).
(8)
Camper Revenue Receivable
constitute the earning of revenue.
To record accrued salary expense in December.
Interest Receivable
To record accrued interest revenue on CDs at
Interest Expense
To record accrued interest expense in December
December 31.
Salaries Expense
PROBLEM 4.2A
(4)
(6)
(7)
ENCHANTED FO