
ACO 201 Problems Chapter 7 Solutions, Spring 2013
Notre Dame University–Louaize · Principles of Accounting I · 56 pages · with solution



Showing the first 10 of 56 pages. Download the PDF to see all of it.
More ACO 201 files
- Chapter 1 · Spring 2013ChapterView
- Chapter 2 · Spring 2013ChapterView
- Chapter 3 · Spring 2013ChapterView
- Chapter 4 · Spring 2013ChapterView
- Chapter 5 · Spring 2013ChapterView
- Chapter 6 · Spring 2013ChapterView
- Chapter 7 · Spring 2013ChapterView
- Problems Chapter 2 Solution · Spring 2013Chapter · with solutionView
Show the text of this chapter
Brief
Learning
Exercises
Objectives
B. Ex. 7.1
B. Ex. 7.2
Bank reconciliations
B. Ex. 7.3
B. Ex. 7.4
B. Ex. 7.5
Analysis
B. Ex. 7.6
B. Ex. 7.7
B. Ex. 7.8
Notes receivable and interest
B. Ex. 7.9
B. Ex. 7.10
Learning
Objectives
7.1
3
7.2
1, 2
7.3
2
7.4
2
7.5
3
7.6
1, 2
7.7
1, 4
7.8
1, 5
Analysis
Analysis, communication
Analysis
Analysis, judgment
Analysis, communication
Analysis, communication
Analysis
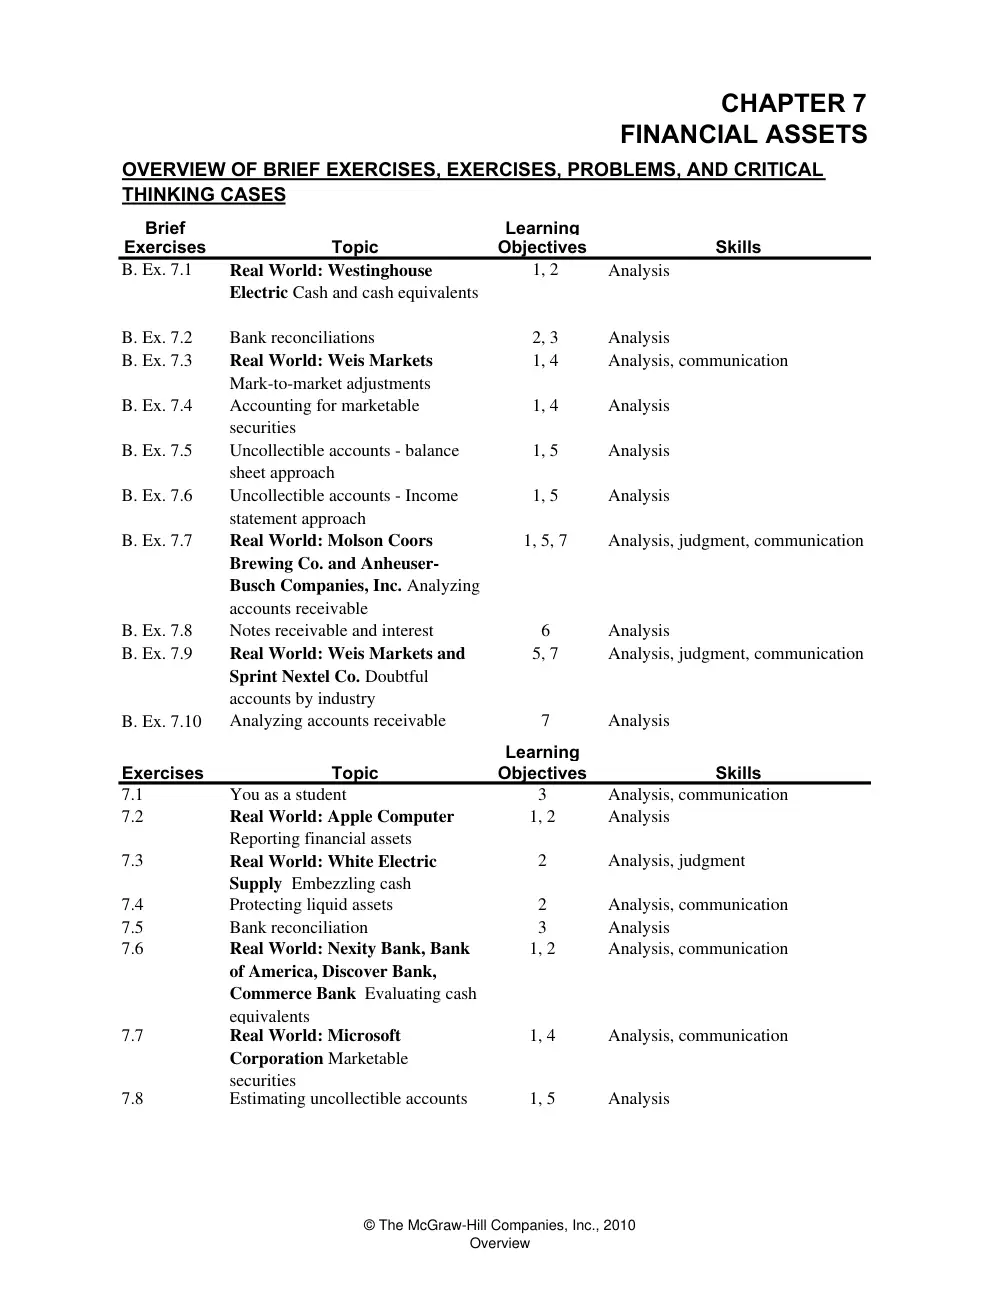
CHAPTER 7
FINANCIAL ASSETS
OVERVIEW OF BRIEF EXERCISES, EXERCISES, PROBLEMS, AND CRITICAL
THINKING CASES
Topic
Skills
1, 4
1, 5
1, 2
Analysis
Bank reconciliation
Exercises
Topic
Accounting for marketable
securities
1, 5
Real World: White Electric
Supply Embezzling cash
Real World: Nexity Bank, Bank
of America, Discover Bank,
Commerce Bank Evaluating cash
equivalents
Real World: Weis Markets and
Sprint Nextel Co. Doubtful
accounts by industry
Real World: Molson Coors
Brewing Co. and Anheuser-
Busch Companies, Inc. Analyzing
accounts receivable
Uncollectible accounts - Income
statement approach
Analysis
1, 5, 7
Analysis, judgment, communication
Real World: Westinghouse
Electric Cash and cash equivalents
Real World: Weis Markets
Mark-to-market adjustments
Analysis
2, 3
Analysis
Analysis, communication
1, 4
6
Analysis
5, 7
Analysis, judgment, communication
Analysis, communication
7
Analysis
Skills
Uncollectible accounts - balance
sheet approach
Protecting liquid assets
Analyzing accounts receivable
Real World: Apple Computer
Reporting financial assets
Real World: Microsoft
Corporation Marketable
securities
Estimating uncollectible accounts
You as a student
© The McGraw-Hill Companies, Inc., 2010
Overview
Learning
Objective
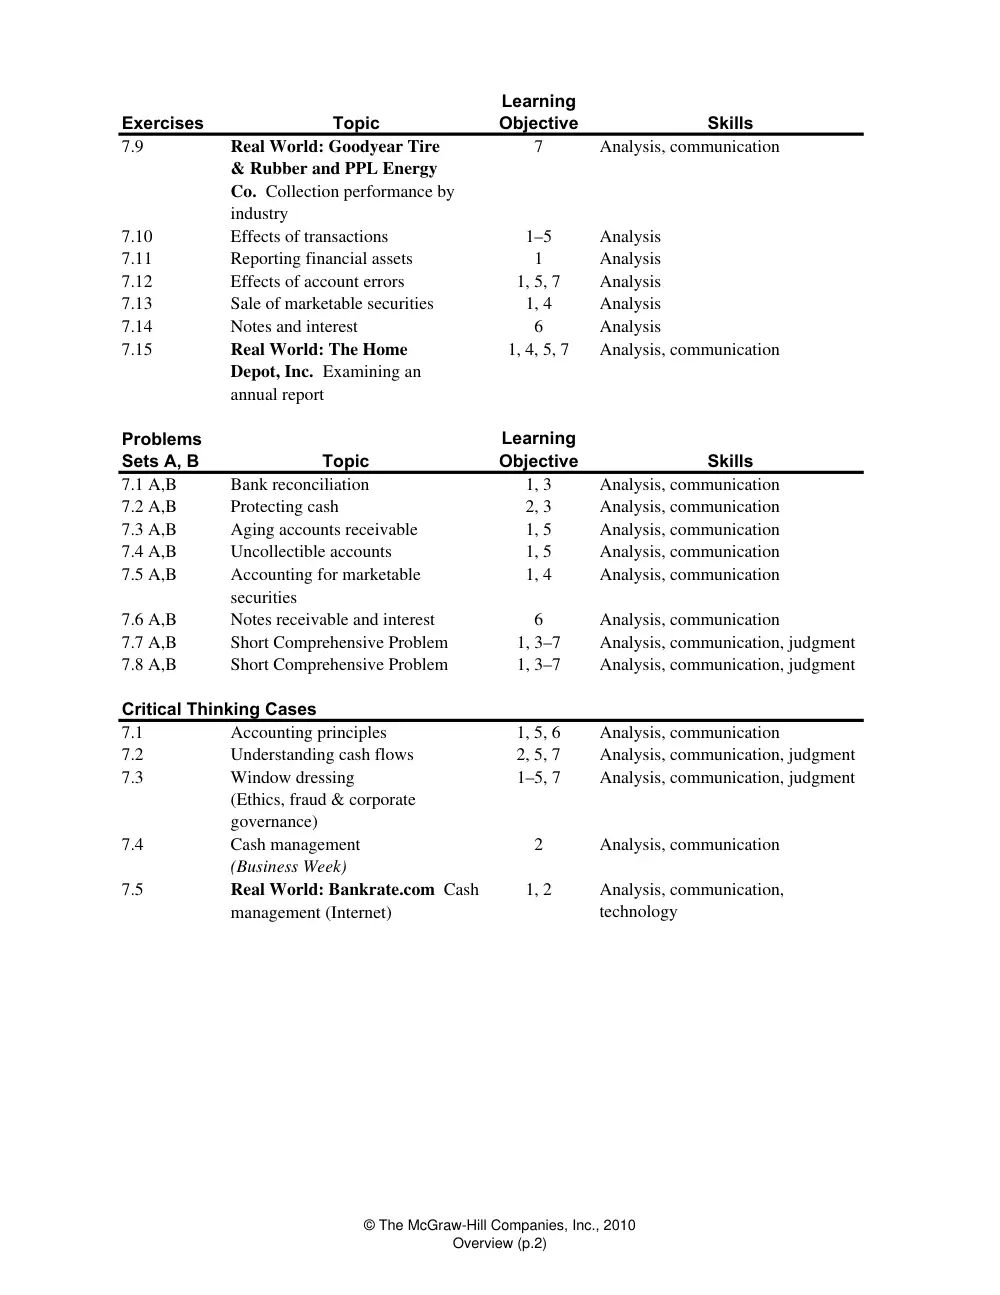
7.9
7
7.10
Effects of transactions
1–5
7.11
Reporting financial assets
1
Analysis
7.12
Effects of account errors
1, 5, 7
7.13
Sale of marketable securities
1, 4
7.14
Notes and interest
6
7.15
1, 4, 5, 7
Learning
Topic
Objective
7.1 A,B
1, 3
7.2 A,B
2, 3
7.3 A,B
1, 5
7.4 A,B
1, 5
7.5 A,B
1, 4
7.6 A,B
Notes receivable and interest
6
7.7 A,B
Short Comprehensive Problem
1, 3–7
7.8 A,B
Short Comprehensive Problem
1, 3–7
7.1
1, 5, 6
7.2
2, 5, 7
7.3
1–5, 7
7.4
2
7.5
1, 2
Analysis
Analysis
Analysis, communication
Real World: Goodyear Tire
& Rubber and PPL Energy
Co. Collection performance by
industry
(Ethics, fraud & corporate
governance)
Accounting for marketable
securities
Bank reconciliation
Protecting cash
Aging accounts receivable
Real World: The Home
Depot, Inc. Examining an
annual report
Window dressing
Exercises
Topic
Skills
Analysis, communication
Analysis
Analysis
Problems
Critical Thinking Cases
Cash management
Analysis, communication
Analysis, communication, judgment
(Business Week)
Real World: Bankrate.com Cash
management (Internet)
Analysis, communication,
technology
Analysis, communication, judgment
Analysis, communication
Analysis, communication, judgment
Analysis, communication
Analysis, communication, judgment
Analysis, communication
Analysis, communication
Analysis, communication
Analysis, communication
Sets A, B
Skills
Analysis, communication
Accounting principles
Uncollectible accounts
Understanding cash flows
© The McGraw-Hill Companies, Inc., 2010
Overview (p.2)
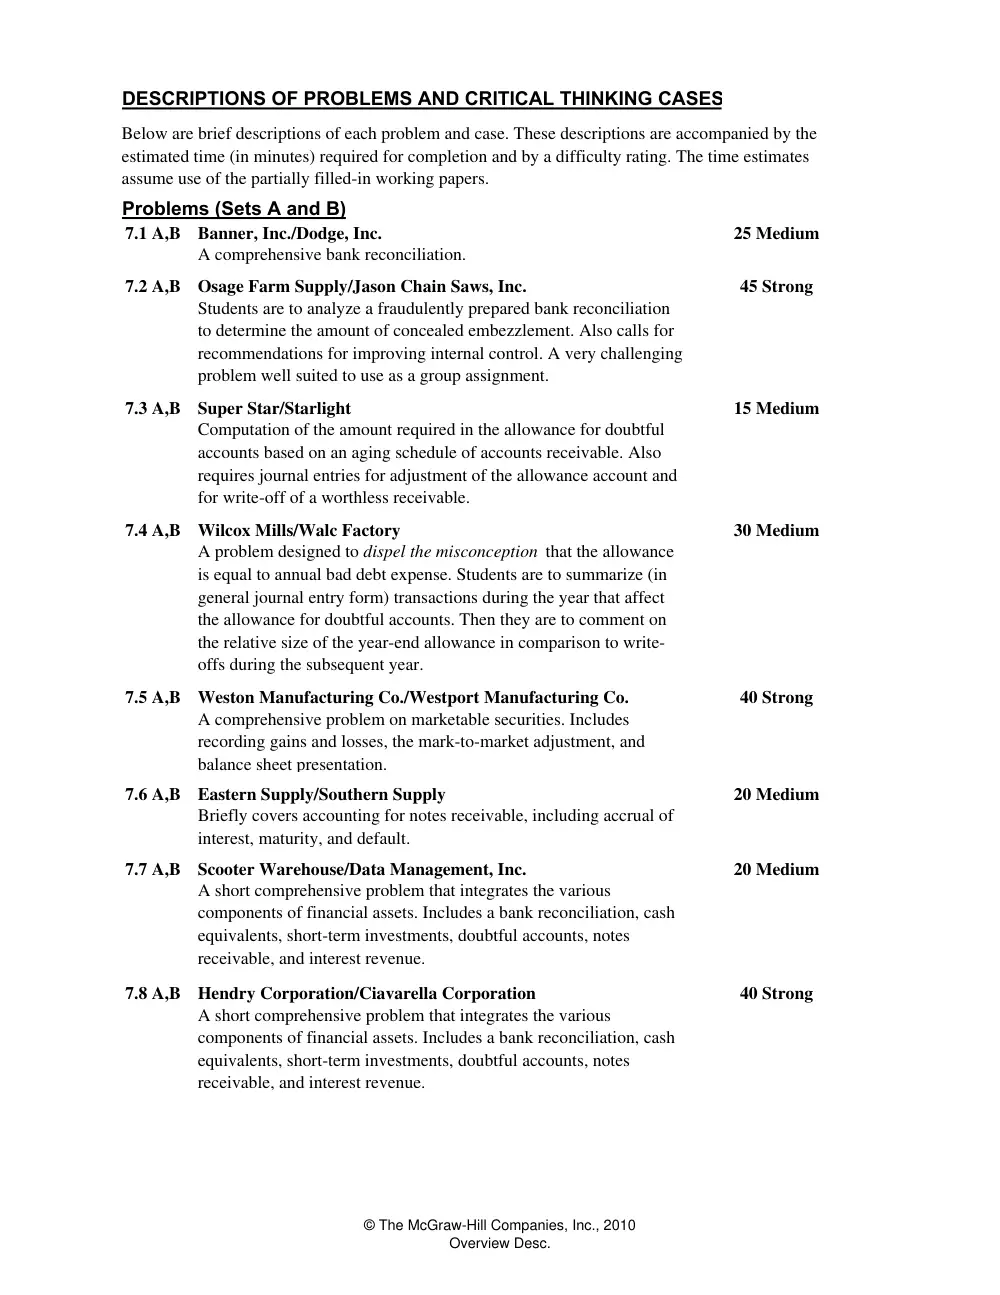
DESCRIPTIONS OF PROBLEMS AND CRITICAL THINKING CASES
Problems (Sets A and B)
7.1 A,B
25 Medium
7.2 A,B
45 Strong
7.3 A,B
15 Medium
7.4 A,B
30 Medium
7.5 A,B
40 Strong
7.6 A,B
20 Medium
7.7 A,B
20 Medium
7.8 A,B
40 Strong
Computation of the amount required in the allowance for doubtful
accounts based on an aging schedule of accounts receivable. Also
requires journal entries for adjustment of the allowance account and
for write-off of a worthless receivable.
Wilcox Mills/Walc Factory
A short comprehensive problem that integrates the various
components of financial assets. Includes a bank reconciliation, cash
equivalents, short-term investments, doubtful accounts, notes
receivable, and interest revenue.
Briefly covers accounting for notes receivable, including accrual of
interest, maturity, and default.
Scooter Warehouse/Data Management, Inc.
A problem designed to dispel the misconception that the allowance
is equal to annual bad debt expense. Students are to summarize (in
general journal entry form) transactions during the year that affect
the allowance for doubtful accounts. Then they are to comment on
the relative size of the year-end allowance in comparison to write-
offs during the subsequent year.
Weston Manufacturing Co./Westport Manufacturing Co.
A comprehensive problem on marketable securities. Includes
recording gains and losses, the mark-to-market adjustment, and
balance sheet presentation.
Eastern Supply/Southern Supply
Hendry Corporation/Ciavarella Corporation
A short comprehensive problem that integrates the various
components of financial assets. Includes a bank reconciliation, cash
equivalents, short-term investments, doubtful accounts, notes
receivable, and interest revenue.
Super Star/Starlight
Below are brief descriptions of each problem and case. These descriptions are accompanied by the
estimated time (in minutes) required for completion and by a difficulty rating. The time estimates
assume use of the partially filled-in working papers.
Banner, Inc./Dodge, Inc.
A comprehensive bank reconciliation.
Osage Farm Supply/Jason Chain Saws, Inc.
Students are to analyze a fraudulently prepared bank reconciliation
to determine the amount of concealed embezzlement. Also calls for
recommendations for improving internal control. A very challenging
problem well suited to use as a group assignment.
© The McGraw-Hill Companies, Inc., 2010
Overview Desc.
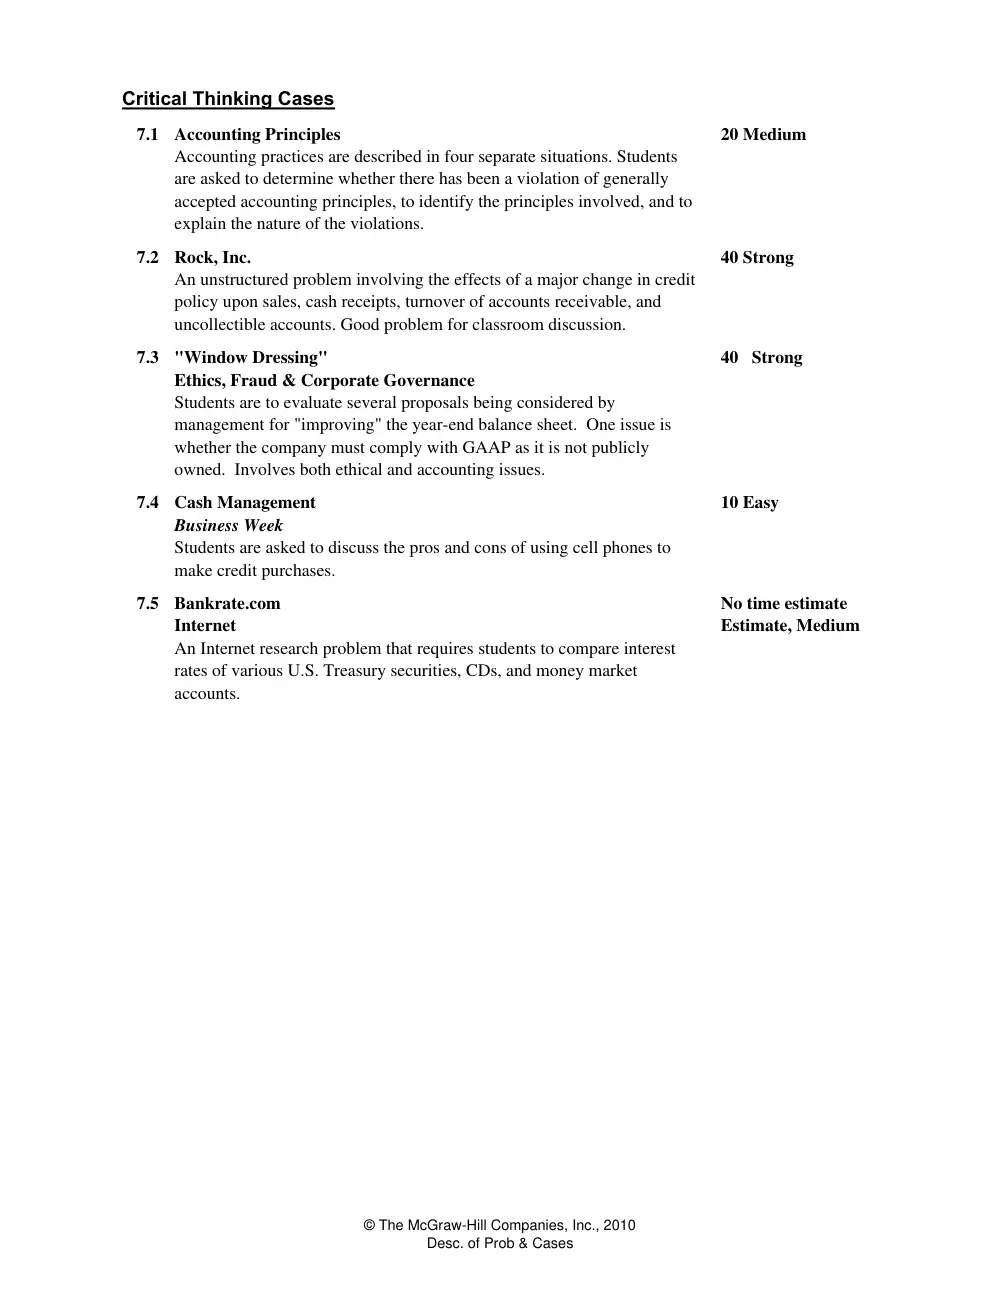
Critical Thinking Cases
Accounting Principles
Rock, Inc.
"Window Dressing"
Ethics, Fraud & Corporate Governance
Cash Management
Business Week
Bankrate.com
No time estimate
Internet
7.2
7.1
An Internet research problem that requires students to compare interest
rates of various U.S. Treasury securities, CDs, and money market
accounts.
10 Easy
20 Medium
Accounting practices are described in four separate situations. Students
are asked to determine whether there has been a violation of generally
accepted accounting principles, to identify the principles involved, and to
explain the nature of the violations.
40 Strong
40 Strong
Estimate, Medium
An unstructured problem involving the effects of a major change in credit
policy upon sales, cash receipts, turnover of accounts receivable, and
uncollectible accounts. Good problem for classroom discussion.
7.3
7.4
Students are to evaluate several proposals being considered by
management for "improving" the year-end balance sheet. One issue is
whether the company must comply with GAAP as it is not publicly
owned. Involves both ethical and accounting issues.
7.5
Students are asked to discuss the pros and cons of using cell phones to
make credit purchases.
© The McGraw-Hill Companies, Inc., 2010
Desc. of Prob & Cases
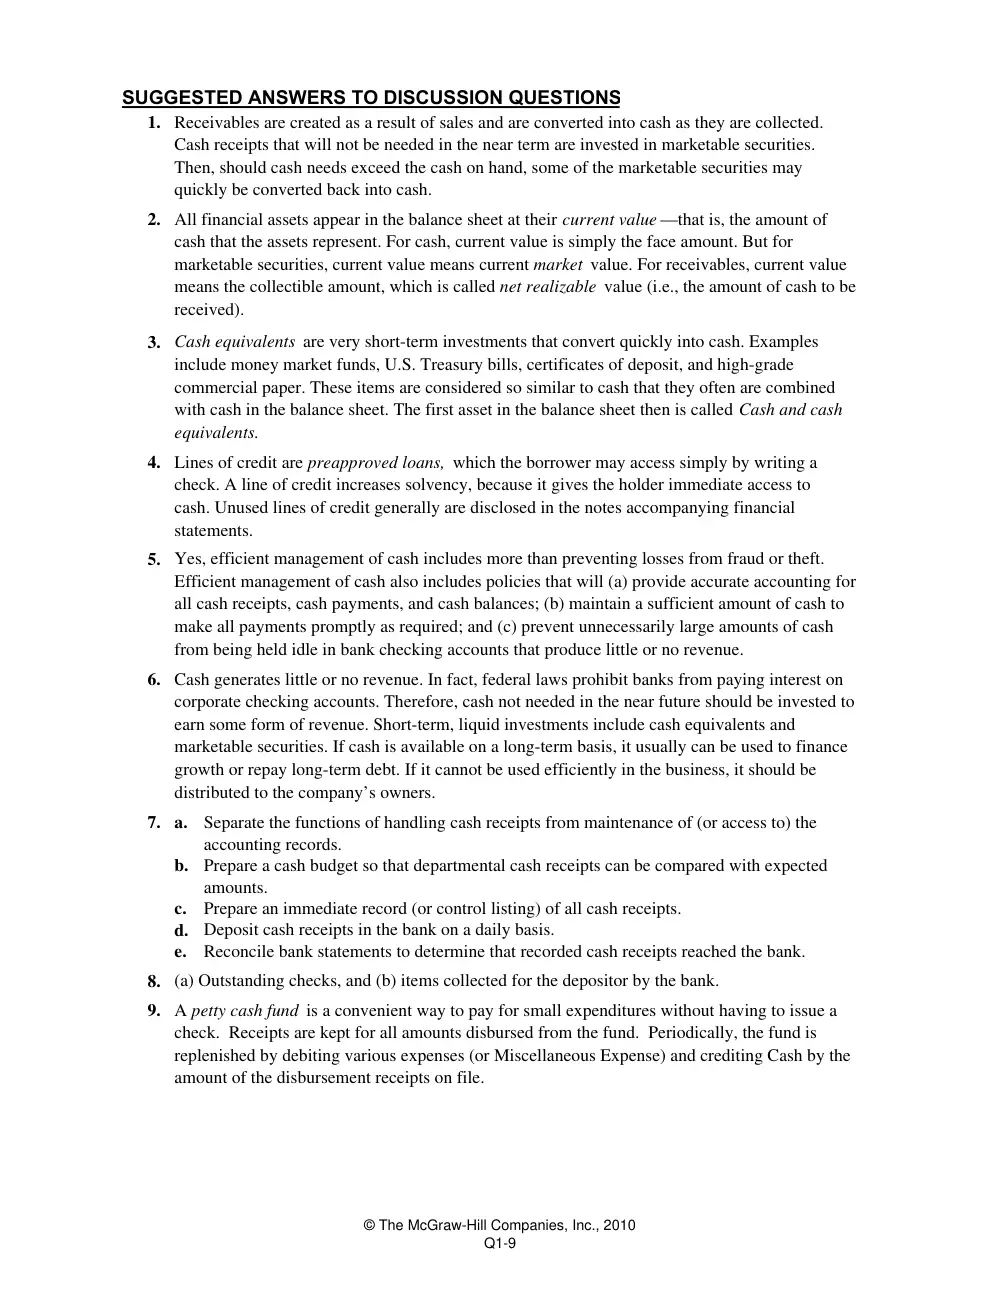
SUGGESTED ANSWERS TO DISCUSSION QUESTIONS
1.
2.
3.
4.
5.
6.
7. a.
b.
c.
d.
e.
8.
9.
Deposit cash receipts in the bank on a daily basis.
Receivables are created as a result of sales and are converted into cash as they are collected.
Cash receipts that will not be needed in the near term are invested in marketable securities.
Then, should cash needs exceed the cash on hand, some of the marketable securities may
quickly be converted back into cash.
Cash equivalents are very short-term investments that convert quickly into cash. Examples
include money market funds, U.S. Treasury bills, certificates of deposit, and high-grade
commercial paper. These items are considered so similar to cash that they often are combined
with cash in the balance sheet. The first asset in the balance sheet then is called Cash and cash
equivalents.
Lines of credit are preapproved loans, which the borrower may access simply by writing a
check. A line of credit increases solvency, because it gives the holder immediate access to
cash. Unused lines of credit generally are disclosed in the notes accompanying financial
statements.
All financial assets appear in the balance sheet at their current value —that is, the amount of
cash that the assets represent. For cash, current value is simply the face amount. But for
marketable securities, current value means current market value. For receivables, current value
means the collectible amount, which is called net realizable value (i.e., the amount of cash to be
received).
Reconcile bank statements to determine that recorded cash receipts reached the bank.
Yes, efficient management of cash includes more than preventing losses from fraud or theft.
Efficient management of cash also includes policies that will (a) provide accurate accounting for
all cash receipts, cash payments, and cash balances; (b) maintain a sufficient amount of cash to
make all payments promptly as required; and (c) prevent unnecessarily large amounts of cash
from being held idle in bank checking accounts that produce little or no revenue.
Cash generates little or no revenue. In fact, federal laws prohibit banks from paying interest on
corporate checking accounts. Therefore, cash not needed in the near future should be invested to
earn some form of revenue. Short-term, liquid investments include cash equivalents and
marketable securities. If cash is available on a long-term basis, it usually can be used to finance
growth or repay long-term debt. If it cannot be used efficiently in the business, it should be
distributed to the company’s owners.
(a) Outstanding checks, and (b) items collected for the depositor by the bank.
A petty cash fund is a convenient way to pay for small expenditures without having to issue a
check. Receipts are kept for all amounts disbursed from the fund. Periodically, the fund is
replenished by debiting various expenses (or Miscellaneous Expense) and crediting Cash by the
amount of the disbursement receipts on file.
Separate the functions of handling cash receipts from maintenance of (or access to) the
accounting records.
Prepare a cash budget so that departmental cash receipts can be compared with expected
amounts.
Prepare an immediate record (or control listing) of all cash receipts.
© The McGraw-Hill Companies, Inc., 2010
Q1-9
10.
11.
12.
13.
14.
15.
16.
Mark-to-market is the process of adjusting the balance sheet valuation of investments in
marketable securities to current market value at each balance sheet date. This adjustment
affects only the balance sheet. The offsetting entry is to an owners’ equity account sometimes
entitled Unrealized Holding Gains (or Losses) on Investments.
The account Unrealized Holding Gains (or Losses) on Investments represents the difference
between the cost of marketable securities owned and their current market value. In essence,
this is the amount of gain or loss that would be realized if the securities were sold today. The
amount of unrealized gain or loss appears in the owners’ equity section of the balance sheet.
An unrealized gain increases total owners’ equity, and an unrealized loss decreases owners’
equity.
Uncollectible accounts expense is associated with the revenue resulting from making credit
sales to customers who do not pay their bills. The matching principle states that revenue should
be offset with all of the expenses incurred in producing that revenue. Therefore, the expense of
an uncollectible account should be recognized in the same accounting period as the credit
sale.
Marketable securities are less liquid than cash equivalents, primarily due to management’s
intent with regard to converting them to cash. They are usually presented separate from cash
and cash equivalents in the balance sheet.
For each type of security owned the marketable securities subsidiary ledger shows the total
cost, number of units (shares or bonds) owned, and cost per unit. The record assists the
investor in keeping track of the securities owned, of interest and dividends received, and in
computing the gain or loss resulting from sales of specific securities.
The direct write-off method does not require estimates of uncollectible accounts expense or
use a valuation allowance. When individual accounts receivable are determined to be
uncollectible, they are written off by debiting Uncollectible Accounts Expense. This method
(in contrast to the allowance method ) does not attempt to assign the expense from
uncollectible accounts to the accounting period in which the uncollectible receivables
originated, and therefore does not match related revenue and expenses.
At the time of a credit sale, we do not know that the resulting account receivable will prove to
be uncollectible. This determination usually is made only after months of unsuccessful
collection effort. Therefore, if the expense of uncollectible accounts is to be recognized in the
same period as the related sales revenue, this expense must be estimated.
The balance sheet approach to estimating uncollectible accounts means aging the accounts
receivable on hand at year-end and estimating the uncollectible portion of these receivables.
The Allowance for Doubtful Accounts is then adjusted by the amount necessary to make it
equal to the estimated uncollectible amount contained in the receivables.
The income statement approach to estimating uncollectible accounts means determining the
average percentage relationship of uncollectible accounts expense to the year’s net sales on
credit. Ordinarily, no consideration is given to the existing balance in the allowance account. If
the percentage used is valid, the allowance account will be subject to fluctuations in the short
run but will neither build up to unreasonable size nor become exhausted.
© The McGraw-Hill Companies, Inc., 2010
Q10-16
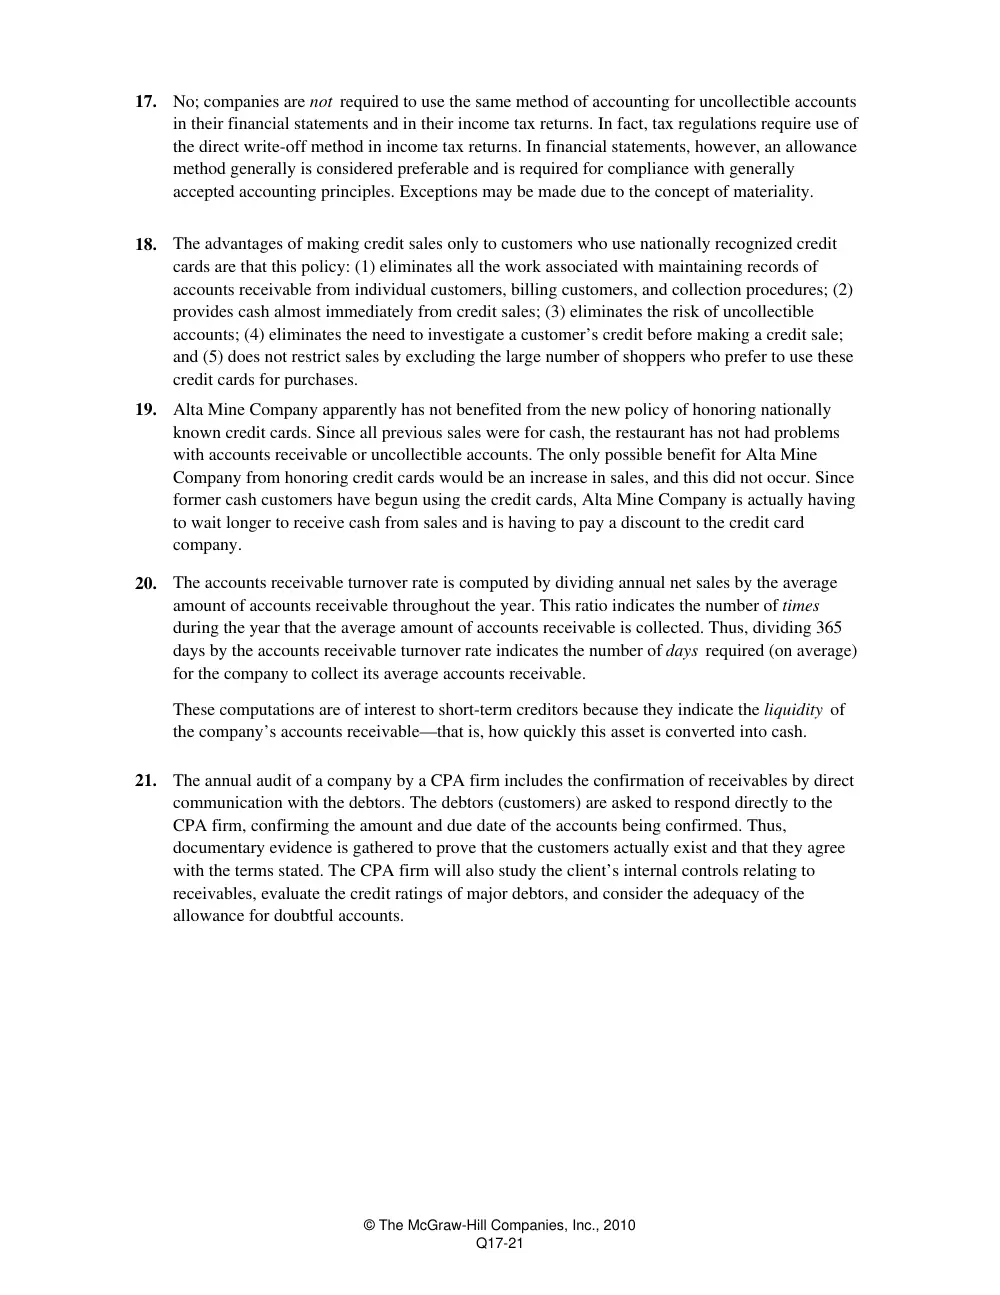
17.
18.
19.
20.
21.
The advantages of making credit sales only to customers who use nationally recognized credit
cards are that this policy: (1) eliminates all the work associated with maintaining records of
accounts receivable from individual customers, billing customers, and collection procedures; (2)
provides cash almost immediately from credit sales; (3) eliminates the risk of uncollectible
accounts; (4) eliminates the need to investigate a customer’s credit before making a credit sale;
and (5) does not restrict sales by excluding the large number of shoppers who prefer to use these
credit cards for purchases.
No; companies are not required to use the same method of accounting for uncollectible accounts
in their financial statements and in their income tax returns. In fact, tax regulations require use of
the direct write-off method in income tax returns. In financial statements, however, an allowance
method generally is considered preferable and is required for compliance with generally
accepted accounting principles. Exceptions may be made due to the concept of materiality.
These computations are of interest to short-term creditors because they indicate the liquidity of
the company’s accounts receivable—that is, how quickly this asset is converted into cash.
The annual audit of a company by a CPA firm includes the confirmation of receivables by direct
communication with the debtors. The debtors (customers) are asked to respond directly to the
CPA firm, confirming the amount and due date of the accounts being confirmed. Thus,
documentary evidence is gathered to prove that the customers actually exist and that they agree
with the terms stated. The CPA firm will also study the client’s internal controls relating to
receivables, evaluate the credit ratings of major debtors, and consider the adequacy of the
allowance for doubtful accounts.
Alta Mine Company apparently has not benefited from the new policy of honoring nationally
known credit cards. Since all previous sales were for cash, the restaurant has not had problems
with accounts receivable or uncollectible accounts. The only possible benefit for Alta Mine
Company from honoring credit cards would be an increase in sales, and this did not occur. Since
former cash customers have begun using the credit cards, Alta Mine Company is actually having
to wait longer to receive cash from sales and is having to pay a discount to the credit card
company.
The accounts receivable turnover rate is computed by dividing annual net sales by the average
amount of accounts receivable throughout the year. This ratio indicates the number of times
during the year that the average amount of accounts receivable is collected. Thus, dividing 365
days by the accounts receivable turnover rate indicates the number of days required (on average)
for the company to collect its average accounts receivable.
© The McGraw-Hill Companies, Inc., 2010
Q17-21
22.
a.
b.
c.
d.
23.
24.
a.
b.
Writing off an account receivable against the allowance does not affect income or cash
flows.
The adjusting entry to increase the balance sheet valuation of marketable securities affects
only the balance sheet. No cash flows are involved, and the unrealized gain appears in the
stockholders’ equity section of the balance sheet, not in the income statement.
In a multiple-step income statement, the loss from a sale of marketable securities reduces net
income and is classified as a nonoperating item. In a statement of cash flows, the entire
proceeds from the sale are shown as a cash receipt from investing activities.
The adjusting entry to create or increase the allowance for doubtful accounts involves the
recognition of an expense. This expense (uncollectible accounts expense) appears as a selling
expense in a multiple-step income statement. But this adjusting entry, like all adjusting
entries, involves no cash receipts or cash payments. Therefore, it has no effect upon cash
flows.
Changes in the market value of securities owned do not affect the investor's taxable income. For
income tax purposes, gains on investments are recognized only when the investments are sold .
Maturity value = $10,900 (interest = $10,000 x .09 x 1 = $900.)
Maturity date = July 1, 2010 (365 days later, but the counting starts on July 2).
Maturity value = $20,400 (interest = $20,000 x .08 x 90/360 = $400.)
Maturity date = June 9, (20 days in March, 30 days in April, 31 days in May,
leaves 9 days in June).
© The McGraw-Hill Companies, Inc., 2010
Q22-24
B.Ex.7.1 a.
b.
c.
B.Ex.7.2 a.
$ 21,749
(200)
(3,000)
(549)
$ 18,000
$ 22,000
5,000
(9,000)
$ 18,000
b.
$ 18,000
60,000
$ 78,000
c. Bank Service Charges…………………………………
200
Accounts Receivable……………………………………
3,000
Office Supplies…………………………………………
549
Cash……………...…………………………
3,749
NSF check from Susque Company………………………….
Adjusted cash balance, December 31 (from part a.)…………..
Cash equivalents: Money market account…………………….
Cash and cash equivalents, December 31………………………..
Cash balance per bank statement…………………………………
Add: Deposits in transit…………………………………………….
Less: Outstanding checks………………………………………….
Adjusted cash balance, December 31……………………………..
SOLUTIONS TO BRIEF EXERCISES
Cash equivalents are usually short-term debt securities (e.g., U.S. Treasury bills,
high-grade commercial paper, etc.). This appears to be true for Westinghouse
Electric, as the footnote specifically mentions that all cash equivalents have a
maturity date of three months or less (equity securities have no maturity date).
The statement referring to the company's limited credit exposure to any one
financial institution means simply that Westinghouse has not put "all of its eggs in
any one basket." In short, it has spread any risk associated with cash equivalents
across numerous financial institutions that issue these short-term securities.
To record bank service charges, to reclassify a NSF check as an
account receivable, and to correct an error in the recording of office
supplies.
Error corrections, office supplies…………………………..
Adjusted cash balance, December 31……………………………….
Note: Stocks are never considered cash equivalents and commercial
paper can be considered cash equivalents only when durations are 90
days or less.
The $42 million designated as restricted cash and cash equivalents is not available
to meet the normal operating needs of the company. The amount may be reserved
for a specific purpose or may represent a compensating balance as a condition of a
bank loan or some other credit agreement.
Cash balance per general ledger………………………………….
Less: Bank service charge………………….……………………..
© The McGraw-Hill Companies, Inc., 2010
BE7.1,2
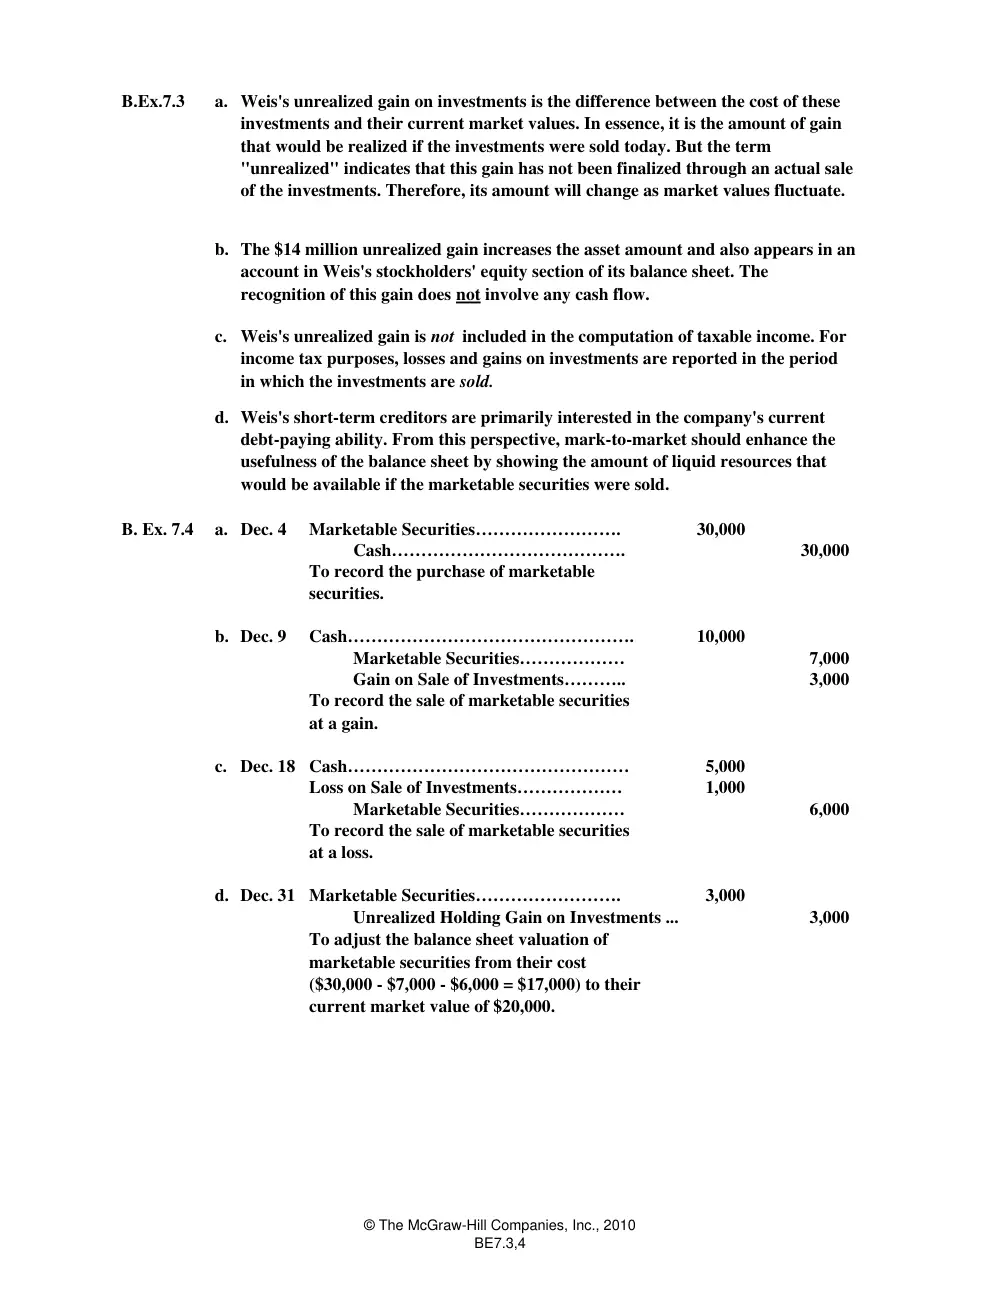
B.Ex.7.3
a.
b.
B. Ex. 7.4
a. Dec. 4
Marketable Securities…………………….
30,000
Cash………………………………….
30,000
b. Dec. 9
Cash………………………………………….
10,000
Marketable Securities………………
7,000
Gain on Sale of Investments………..
3,000
c. Dec. 18 Cash…………………………………………
5,000
Loss on Sale of Investments………………
1,000
Marketable Securities………………
6,000
d. Dec. 31 Marketable Securities…………………….
3,000
Unrealized Holding Gain on Investments ...
3,000
To adjust the balance sheet valuation of
marketable securities from their cost
($30,000 - $7,000 - $6,000 = $17,000) to their
current market value of $20,000.
Weis's unrealized gain is not included in the computation of taxable income. For
income tax purposes, losses and gains on investments are reported in the period
in which the investments are sold.
The $14 million unrealized gain increases the asset amount and also appears in an
account in Weis's stockholders' equity section of its balance sheet. The
recognition of this gain does not involve any cash flow.
Weis's unrealized gain on investments is the difference between the cost of these
investments and their current market values. In essence, it is the amount of gain
that would be realized if the investments were sold today. But the term
"unrealized" indicates that this gain has not been finalized through an actual sale
of the investments. Therefore, its amount will change as market values fluctuate.
To record the sale of marketable securities
at a loss.
c.
d. Weis's short-term creditors are primarily interested in the company's current
debt-paying ability. From this perspective, mark-to-market should enhance the
usefulness of the balance sheet by showing the amount of liquid resources that
would be available if the marketable securities were sold.
To record the sale of marketable securities
at a gain.
To record the purchase of marketable
securities.
© The McGraw-Hill Companies, Inc., 2010
BE7.3,4
B.Ex.7.5 a. Uncollectible Accounts Expense………………….
12,000
Allowance for Doubtful Accounts ..........
12,000
b. Uncollectible Accounts Expense………………….
15,000
Allowance for Doubtful Accounts .........
15,000
B.Ex.7.6
$ 6,000,000
$ 5,000,000
9,000,000
(100,000)
(7,835,000)
$ 6,065,000
$ 75,000
90,000
(100,000)
$ 65,000
Ending net realizable value ($6,065,000 - $65,000)…………….
6,000,000
$
Allowance for Doubtful Accounts (ending balance)…………….
Accounts Receivable (beginning balance)……………………….
Add: Credit sales for the period…………………………………….
Less: Accounts receivable written-off……………………………..
Accounts receivable collected……………………………
Accounts Receivable (ending balance)…………………………..
Less: Accounts receivable written-off……………………………
Past due 61-90 days 12,000 x 40% = 4,800
Required allowance for doubtful accounts balance $13,400 credit
Past due over 90 days 2,000 x 90% = 1,800
* $5,000,000 - $4,925,000 = $75,000 beginning balance in the
Allowance for Doubtful Accounts.
Past due 1-30 days 40,000 x 4% = 1,600
Allowance for Doubtful Accounts (beginning balance*)……….
Add: Uncollectible accounts expense ($9 million x 1%)………
To record uncollectible accounts expense ($13,400 - $1,400 credit
balance = $12,000).
Ending net realizable value of accounts receivable…………….
Computations:
To record uncollectible accounts expense ($13,400 + $1,600 debit
balance = $15,000).
Computations:
Current $60,000 x 2% = $ 1,200
Past due 31-60 days 25,000 x 16% = 4,000
© The McGraw-Hill Companies, Inc., 2010
BE7.5,6
B.Ex. 7.7
a.
b.
c.
B.Ex. 7.8
a.
Sept.
1
22,000
Accounts Receivable …………………
22,000
b.
Dec.
31 Interest Receivable ………………………………
880
Interest Revenue ………………………
880
c.
May
31
23,980
Notes Receivable ………………………
22,000
Interest Receivable ……………………
880
Interest Revenue ………………………
1,100
Accounts receivable turnover rate (net sales/average accounts
receivable):
To record receipt of a 9-month, 12% note
receivable in settlement of the account
receivable of Herbal Innovations.
Both of these companies have very liquid accounts receivable – that is, their
receivables convert quickly into cash. However, the accounts receivable of
Anheuser-Busch are even more liquid than those of Molson Coors. Anheuser-
Busch, on average, collects on its outstanding accounts 12 days faster than
Anheuser-Busch (31 days - 19 days).
Notes Receivable …………………………………
Cash ………………………………………………
Molson Coors : $8,320/$720 = 11.6 times
Anheuser-Busch : $17,400/$900 = 19.3 times
Accounts receivable days outstanding (365 days/accounts
receivable turnover rate):
To recognize 4 months’ interest on note
Molson Coors : 365 days/11.6 times = 31 days
Anheuser-Busch : 365 days/19.3 times = 19 days
from Herbal Innovations ($22,000 x 12% x
4/12 = $880).
To record collection of principal and interest
on 12% note from Herbal Innovations.
Interest revenue is computed as $22,000 x
12% x 5/12.
© The McGraw-Hill Companies, Inc., 2010
BE7.7,8
B.Ex. 7.9
B.Ex. 7.10
a.
b.
$1,500,000 ÷ $125,000 = 12 times
365 days ÷ 12 times turnover rate = 30.4 days
All sales by long distance carriers, such as Sprint Nextel Corporation, are made on
account. In contrast, the majority of sales made by grocery chains, such as Weis
Markets, are cash sales . Thus, one would expect accounts receivable, expressed as a
percentage of net sales, to be larger for Sprint Nextel than it is for Weis (10.5%
versus 2.1%).
Sales made on account by grocery chains are often to institutional customers (e.g.,
restaurants, college cafeterias, Boy Scout Camps, etc.). Long distance carriers, on
the other hand, generate a large volume of credit sales from individuals. Generally
speaking, individuals pose a greater credit risk than institutional customers.
Therefore, it is not surprising that the allowance for doubtful accounts, expressed as
a percentage of net sales, is nearly 28 times greater for Sprint Nextel than it is for
Weis (1.1% versus 0.04%).
© The McGraw-Hill Companies, Inc., 2010
BE7.9
a.
Balance per bank statement at September 30 ………………………..
3,400
$
Add: Deposit made by your parents on October 2 …………………..
2,400
5,800
$
Deduct outstanding checks:
#203 University tuition ………………………………………………..
1,500
#205 University bookstore ……………………………………………
350
#208 Rocco’s pizza …………………………………………………….
25
#210 Stereo purchase ………………………………………………….
425
#211 October apartment rent ………………………………………….
500
Adjusted cash balance ………………………………………………….
3,000
$
Balance per your checkbook (including $2,400.00 deposit)
3,001
$
Add: Interest earned in September
4
3,005
$
Deduct bank’s service charge
5
Adjusted cash balance (as above)
3,000
$
Ex. 7.2
a.
b.
c.
d.
e.
Cash equivalents are safe and highly liquid investments that convert to cash within
90 days of acquisition. These investments often include certificates of deposits (CDs),
U.S. Treasury bills, and money market accounts.
Apple Computer’s accounts receivable, in total, amount to $1.637 billion. Of this
amount, however, the company estimates that $44 million will not be collected. Thus,
the company reports receivables at a net realizable value of $1.593 billion in its
balance sheet ($1.637 billion - $44 million).
Financial assets are cash and other assets that will convert directly into known
amounts of cash.
Cash and cash equivalents are reported in the balance sheet at face value.
Marketable securities are reported at market value, whereas accounts receivable are
reported at net realizable value. The common goal is to report these assets at their
current value —that is, the amount of cash that each asset represents.
Companies hold marketable securities because these assets, unlike corporate
checking accounts, have the potential to generate income through interest and
capital appreciation. The reason companies hold accounts receivable is different.
Most companies must be willing to make sales on account (as opposed to only cash
sales) in order to maximize their income potential. Thus, they must be willing to hold
some of their resources in the form of accounts receivable.
SOLUTIONS TO EXERCISES
As shown above, your correct current checkbook balance is $3,000. Prior to
adjusting your records, neither your checkbook nor your bank statement report this
balance because neither contains complete information about your account activity
during the month.
Ex. 7.1
© The McGraw-Hill Companies, Inc., 2010
E7.1,2
Ex. 7.3
a.
b.
Employee theft is never ethical, even if it is committed to pay for medical bills. It
is also unethical for employees to “borrow” funds from their employers without
formal permission (even if one has the “intent” of eventually paying back the full
amount).
Note to instructor: The White Electric Supply example is one of several “real world” cases
documented in a video entitled, Red Flags: What Every Manager Should Know About Crime. The
video is produced by The Institute for Financial Crime Prevention, 716 West Avenue, Austin, TX
78701.
There were several controls lacking at White Electric Supply which made it
possible for the bookkeeper to embezzle nearly $416,000 in less than five years.
First, not only did the bookkeeper prepare the company’s bank reconciliation
each month, but she also had complete control over all cash receipts and
disbursements. These duties must be segregated for adequate protection against
theft. Second, the company had no inventory control system in place. Thus, it
went undetected by management when the check register consistently showed
inventory purchase amounts in excess of actual inventory received. Finally,
because White Electric Supply was not a publicly owned corporation, an
independent audit was not required. As a result, management never considered
conducting an independent review of the company’s financial records and
control systems.
© The McGraw-Hill Companies, Inc., 2010
E7.3
Ex. 7.4
a.
b.
c.
(1)
(2)
(3)
(