
ACCT 215 Problems Solutions, Fall 2011
American University of Beirut · Management Accounting · 16 pages · with solution

Showing the first 10 of 16 pages. Download the PDF to see all of it.
More ACCT 215 files
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
Show the text of this problems
Chapter 08 Profit Planning
Chapter 08
Profit Planning
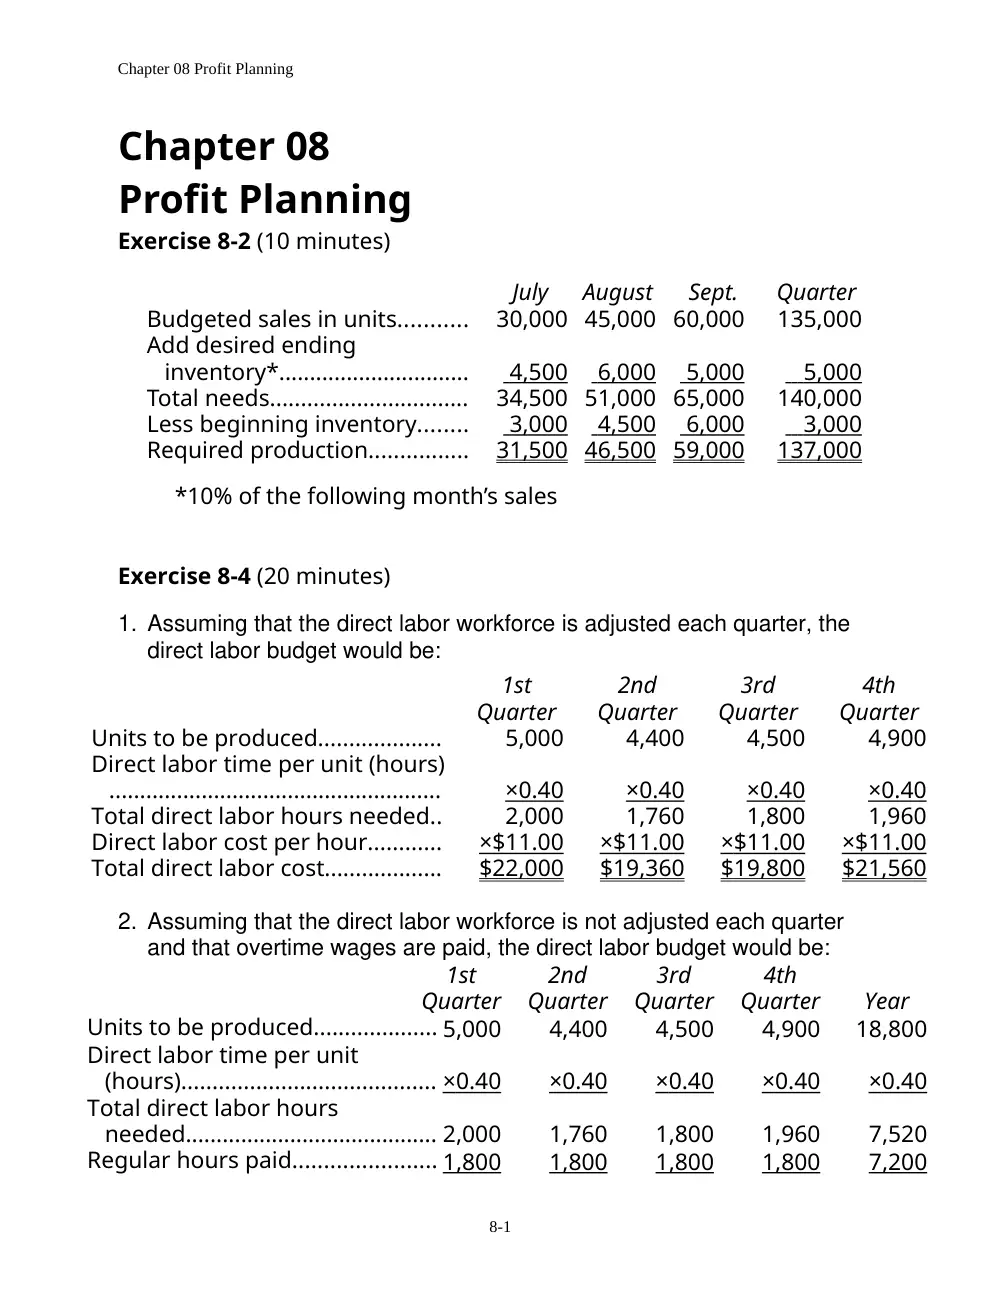
Exercise 8-2 (10 minutes)
July
August
Sept.
Quarter
Budgeted sales in units...........
30,000 45,000 60,000
135,000
Add desired ending
inventory*...............................
4,500
6,000
5,000
5,000
Total needs................................
34,500 51,000 65,000
140,000
Less beginning inventory........
3,000
4,500
6,000
3,000
Required production................
31,500 46,500 59,000
137,000
*10% of the following month’s sales
Exercise 8-4 (20 minutes)
1. Assuming that the direct labor workforce is adjusted each quarter, the
direct labor budget would be:
1st
Quarter
2nd
Quarter
3rd
Quarter
4th
Quarter
Units to be produced....................
5,000
4,400
4,500
4,900
Direct labor time per unit (hours)
......................................................
× 0.40
× 0.40
× 0.40
× 0.40
Total direct labor hours needed..
2,000
1,760
1,800
1,960
Direct labor cost per hour............
× $11.00
× $11.00
× $11.00
× $11.00
Total direct labor cost...................
$22,000
$19,360
$19,800
$21,560
2. Assuming that the direct labor workforce is not adjusted each quarter
and that overtime wages are paid, the direct labor budget would be:
1st
Quarter
2nd
Quarter
3rd
Quarter
4th
Quarter
Year
Units to be produced.................... 5,000
4,400
4,500
4,900
18,800
Direct labor time per unit
(hours)......................................... × 0.40
× 0.40
× 0.40
× 0.40
× 0.40
Total direct labor hours
needed......................................... 2,000
1,760
1,800
1,960
7,520
Regular hours paid....................... 1,800
1,800
1,800
1,800
7,200
8-1
Chapter 08 Profit Planning
Overtime hours paid..................... 200
0
0
160
360
Wages for regular hours
(@ $11.00 per hour)...................
$19,800
$19,800
$19,800
$19,800
$79,200
Overtime wages (@ $11.00
per hour × 1.5 hours)................. 3,300
0
0
2,640
5,940
Total direct labor cost...................
$23,100
$19,800
$19,800
$22,440
$85,140
8-2
Chapter 08 Profit Planning
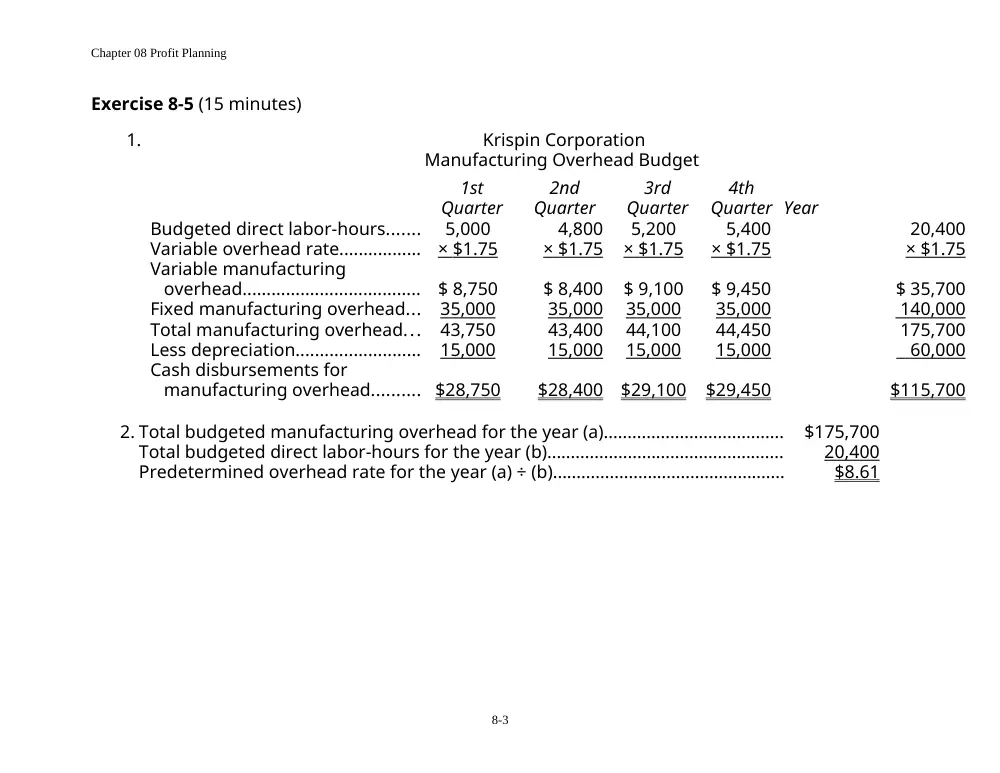
Exercise 8-5 (15 minutes)
1.
Krispin Corporation
Manufacturing Overhead Budget
1st
Quarter
2nd
Quarter
3rd
Quarter
4th
Quarter Year
Budgeted direct labor-hours.......
5,000
4,800
5,200
5,400
20,400
Variable overhead rate.................
× $1.75
× $1.75
× $1.75
× $1.75
× $1.75
Variable manufacturing
overhead.....................................
$ 8,750
$ 8,400
$ 9,100
$ 9,450
$ 35,700
Fixed manufacturing overhead...
35,000
35,000
35,000
35,000
140,000
Total manufacturing overhead...
43,750
43,400
44,100
44,450
175,700
Less depreciation..........................
15,000
15,000
15,000
15,000
60,000
Cash disbursements for
manufacturing overhead.......... $28,750
$28,400
$29,100
$29,450
$115,700
8-3
2. Total budgeted manufacturing overhead for the year (a)......................................
$175,700
Total budgeted direct labor-hours for the year (b)..................................................
20,400
Predetermined overhead rate for the year (a) ÷ (b).................................................
$8.61
Chapter 08 Profit Planning
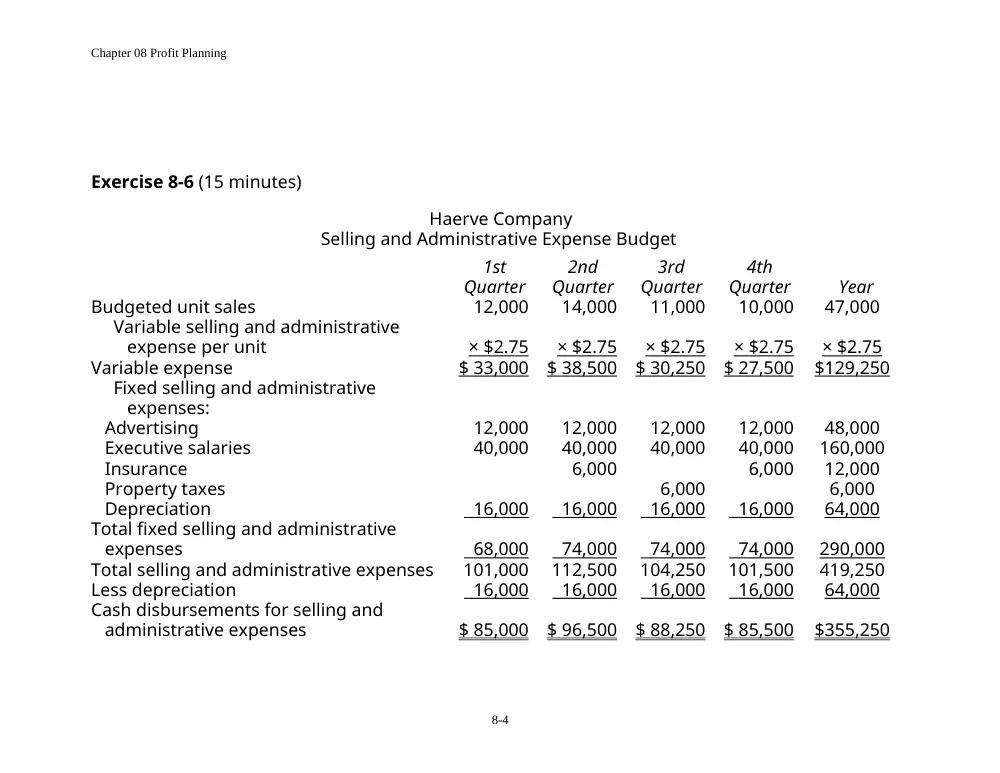
Exercise 8-6 (15 minutes)
Haerve Company
Selling and Administrative Expense Budget
1st
Quarter
2nd
Quarter
3rd
Quarter
4th
Quarter
Year
Budgeted unit sales
12,000
14,000
11,000
10,000
47,000
Variable selling and administrative
expense per unit
× $2.75
× $2.75
× $2.75
× $2.75
× $2.75
Variable expense
$ 33,000
$ 38,500
$ 30,250
$ 27,500
$129,250
Fixed selling and administrative
expenses:
Advertising
12,000
12,000
12,000
12,000
48,000
Executive salaries
40,000
40,000
40,000
40,000
160,000
Insurance
6,000
6,000
12,000
Property taxes
6,000
6,000
Depreciation
16,000
16,000
16,000
16,000
64,000
Total fixed selling and administrative
expenses
68,000
74,000
74,000
74,000
290,000
Total selling and administrative expenses
101,000
112,500
104,250
101,500
419,250
Less depreciation
16,000
16,000
16,000
16,000
64,000
Cash disbursements for selling and
administrative expenses
$ 85,000
$ 96,500
$ 88,250
$ 85,500
$355,250
8-4
Chapter 08 Profit Planning
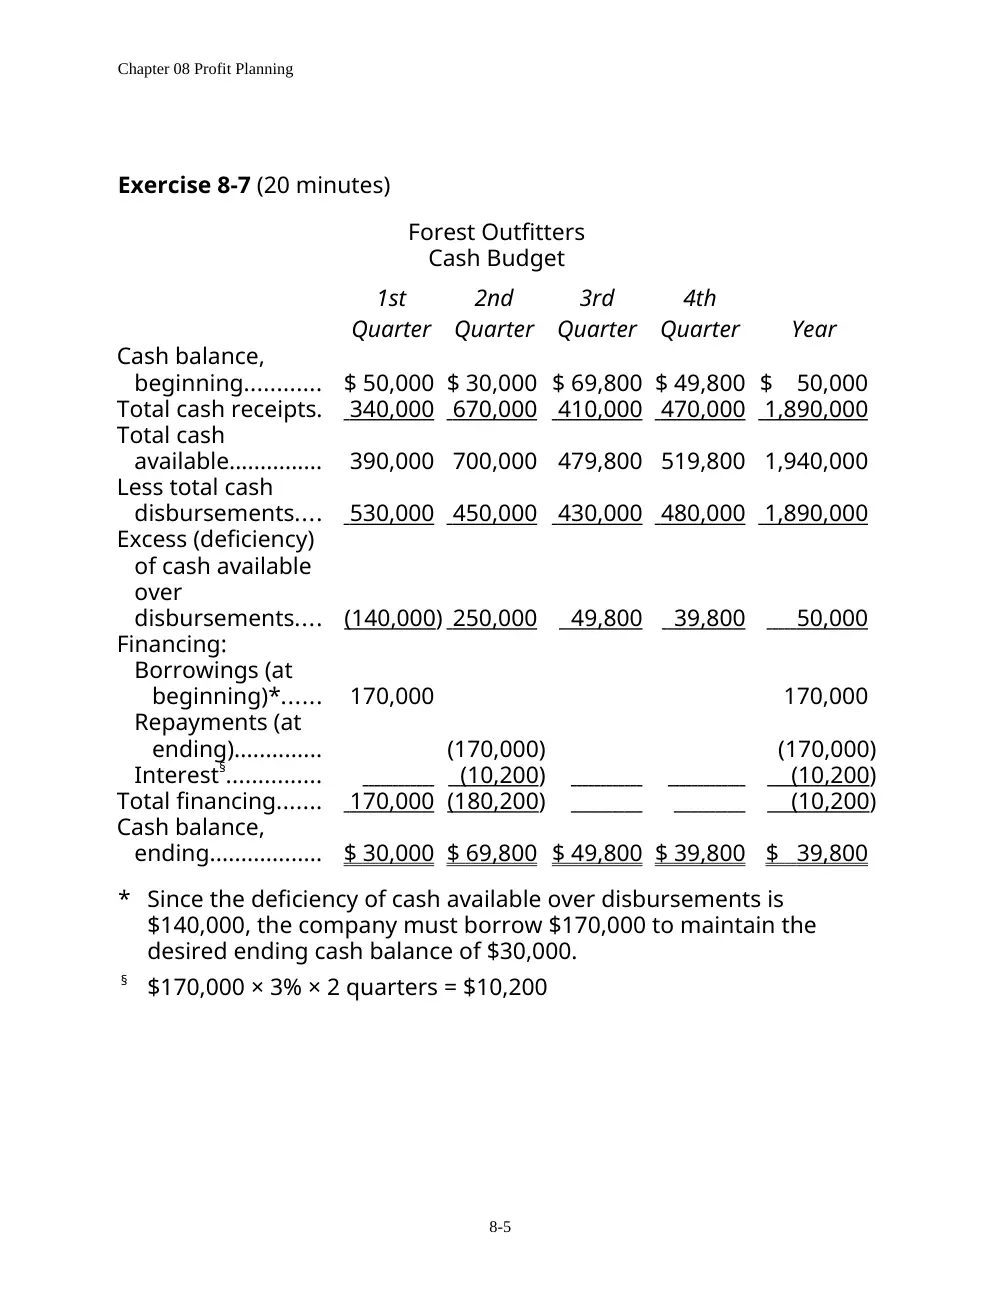
Exercise 8-7 (20 minutes)
Forest Outfitters
Cash Budget
1st
Quarter
2nd
Quarter
3rd
Quarter
4th
Quarter
Year
Cash balance,
beginning............
$ 50,000 $ 30,000 $ 69,800 $ 49,800 $ 50,000
Total cash receipts.
340,000
670,000
410,000
470,000
1,890,000
Total cash
available...............
390,000
700,000
479,800
519,800
1,940,000
Less total cash
disbursements....
530,000
450,000
430,000
480,000
1,890,000
Excess (deficiency)
of cash available
over
disbursements....
(140,000) 250,000
49,800
39,800
50,000
Financing:
Borrowings (at
beginning)*......
170,000
170,000
Repayments (at
ending)..............
(170,000)
(170,000)
Interest§...............
(10,200
)
(10,200
)
Total financing.......
170,000
(180,200)
(10,200
)
Cash balance,
ending..................
$ 30,000
$ 69,800
$ 49,800
$ 39,800
$ 39,800
* Since the deficiency of cash available over disbursements is
$140,000, the company must borrow $170,000 to maintain the
desired ending cash balance of $30,000.
§
$170,000 × 3% × 2 quarters = $10,200
8-5
Chapter 08 Profit Planning
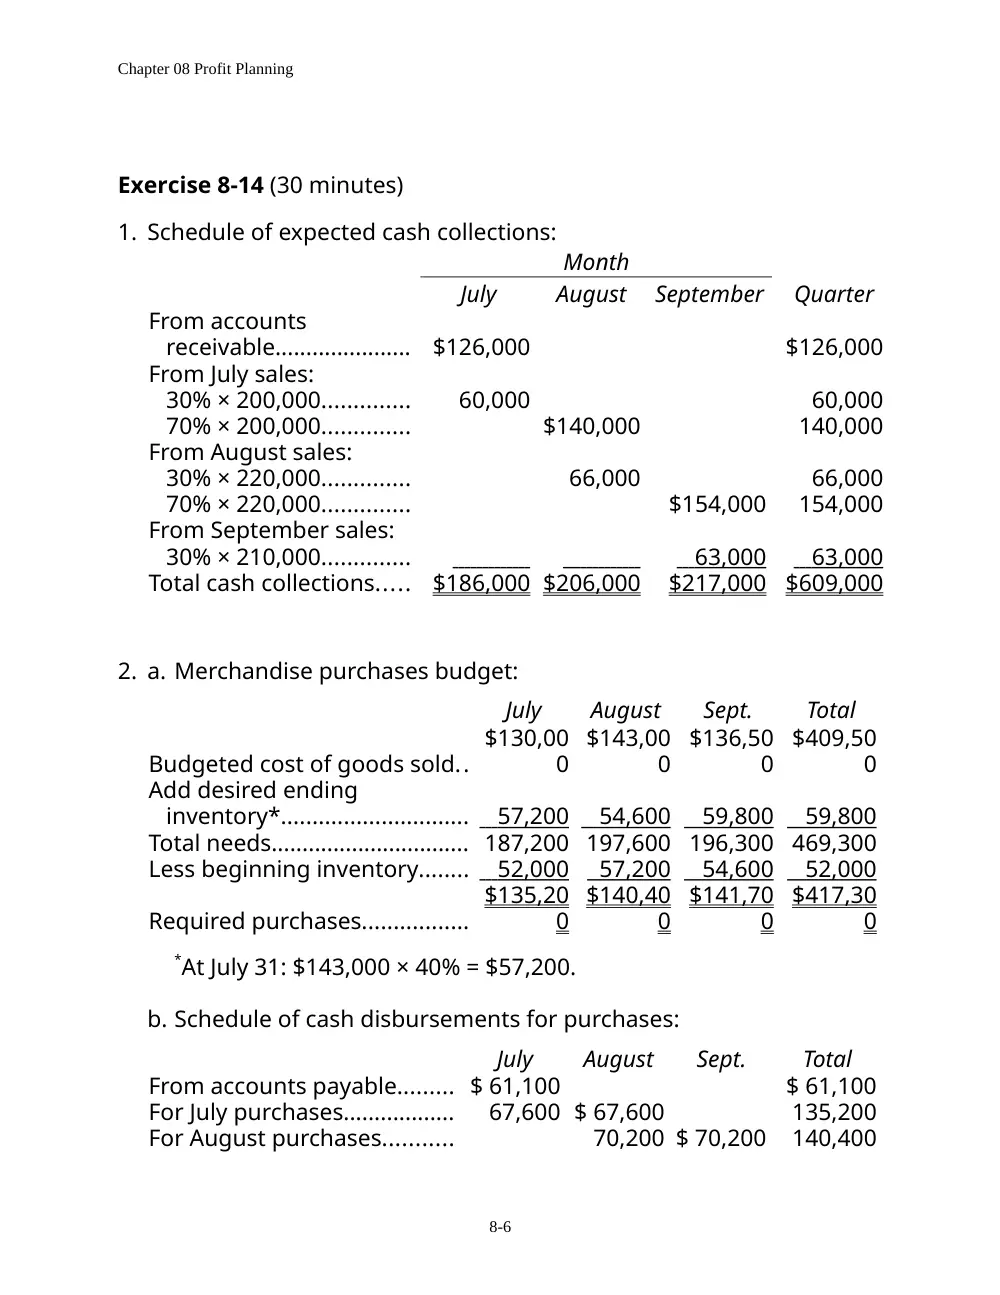
Exercise 8-14 (30 minutes)
1. Schedule of expected cash collections:
Month
July
August
September
Quarter
From accounts
receivable......................
$126,000
$126,000
From July sales:
30% × 200,000..............
60,000
60,000
70% × 200,000..............
$140,000
140,000
From August sales:
30% × 220,000..............
66,000
66,000
70% × 220,000..............
$154,000
154,000
From September sales:
30% × 210,000..............
63,000
63,000
Total cash collections.....
$186,000 $206,000
$217,000
$609,000
2. a. Merchandise purchases budget:
July
August
Sept.
Total
Budgeted cost of goods sold..
$130,00
0
$143,00
0
$136,50
0
$409,50
0
Add desired ending
inventory*.............................. 57,200
54,600
59,800
59,800
Total needs................................ 187,200 197,600
196,300
469,300
Less beginning inventory........ 52,000
57,200
54,600
52,000
Required purchases.................
$135,20
0
$140,40
0
$141,70
0
$417,30
0
*At July 31: $143,000 × 40% = $57,200.
b. Schedule of cash disbursements for purchases:
July
August
Sept.
Total
From accounts payable......... $ 61,100
$ 61,100
For July purchases..................
67,600 $ 67,600
135,200
For August purchases...........
70,200 $ 70,200
140,400
8-6
Chapter 08 Profit Planning
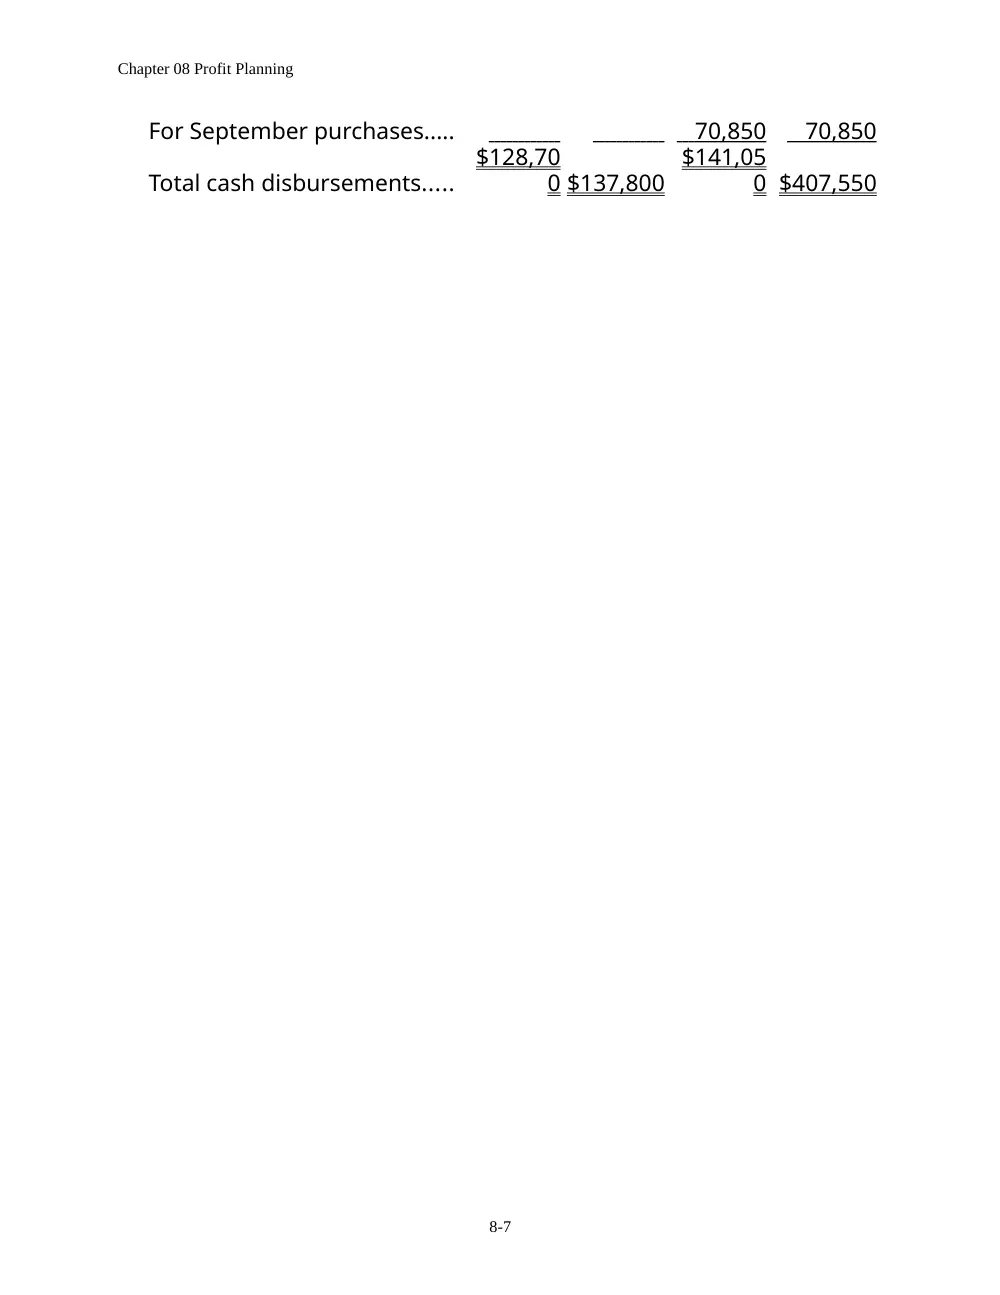
For September purchases.....
70,850
70,850
Total cash disbursements.....
$128,70
0 $137,800
$141,05
0 $407,550
8-7
Chapter 08 Profit Planning
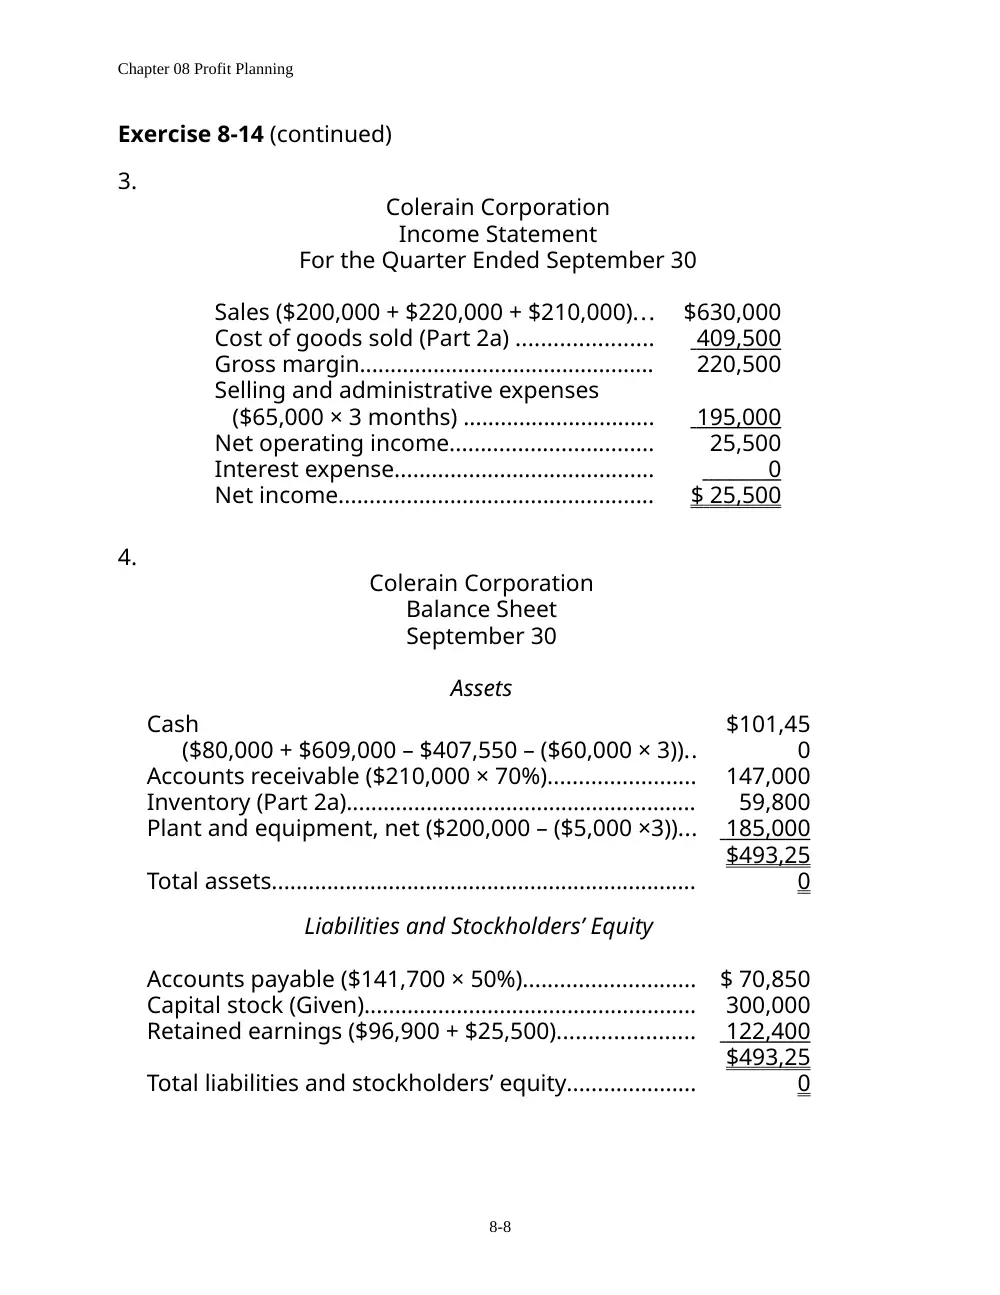
Exercise 8-14 (continued)
3.
Colerain Corporation
Income Statement
For the Quarter Ended September 30
Sales ($200,000 + $220,000 + $210,000)...
$630,000
Cost of goods sold (Part 2a) ......................
409,500
Gross margin................................................
220,500
Selling and administrative expenses
($65,000 × 3 months) ...............................
195,000
Net operating income.................................
25,500
Interest expense..........................................
0
Net income...................................................
$ 25,500
4.
Colerain Corporation
Balance Sheet
September 30
Assets
Cash
($80,000 + $609,000 – $407,550 – ($60,000 × 3))..
$101,45
0
Accounts receivable ($210,000 × 70%)........................
147,000
Inventory (Part 2a).........................................................
59,800
Plant and equipment, net ($200,000 – ($5,000 ×3))...
185,000
Total assets.....................................................................
$493,25
0
Liabilities and Stockholders’ Equity
Accounts payable ($141,700 × 50%)............................
$ 70,850
Capital stock (Given)......................................................
300,000
Retained earnings ($96,900 + $25,500)......................
122,400
Total liabilities and stockholders’ equity.....................
$493,25
0
8-8
Chapter 08 Profit Planning
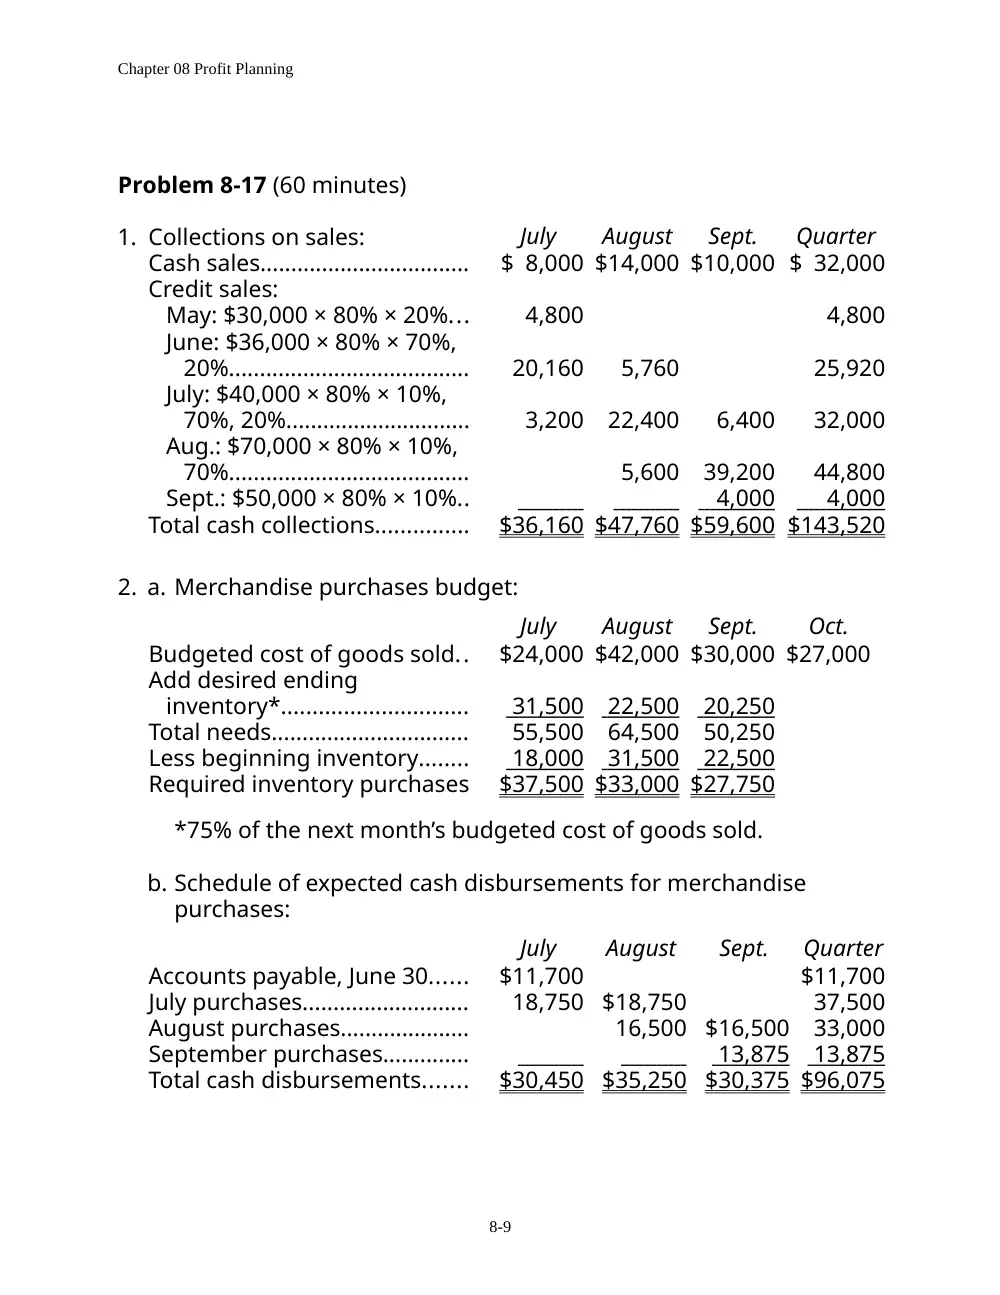
Problem 8-17 (60 minutes)
1. Collections on sales:
July
August
Sept.
Quarter
Cash sales..................................
$ 8,000 $14,000 $10,000 $ 32,000
Credit sales:
May: $30,000 × 80% × 20%...
4,800
4,800
June: $36,000 × 80% × 70%,
20%.......................................
20,160
5,760
25,920
July: $40,000 × 80% × 10%,
70%, 20%..............................
3,200
22,400
6,400
32,000
Aug.: $70,000 × 80% × 10%,
70%.......................................
5,600
39,200
44,800
Sept.: $50,000 × 80% × 10%..
4,000
4,000
Total cash collections...............
$36,160 $47,760 $59,600 $143,520
2. a. Merchandise purchases budget:
July
August
Sept.
Oct.
Budgeted cost of goods sold..
$24,000 $42,000 $30,000 $27,000
Add desired ending
inventory*..............................
31,500
22,500
20,250
Total needs................................
55,500
64,500
50,250
Less beginning inventory........
18,000
31,500
22,500
Required inventory purchases
$37,500 $33,000 $27,750
*75% of the next month’s budgeted cost of goods sold.
b. Schedule of expected cash disbursements for merchandise
purchases:
July
August
Sept.
Quarter
Accounts payable, June 30......
$11,700
$11,700
July purchases...........................
18,750
$18,750
37,500
August purchases.....................
16,500
$16,500
33,000
September purchases..............
13,875
13,875
Total cash disbursements.......
$30,450
$35,250
$30,375 $96,075
8-9
Chapter 08 Profit Planning
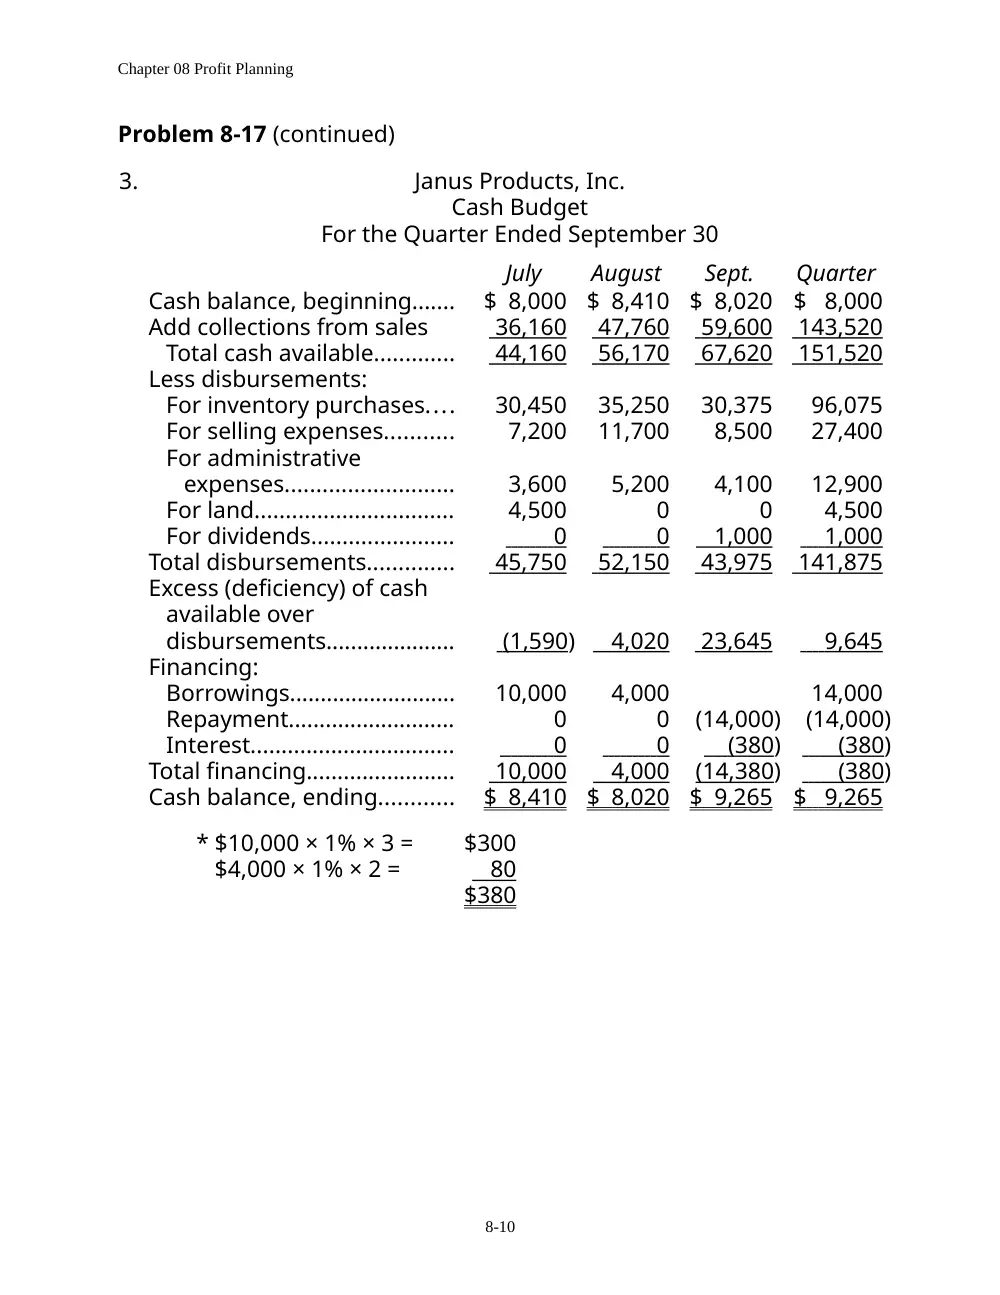
Problem 8-17 (continued)
3.
Janus Products, Inc.
Cash Budget
For the Quarter Ended September 30
July
August
Sept.
Quarter
Cash balance, beginning.......
$ 8,000
$ 8,410
$ 8,020
$ 8,000
Add collections from sales
36,160
47,760
59,600
143,520
Total cash available.............
44,160
56,170
67,620
151,520
Less disbursements:
For inventory purchases....
30,450
35,250
30,375
96,075
For selling expenses...........
7,200
11,700
8,500
27,400
For administrative
expenses...........................
3,600
5,200
4,100
12,900
For land................................
4,500
0
0
4,500
For dividends.......................
0
0
1,000
1,000
Total disbursements..............
45,750
52,150
43,975
141,875
Excess (deficiency) of cash
available over
disbursements.....................
(1,590
) 4,020
23,645
9,645
Financing:
Borrowings...........................
10,000
4,000
14,000
Repayment...........................
0
0
(14,000)
(14,000)
Interest.................................
0
0
(380
)
(380
)
Total financing........................
10,000
4,000
(14,380)
(380
)
Cash balance, ending............
$ 8,410
$ 8,020
$ 9,265
$ 9,265
* $10,000 × 1% × 3 =
$300
$4,000 × 1% × 2 =
80
$380
8-10
Chapter 08 Profit Planning
Problem 8-19 (60 minutes)
1. The sales budget for the third quarter:
July
Aug.
Sept.
Quarter
Budgeted sales (pairs)....
6,000
7,000
5,000
18,000
Selling price per pair.......
× $ 50
× $ 50
× $ 50
× $ 50
Total budgeted sales...... $300,000 $350,000 $250,000 $900,000
The schedule of expected cash collections from sales:
July
Aug.
Sept.
Quarter
Accounts receivable,
beginning balance....... $130,000
$130,000
July sales:
$300,000 × 40%, 50%...
120,000 $150,000
270,000
August sales:
$350,000 × 40%, 50%...
140,000 $175,000
315,000
September sales:
$250,000 × 40%............
100,000
100,000
Total cash collections...... $250,000 $290,000 $275,000 $815,000
2. The production budget for July through October:
July
Aug.
Sept.
Oct.
Budgeted sales (pairs).......................
6,000
7,000
5,000
4,000
Add desired ending inventory..........
700
500
400
300
Total needs..........................................
6,700
7,500
5,400
4,300
Less beginning inventory..................
600
700
500
400
Required production (pairs)..............
6,100
6,800
4,900
3,900
8-11
Chapter 08 Profit Planning
Problem 8-19 (continued)
3. The direct materials budget for the third quarter:
July
Aug.
Sept.
Quarter
Required production—
pairs (above)......................
6,100
6,800
4,900
17,800
Raw materials needs per
pair (lbs.)............................
× 2
× 2
× 2
× 2
Production needs (lbs.).......
12,200
13,600
9,800
35,600
Add desired ending
inventory............................
2,720
1,960
1,560
*
1,560
Total needs...........................
14,920
15,560
11,360
37,160
Less beginning inventory
2,440
2,720
1,960
2,440
Raw materials to be
purchased..........................
12,480
12,840
9,400
34,720
Cost of raw materials to
be purchased at $2.50
per lb.................................. $31,200
$32,100
$23,500
$86,800
*3,900 pairs (October) × 2 lbs. per pair= 7,800 lbs.;
7,800 lbs. × 20% = 1,560 lbs.
The schedule of expected cash disbursements:
July
Aug.
Sept.
Quarter
Accounts payable, beginning
balance....................................
$11,400
$11,400
July purchases:
$31,200 × 60%, 40%...............
18,720 $12,480
31,200
August purchases:
$32,100 × 60%, 40%...............
19,260 $12,840
32,100
September purchases:
$23,500 × 60%........................
14,100
14,100
Total cash disbursements........
$30,120 $31,740 $26,940 $88,800
8-12
Chapter 08 Profit Planning
Problem 8-26 (120 minutes)
1. Schedule of expected cash collections:
January
February
March
Quarter
Cash sales.............................
$28,000
$32,000
$34,000 $ 94,000
Credit sales*.........................
36,000
42,000
48,000
126,000
Total collections...................
$64,000
$74,000
$82,000 $220,000
*60% of the preceding month’s sales.
2. Merchandise purchases budget:
January February
March
Quarter
Budgeted cost of goods
sold (70% of sales)............
$49,000
$56,000
$59,500
$164,500
Add desired ending
inventory*..........................
11,200
11,900
7,700
7,700
Total needs...........................
60,200
67,900
67,200
172,200
Less beginning inventory...
9,800
11,200
11,900
9,800
Required purchases............
$50,400
$56,700
$55,300
$162,400
*At March 30: April sales $55,000 × 70% × 20% = $7,700.
Schedule of expected cash disbursements—merchandise purchases
January
February
March
Quarter
December purchases..........
$32,550
$ 32,550
January purchases...............
12,600
$37,800
50,400
February purchases............
14,175
$42,525
56,700
March purchases.................
13,825
13,825
Total disbursements............
$45,150
$51,975
$56,350 $153,475
8-13
Chapter 08 Profit Planning
Problem 8-26 (continued)
3. Schedule of expected cash disbursements—selling and
administrative expenses
January
February
March
Quarter
Commissions........................
$12,000
$12,000 $12,000
$36,000
Rent.......................................
1,800
1,800
1,800
5,400
Other expenses....................
5,600
6,400
6,800
18,800
Total disbursements............
$19,400
$20,200 $20,600
$60,200
4. Cash budget:
January
February
March
Quarter
Cash balance, beginning..
$ 6,000
$ 5,450
$ 5,275
$ 6,000
Add cash collections.........
64,000
74,000
82,000
220,000
Total cash available........
70,000
79,450
87,275
226,000
Less cash disbursements:
For inventory..................
45,150
51,975
56,350
153,475
For operating expenses.
19,400
20,200
20,600
60,200
For equipment................
3,000
8,000
0
11,000
Total disbursements.........
67,550
80,175
76,950
224,675
Excess (deficiency) of cash
2,450
(725
)
10,325
1,325
Financing:
Borrowings......................
3,000
6,000
0
9,000
Repayments....................
0
0
(5,000)
(5,000)
Interest*..........................
0
0
(210
)
(210
)
Total financing...................
3,000
6,000
(5,210
) 3,790
Cash balance, ending.......
$ 5,450
$ 5,275
$ 5,115
$ 5,115
* $3,000 × 1% × 3 =
$ 90
$6,000 × 1% × 2 =
120
Total interest
$210
8-14
Chapter 08 Profit Planning
Problem 8-26 (continued)
5.
Picanuy Corporation
Income Statement
For the Quarter Ended March 31
Sales ($70,000 + $80,000 + $85,000)..........
$235,000
Cost of goods sold:
Beginning inventory (Given)....................
$ 9,800
Purchases (Part 2).....................................
162,400
Goods available for sale...........................
172,200
Ending inventory (Part 2).........................
7,700
164,500
*
Gross margin................................................
70,500
Selling and administrative expenses:
Commissions (Part 3)................................
36,000
Rent (Part 3)...............................................
5,400
Depreciation (Given).................................
2,400
Other expenses (Part 3)...........................
18,800
62,600
Net operating income.................................
7,900
Interest expense..........................................
210
Net income...................................................
$ 7,690
* A simpler computation would be: $235,000 × 70% = $164,500.
8-15
Chapter 08 Profit Planning
Problem 8-26 (continued)
6.
Picanuy Corporation
Balance Sheet
March 31
Assets
Current assets:
Cash (Part 4)....................................................................
$ 5,115
Accounts receivable ($85,000 × 60%)...........................
51,000
Inventory (Part 2)............................................................
7,700
Total current assets...........................................................
63,815
Fixed assets—net
($110,885 + $3,000 + $8,000 – $2,400).........................
119,485
Total assets.........................................................................
$183,300
Liabilities and Stockholders’ Equity
Accounts payable (Part 2: $55,300 × 75%).....
$ 41,475
Bank loan payable............................................
4,000
Stockholders’ equity:
Capital stock (Given)......................................
$100,000
Retained earnings*.......................................
37,825
137,825
Total liabilities and equity................................
$183,300
* Retained earnings, beginning.....................
$30,135
Add net income.............................................
7,690
Retained earnings, ending..........................
$37,825
8-16