
ACCT 215 Problems Solutions, Fall 2011
American University of Beirut · Management Accounting · 18 pages · with solution


Showing the first 10 of 18 pages. Download the PDF to see all of it.
More ACCT 215 files
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
Show the text of this problems
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Chapter 06
Variable Costing and Segment Reporting:
Tools for Management
Exercise 6-1 (15 minutes)
1. Under absorption costing, all manufacturing costs (variable and
fixed) are included in product costs. (All currency values are in
thousands of rupees, denoted by R.)
Direct materials........................................................................
R120
Direct labor................................................................................
140
Variable manufacturing overhead.........................................
50
Fixed manufacturing overhead (R600,000 ÷ 10,000
units).......................................................................................
60
Absorption costing unit product cost....................................
R370
2. Under variable costing, only the variable manufacturing costs are
included in product costs. (All currency values are in thousands of
rupees, denoted by R.)
Direct materials.....................................
R120
Direct labor............................................
140
Variable manufacturing overhead......
50
Variable costing unit product cost......
R310
Note that selling and administrative expenses are not treated as
product costs under either absorption or variable costing. These
expenses are always treated as period costs and are charged
against the current period’s revenue.
6-1
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Exercise 6-2 (20 minutes)
1. 2,000 units in ending inventory × R60 fixed manufacturing overhead
per unit = R120,000.
2. The variable costing income statement appears below:
Sales.......................................................
R4,000,000
Variable expenses:
Variable cost of goods sold
(8,000 units × R310 per unit).........
R2,480,000
Variable selling and administrative
(8,000 units × R20 per unit)...........
160,000
2,640,000
Contribution margin............................
1,360,000
Fixed expenses:
Fixed manufacturing overhead........
600,000
Fixed selling and administrative......
400,000
1,000,000
Net operating income..........................
R 360,000
The difference in net operating income between variable and
absorption costing can be explained by the deferral of fixed
manufacturing overhead cost in inventory that has taken place
under the absorption costing approach. Note from part (1) that
R120,000 of fixed manufacturing overhead cost has been deferred
in inventory to the next period. Thus, net operating income under
the absorption costing approach is R120,000 higher than it is under
variable costing
6-2
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
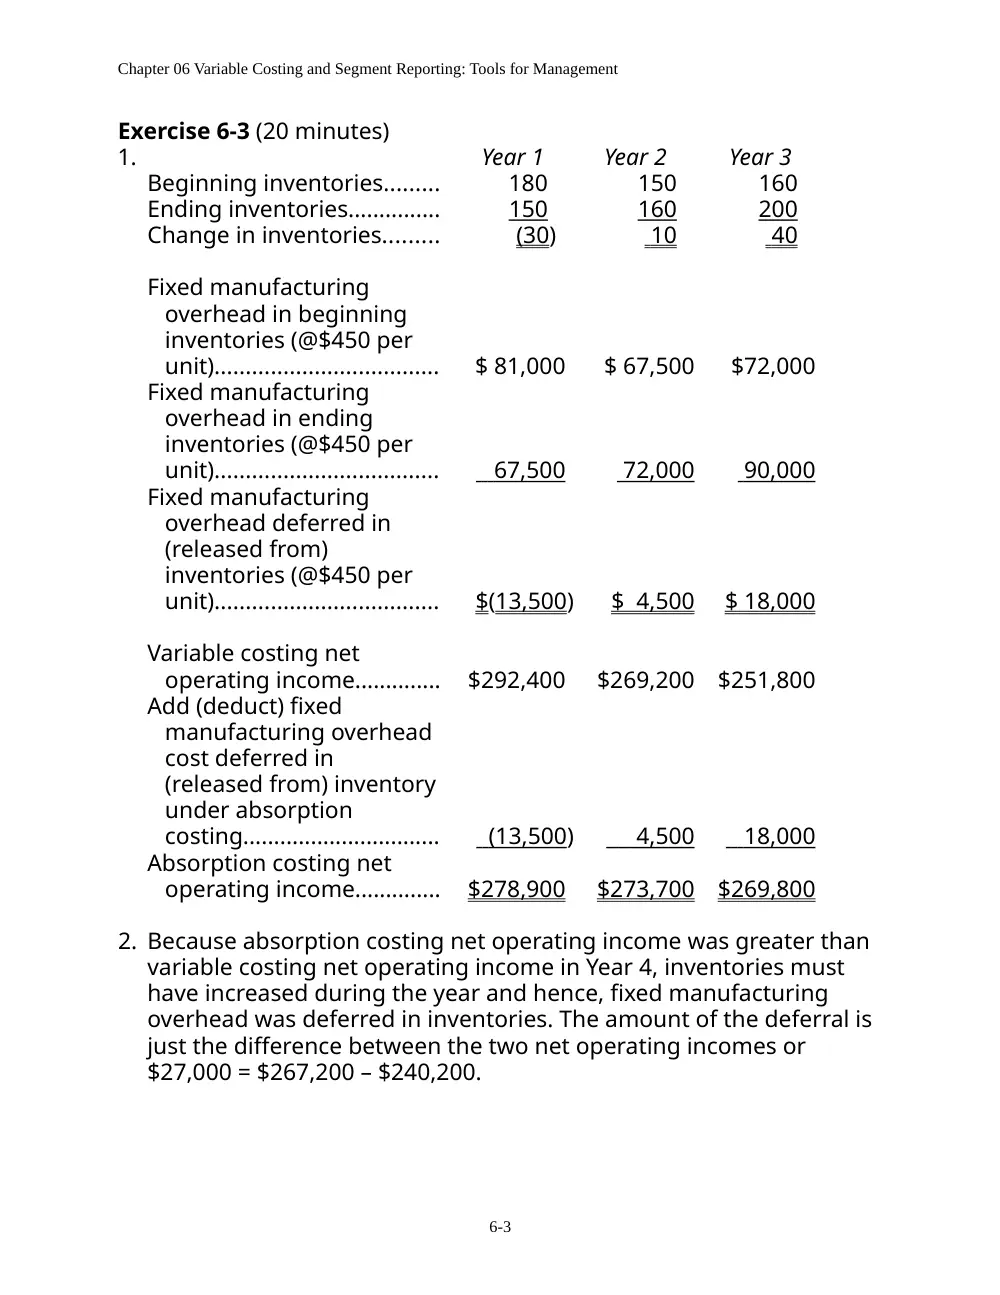
Exercise 6-3 (20 minutes)
1.
Year 1
Year 2
Year 3
Beginning inventories.........
180
150
160
Ending inventories...............
150
160
200
Change in inventories.........
(30)
10
40
Fixed manufacturing
overhead in beginning
inventories (@$450 per
unit)....................................
$ 81,000
$ 67,500
$72,000
Fixed manufacturing
overhead in ending
inventories (@$450 per
unit)....................................
67,500
72,000
90,000
Fixed manufacturing
overhead deferred in
(released from)
inventories (@$450 per
unit)....................................
$(13,500)
$ 4,500
$ 18,000
Variable costing net
operating income..............
$292,400
$269,200
$251,800
Add (deduct) fixed
manufacturing overhead
cost deferred in
(released from) inventory
under absorption
costing................................
(13,500
)
4,500
18,000
Absorption costing net
operating income..............
$278,900
$273,700
$269,800
2. Because absorption costing net operating income was greater than
variable costing net operating income in Year 4, inventories must
have increased during the year and hence, fixed manufacturing
overhead was deferred in inventories. The amount of the deferral is
just the difference between the two net operating incomes or
$27,000 = $267,200 – $240,200.
6-3
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
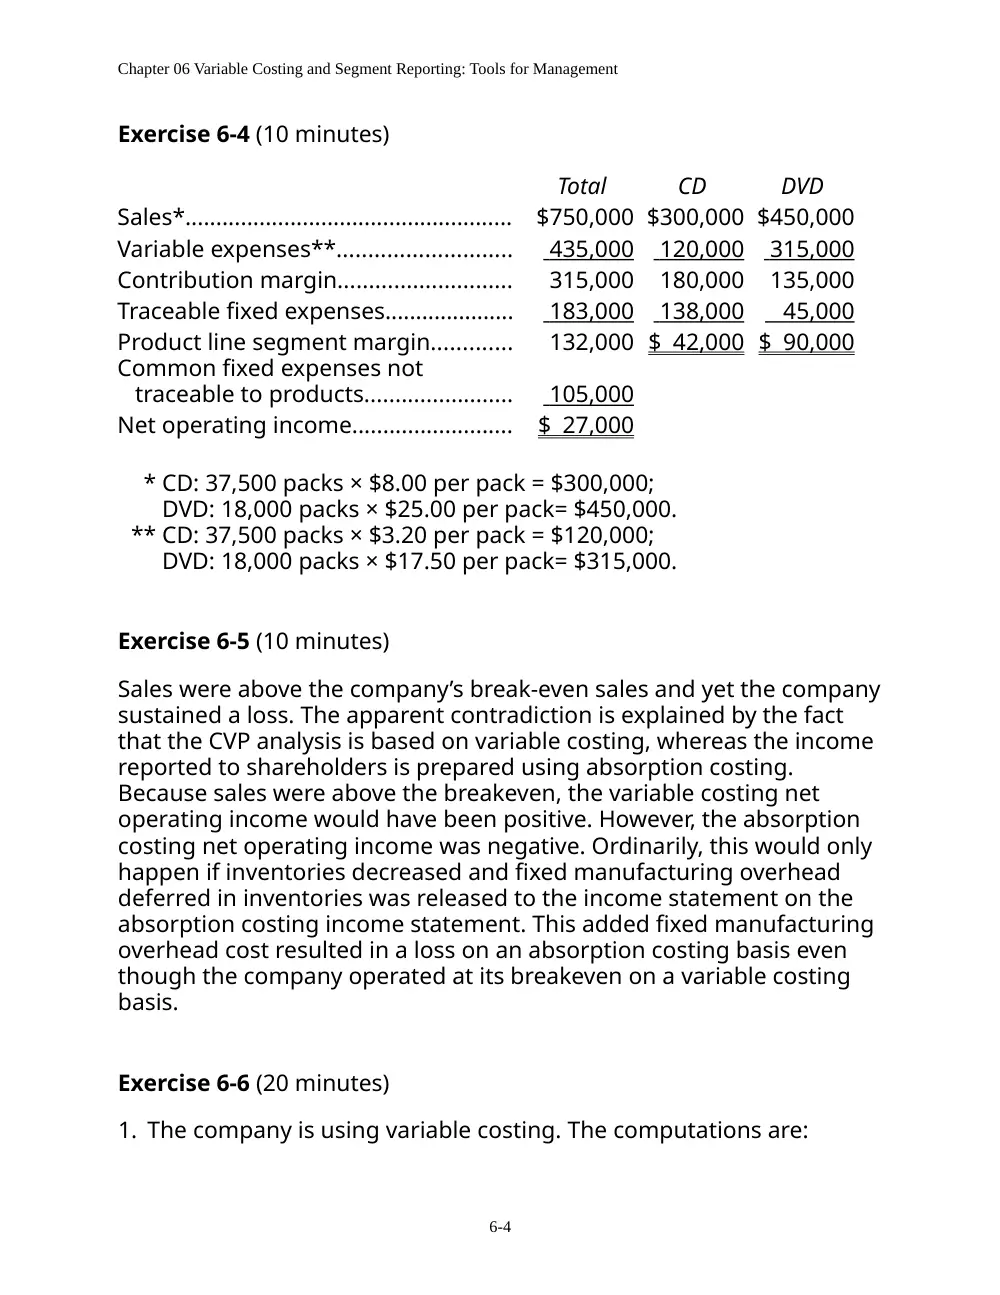
Exercise 6-4 (10 minutes)
Total
CD
DVD
Sales*.....................................................
$750,000 $300,000 $450,000
Variable expenses**............................
435,000
120,000
315,000
Contribution margin............................
315,000
180,000
135,000
Traceable fixed expenses.....................
183,000
138,000
45,000
Product line segment margin.............
132,000 $ 42,000 $ 90,000
Common fixed expenses not
traceable to products........................
105,000
Net operating income..........................
$ 27,000
*
**
CD: 37,500 packs × $8.00 per pack = $300,000;
DVD: 18,000 packs × $25.00 per pack= $450,000.
CD: 37,500 packs × $3.20 per pack = $120,000;
DVD: 18,000 packs × $17.50 per pack= $315,000.
Exercise 6-5 (10 minutes)
Sales were above the company’s break-even sales and yet the company
sustained a loss. The apparent contradiction is explained by the fact
that the CVP analysis is based on variable costing, whereas the income
reported to shareholders is prepared using absorption costing.
Because sales were above the breakeven, the variable costing net
operating income would have been positive. However, the absorption
costing net operating income was negative. Ordinarily, this would only
happen if inventories decreased and fixed manufacturing overhead
deferred in inventories was released to the income statement on the
absorption costing income statement. This added fixed manufacturing
overhead cost resulted in a loss on an absorption costing basis even
though the company operated at its breakeven on a variable costing
basis.
Exercise 6-6 (20 minutes)
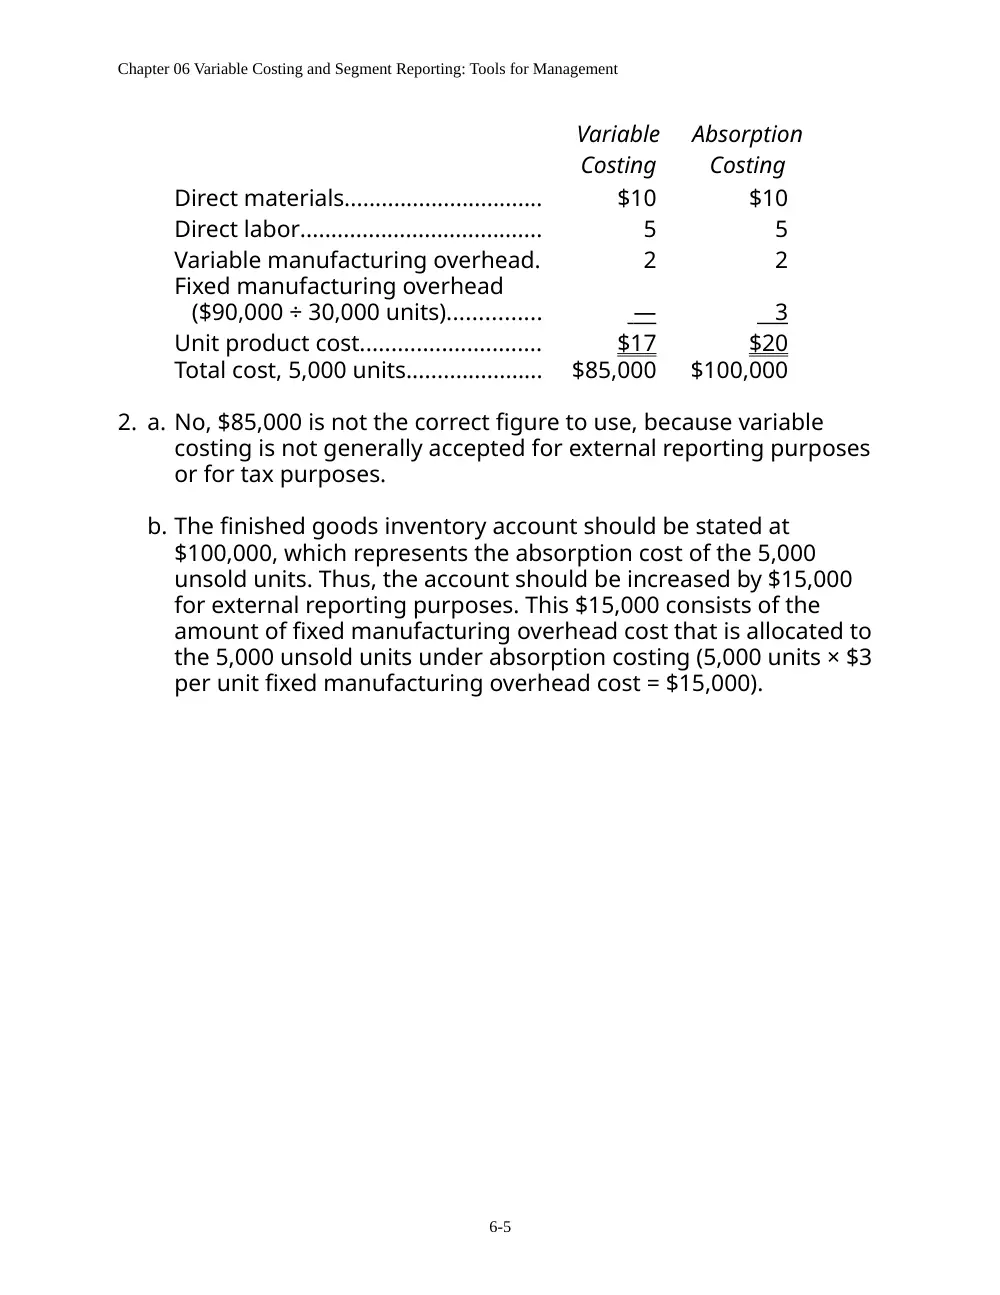
1. The company is using variable costing. The computations are:
6-4
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Variable
Costing
Absorption
Costing
Direct materials................................
$10
$10
Direct labor.......................................
5
5
Variable manufacturing overhead.
2
2
Fixed manufacturing overhead
($90,000 ÷ 30,000 units)...............
—
3
Unit product cost.............................
$17
$20
Total cost, 5,000 units......................
$85,000
$100,000
2. a. No, $85,000 is not the correct figure to use, because variable
costing is not generally accepted for external reporting purposes
or for tax purposes.
b. The finished goods inventory account should be stated at
$100,000, which represents the absorption cost of the 5,000
unsold units. Thus, the account should be increased by $15,000
for external reporting purposes. This $15,000 consists of the
amount of fixed manufacturing overhead cost that is allocated to
the 5,000 unsold units under absorption costing (5,000 units × $3
per unit fixed manufacturing overhead cost = $15,000).
6-5
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
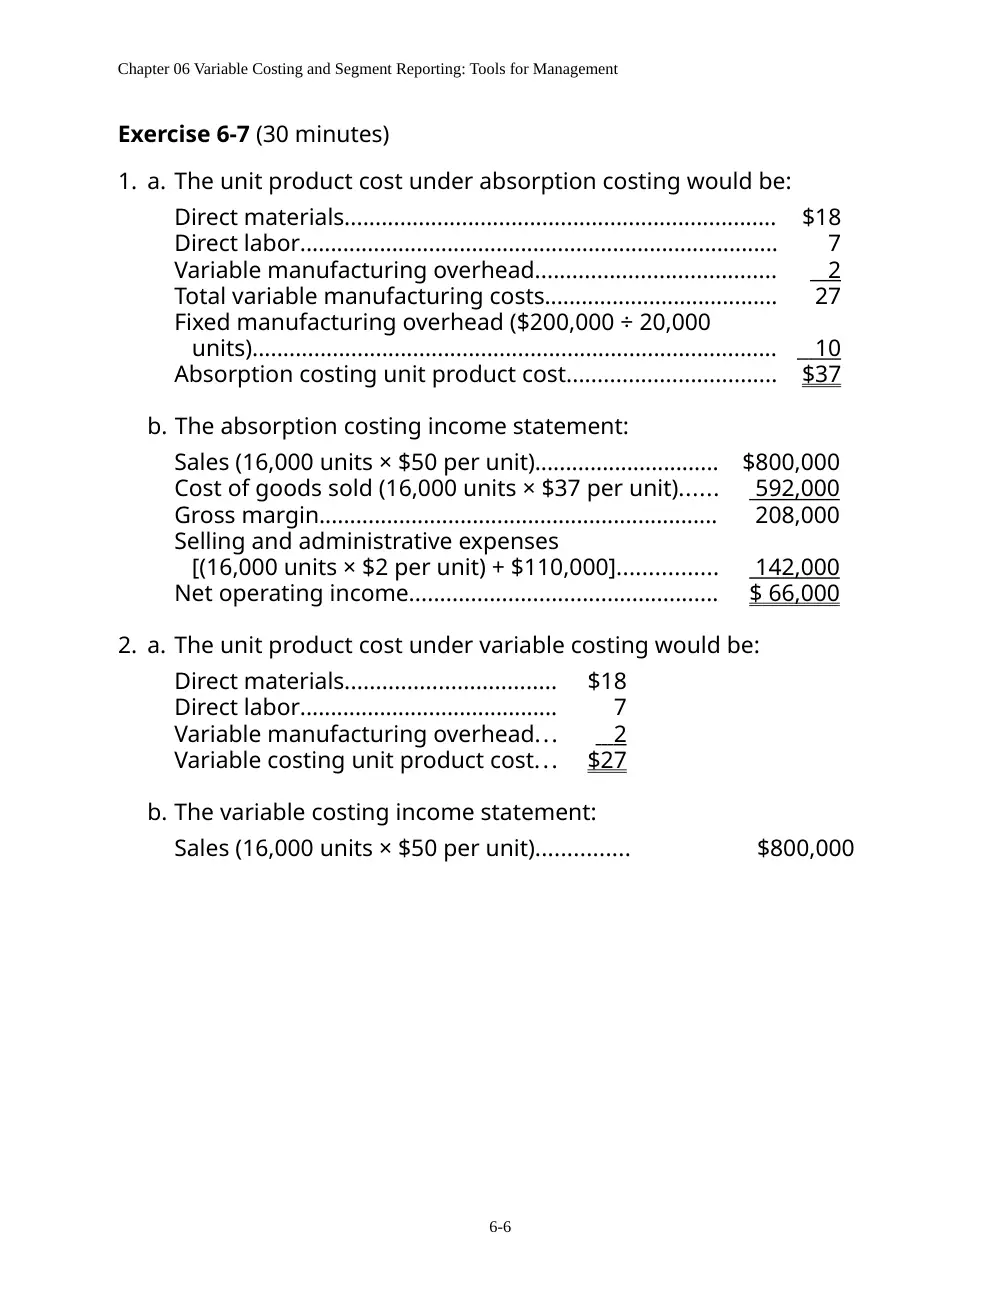
Exercise 6-7 (30 minutes)
1. a. The unit product cost under absorption costing would be:
Direct materials......................................................................
$18
Direct labor..............................................................................
7
Variable manufacturing overhead.......................................
2
Total variable manufacturing costs......................................
27
Fixed manufacturing overhead ($200,000 ÷ 20,000
units).....................................................................................
10
Absorption costing unit product cost..................................
$37
b. The absorption costing income statement:
Sales (16,000 units × $50 per unit)..............................
$800,000
Cost of goods sold (16,000 units × $37 per unit)......
592,000
Gross margin.................................................................
208,000
Selling and administrative expenses
[(16,000 units × $2 per unit) + $110,000]................
142,000
Net operating income..................................................
$ 66,000
2. a. The unit product cost under variable costing would be:
Direct materials..................................
$18
Direct labor..........................................
7
Variable manufacturing overhead...
2
Variable costing unit product cost...
$27
b. The variable costing income statement:
Sales (16,000 units × $50 per unit)...............
$800,000
6-6
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
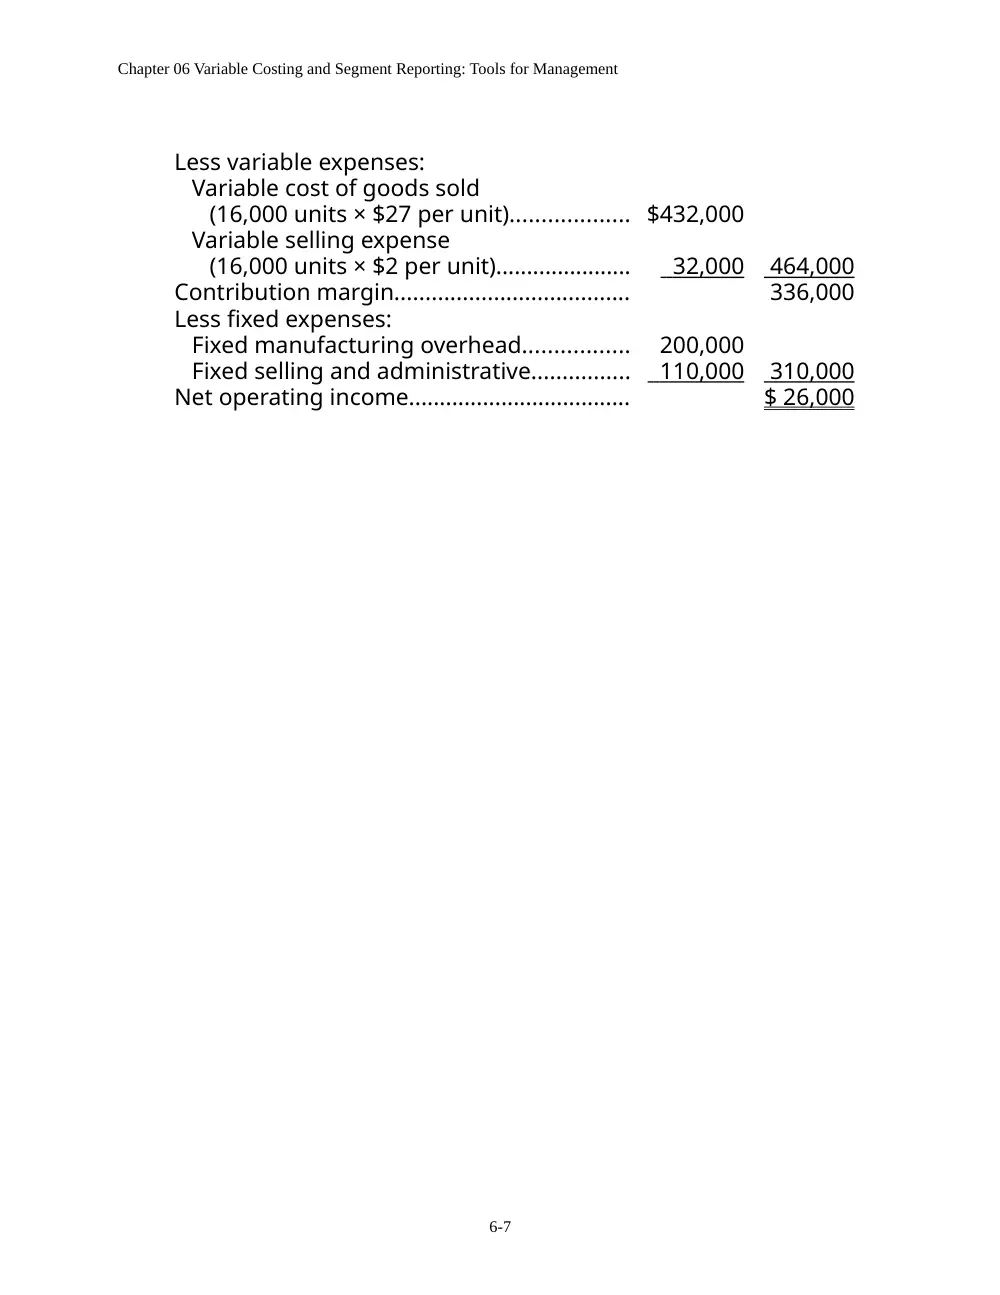
Less variable expenses:
Variable cost of goods sold
(16,000 units × $27 per unit)................... $432,000
Variable selling expense
(16,000 units × $2 per unit)......................
32,000
464,000
Contribution margin......................................
336,000
Less fixed expenses:
Fixed manufacturing overhead.................
200,000
Fixed selling and administrative................ 110,000
310,000
Net operating income....................................
$ 26,000
6-7
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Exercise 6-7 (continued)
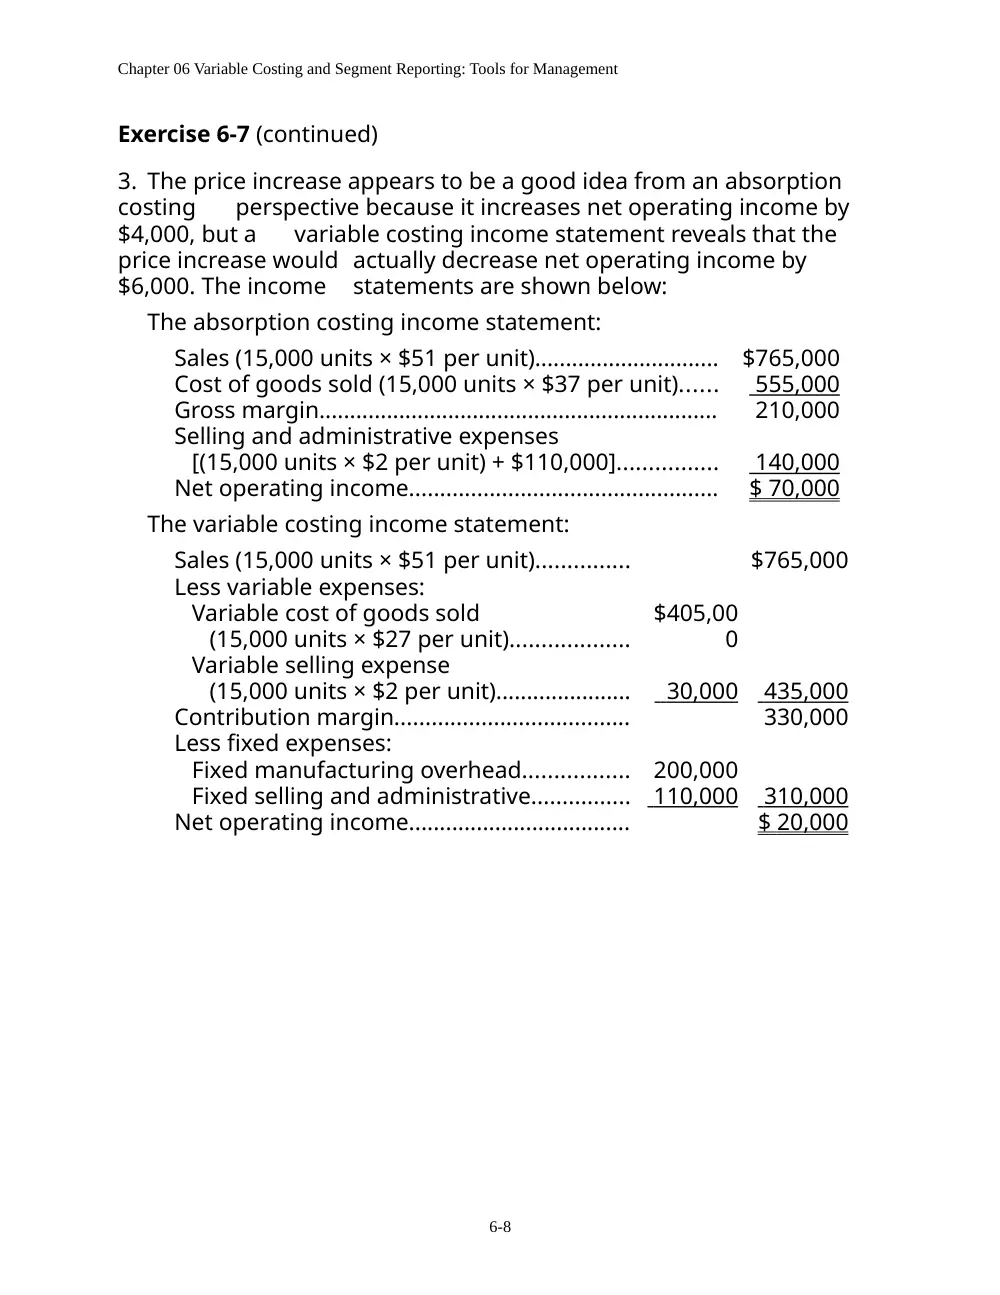
3. The price increase appears to be a good idea from an absorption
costing
perspective because it increases net operating income by
$4,000, but a
variable costing income statement reveals that the
price increase would actually decrease net operating income by
$6,000. The income
statements are shown below:
The absorption costing income statement:
Sales (15,000 units × $51 per unit)..............................
$765,000
Cost of goods sold (15,000 units × $37 per unit)......
555,000
Gross margin.................................................................
210,000
Selling and administrative expenses
[(15,000 units × $2 per unit) + $110,000]................
140,000
Net operating income..................................................
$ 70,000
The variable costing income statement:
Sales (15,000 units × $51 per unit)...............
$765,000
Less variable expenses:
Variable cost of goods sold
(15,000 units × $27 per unit)...................
$405,00
0
Variable selling expense
(15,000 units × $2 per unit)......................
30,000
435,000
Contribution margin......................................
330,000
Less fixed expenses:
Fixed manufacturing overhead.................
200,000
Fixed selling and administrative................ 110,000
310,000
Net operating income....................................
$ 20,000
6-8
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Exercise 6-8 (10 minutes)
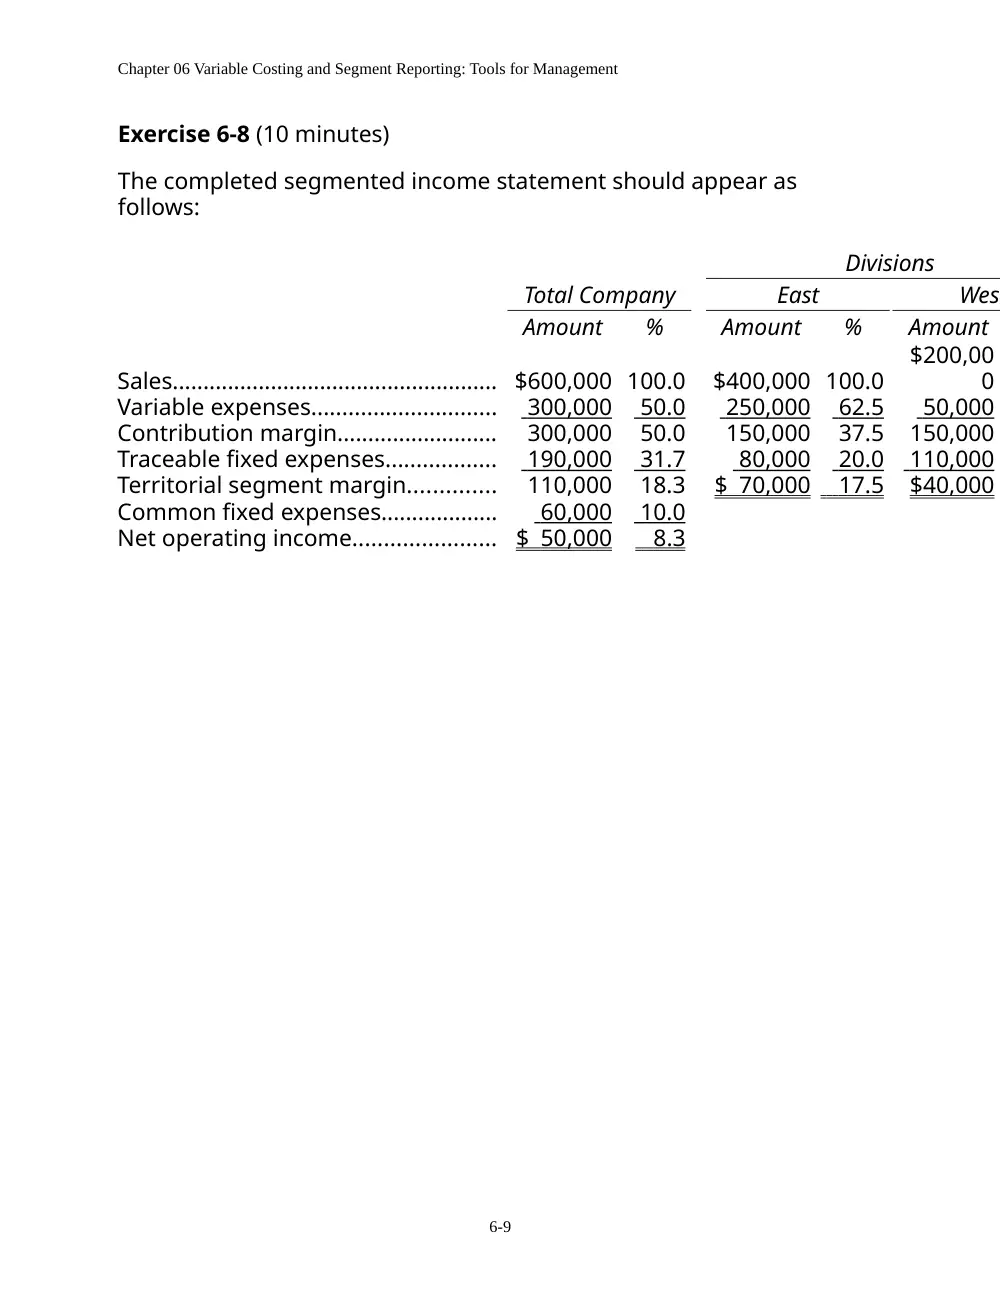
The completed segmented income statement should appear as
follows:
Divisions
Total Company
East
Wes
Amount
%
Amount
%
Amount
Sales..................................................... $600,000 100.0
$400,000 100.0
$200,00
0
Variable expenses..............................
300,000
50.0
250,000
62.5
50,000
Contribution margin..........................
300,000
50.0
150,000
37.5
150,000
Traceable fixed expenses..................
190,000
31.7
80,000
20.0
110,000
Territorial segment margin..............
110,000
18.3
$ 70,000 17.5
$40,000
Common fixed expenses...................
60,000
10.0
Net operating income.......................
$ 50,000
8.3
6-9
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Exercise 6-9 (30 minutes)
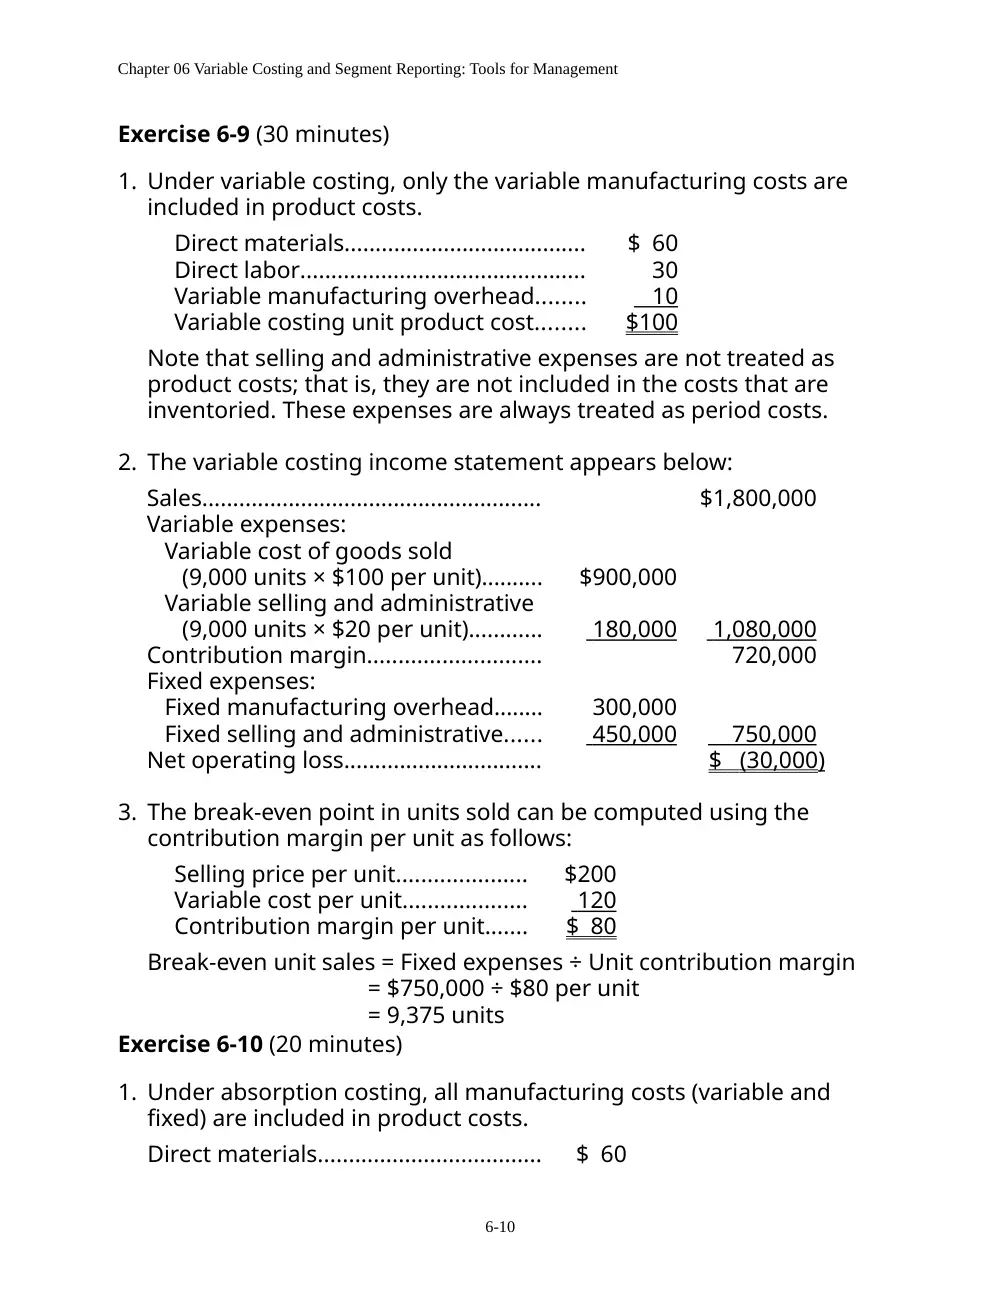
1. Under variable costing, only the variable manufacturing costs are
included in product costs.
Direct materials.......................................
$ 60
Direct labor..............................................
30
Variable manufacturing overhead........
10
Variable costing unit product cost........
$100
Note that selling and administrative expenses are not treated as
product costs; that is, they are not included in the costs that are
inventoried. These expenses are always treated as period costs.
2. The variable costing income statement appears below:
Sales.......................................................
$1,800,000
Variable expenses:
Variable cost of goods sold
(9,000 units × $100 per unit)..........
$900,000
Variable selling and administrative
(9,000 units × $20 per unit)............
180,000
1,080,000
Contribution margin............................
720,000
Fixed expenses:
Fixed manufacturing overhead........
300,000
Fixed selling and administrative......
450,000
750,000
Net operating loss................................
$ (30,000
)
3. The break-even point in units sold can be computed using the
contribution margin per unit as follows:
Selling price per unit.....................
$200
Variable cost per unit....................
120
Contribution margin per unit.......
$ 80
Break-even unit sales = Fixed expenses ÷ Unit contribution margin
= $750,000 ÷ $80 per unit
= 9,375 units
Exercise 6-10 (20 minutes)
1. Under absorption costing, all manufacturing costs (variable and
fixed) are included in product costs.
Direct materials....................................
$ 60
6-10
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Direct labor............................................
30
Variable manufacturing overhead.....
10
Fixed manufacturing overhead
($300,000 ÷ 10,000 units)..................
30
Unit product cost..................................
$130
2. The absorption costing income statement appears below:
Sales (9,000 units × $200 per unit).................................. $1,800,000
Cost of goods sold (9,000 units × $130 per unit)........... 1,170,000
Gross margin.....................................................................
630,000
Selling and administrative expenses
(9,000 units × $20 per unit) + $450,000.......................
630,000
Net operating income.......................................................
$ 0
Note: The company apparently has exactly zero net operating
income even though its sales are below the break-even point
computed in Exercise 6-9. This occurs because $30,000 of fixed
manufacturing overhead has been deferred in inventory and does
not appear on the income statement prepared using absorption
costing.
6-11
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Exercise 6-11 (20 minutes)
1.
Total
Geographic Market
Company
South
Central
North
Sales....................................
$1,500,000
$400,000 $600,000 $500,000
Variable expenses.............
588,000
208,000
180,000
200,000
Contribution margin.........
912,000
192,000
420,000
300,000
Traceable fixed expenses.
770,000
240,000
330,000
200,000
Geographic market
segment margin.............
142,000
$(48,000) $ 90,000 $100,000
Common fixed expenses
not traceable to
geographic markets*.....
175,000
Net operating income
(loss).................................
$ (33,000
)
*$945,000 – $770,000 = $175,000.
2. Incremental sales ($600,000 × 15%)......................
$90,000
Contribution margin ratio ($420,000 ÷
$600,000)...............................................................
× 70%
Incremental contribution margin..........................
63,000
Less incremental advertising expense..................
25,000
Incremental net operating income.......................
$38,000
Yes, the advertising program should be initiated.
Exercise 6-12 (30 minutes)
1 a. Under variable costing, only the variable manufacturing costs are
included in product costs.
Year 1
Year 2
Direct materials.......................................
$20
$20
Direct labor..............................................
12
12
Variable manufacturing overhead........
4
4
Variable costing unit product cost........
$36
$36
Note that selling and administrative expenses are not treated as
product costs; that is, they are not included in the costs that are
inventoried. These expenses are always treated as period costs.
1 b.
6-12
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Year 1
Year 2
Sales.................................................................
$2,000,000 $2,500,000
Variable expenses:
Variable cost of goods sold @ $36 per
unit.............................................................
1,440,000
1,800,000
Variable selling and administrative @ $3
per unit......................................................
120,000
150,000
Total variable expenses.................................
1,560,000
1,950,000
Contribution margin......................................
440,000
550,000
Fixed expenses:
Fixed manufacturing overhead.................
200,000
200,000
Fixed selling and administrative................
80,000
80,000
Total fixed expenses......................................
280,000
280,000
Net operating income (loss)..........................
$ 160,000
$ 270,000
2 a. The unit product costs under absorption costing:
6-13
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Year 1 Year 2
Direct materials.......................................
$20
$20
Direct labor..............................................
12
12
Variable manufacturing overhead........
4
4
Fixed manufacturing overhead.............
*4
**5
Absorption costing unit product cost...
$40
$41
* $200,000 ÷ 50,000 units = $4 per unit.
** $200,000 ÷ 40,000 units = $5 per unit.
Exercise 6-12 (continued)
2 b. The absorption costing income statements appears below:
Year 1
Year 2
Sales............................................................ $2,000,000
$2,500,000
Cost of goods sold..................................... *1,600,000 **2
,040,000
Gross margin.............................................
400,000
460,000
Selling and administrative
expenses..................................................
200,000
2 30,000
Net operating income...............................
$ 200,000
$ 230,000
* 40,000 units × $40 per unit = $1,600,000
** (40,000 units × $41 per unit) + (10,000 units × $40 per unit) =
$2,040,000
3. The net operating incomes are reconciled as follows:
Year 1
Year 2
Variable costing net operating income
(loss)..............................................................
$ 160,000 $ 270,000
6-14
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Add: Fixed manufacturing overhead cost
deferred in inventory under absorption
costing (10,000 units × $4 per unit)..........
40,000
Deduct: Fixed manufacturing overhead
cost released from inventory under
absorption costing (10,000 units × $4
per unit)........................................................
(40,000
)
Absorption costing net operating income..
$ 200,000
$ 230,000
Exercise 6-13 (20 minutes)
1. Sales (40,000 units × $33.75 per unit)............
$1,350,000
Variable expenses:
Variable cost of goods sold
(40,000 units × $16 per unit*)...................
$640,000
Variable selling and administrative
expenses
(40,000 units × $3 per unit).......................
120,000
760,000
Contribution margin........................................
590,000
Fixed expenses:
Fixed manufacturing overhead...................
250,000
Fixed selling and administrative expenses
300,000
550,000
Net operating income......................................
$ 40,000
* Direct materials.................................
$10
Direct labor........................................
4
Variable manufacturing overhead..
2
Total variable manufacturing cost..
$16
2. The difference in net operating income can be explained by the
$50,000 in fixed manufacturing overhead deferred in inventory
under the absorption costing method:
Variable costing net operating income..........................
$40,000
Add fixed manufacturing overhead cost deferred in
inventory under absorption costing (10,000 units ×
$5 per unit in fixed manufacturing overhead cost)...
50,000
Absorption costing net operating income.....................
$90,000
6-15
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
6-16
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Exercise 6-14 (20 minutes)
1. $75,000 × 40% CM ratio = $30,000 increased contribution margin in
Dallas. Because the fixed costs in the office and in the company as a
whole will not change, the entire $30,000 would result in increased
net operating income for the company.
It is incorrect to multiply the $75,000 increase in sales by Dallas’ 25%
segment margin ratio. This approach assumes that the segment’s
traceable fixed expenses increase in proportion to sales, but if they
did, they would not be fixed.
2. a. The segmented income statement follows:
Segments
Total Company
Houston
Dallas
Amount
%
Amount
%
Amount
%
Sales..........................
$800,000 100.0
$200,000 100
$600,000 100
Variable
expenses................ 420,000
52.5
60,000
30
360,000
60
Contribution
margin....................380,000
47.5
140,000
70
240,000
40
Traceable fixed
expenses................ 168,000
21.0
78,000
39
90,000
15
Office segment
margin....................212,000
26.5
$ 62,000
31
$150,000
25
Common fixed
expenses not
traceable to
segments............... 120,000
15.0
Net operating
income............... $ 92,000
11.5
b. The segment margin ratio rises and falls as sales rise and fall due
to the presence of fixed costs. The fixed expenses are spread over
a larger base as sales increase.
In contrast to the segment ratio, the contribution margin ratio is
stable so long as there is no change in either variable expenses or
the selling price of a unit of service.
6-17
Chapter 06 Variable Costing and Segment Reporting: Tools for Management
Exercise 6-15 (15 minutes)
1. The company should focus its campaign on Landscaping Clients.
The computations are:
Construction
Clients
Landscaping
Clients
Increased sales.....................................
$70,000
$60,000
Market CM ratio....................................
× 35%
× 50%
Incremental contribution margin.......
$24,500
$30,000
Less cost of the campaign...................
8,000
8,000
Increased segment margin and net
operating income for the company
as a whole...........................................
$16,500
$22,000
2. The $90,000 in traceable fixed expenses in the previous exercise is
now partly traceable and partly common. When we segment Dallas
by market, only $72,000 remains a traceable fixed expense. This
amount represents costs such as advertising and salaries that arise
because of the existence of the construction and landscaping
market segments. The remaining $18,000 ($90,000 – $72,000) is a
common cost when Dallas is segmented by market. This amount
would include such costs as the salary of the manager of the Dallas
office that could not be avoided by eliminating either of the two
market segments.
6-18