
ACCT 215 Problems Solutions, Fall 2011
American University of Beirut · Management Accounting · 12 pages · with solution


Showing the first 10 of 12 pages. Download the PDF to see all of it.
More ACCT 215 files
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
- Problems Solutions · Fall 2011Problems · with solutionView
Show the text of this problems
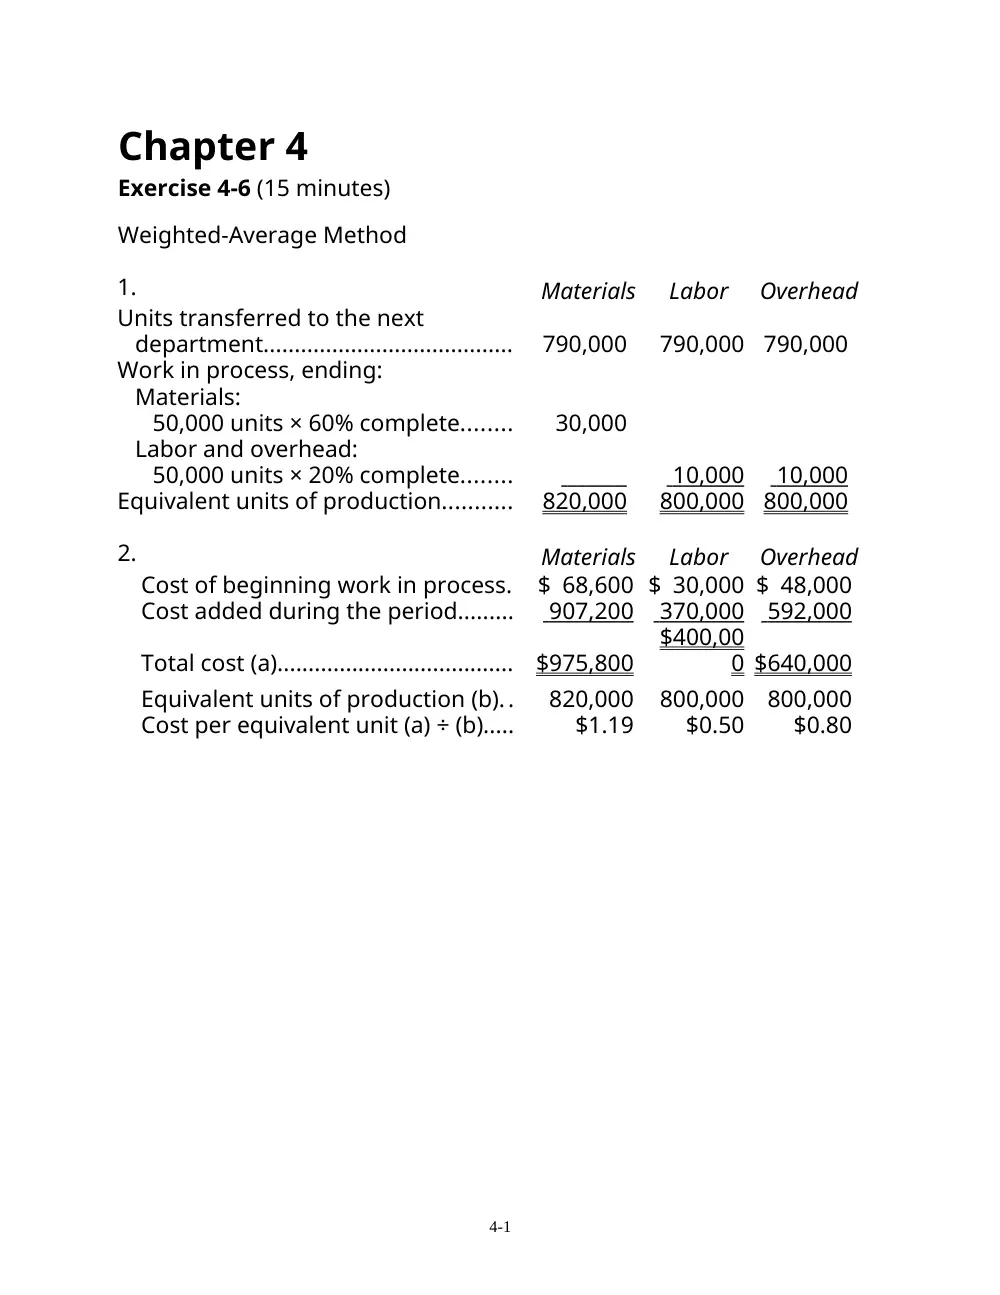
Chapter 4
Exercise 4-6 (15 minutes)
Weighted-Average Method
1.
Materials
Labor
Overhead
Units transferred to the next
department........................................
790,000
790,000
790,000
Work in process, ending:
Materials:
50,000 units × 60% complete........
30,000
Labor and overhead:
50,000 units × 20% complete........
10,000
10,000
Equivalent units of production...........
820,000
800,000
800,000
2.
Materials
Labor
Overhead
Cost of beginning work in process.
$ 68,600 $ 30,000 $ 48,000
Cost added during the period.........
907,200
370,000
592,000
Total cost (a)......................................
$975,800
$400,00
0 $640,000
Equivalent units of production (b)..
820,000
800,000
800,000
Cost per equivalent unit (a) ÷ (b).....
$1.19
$0.50
$0.80
4-1
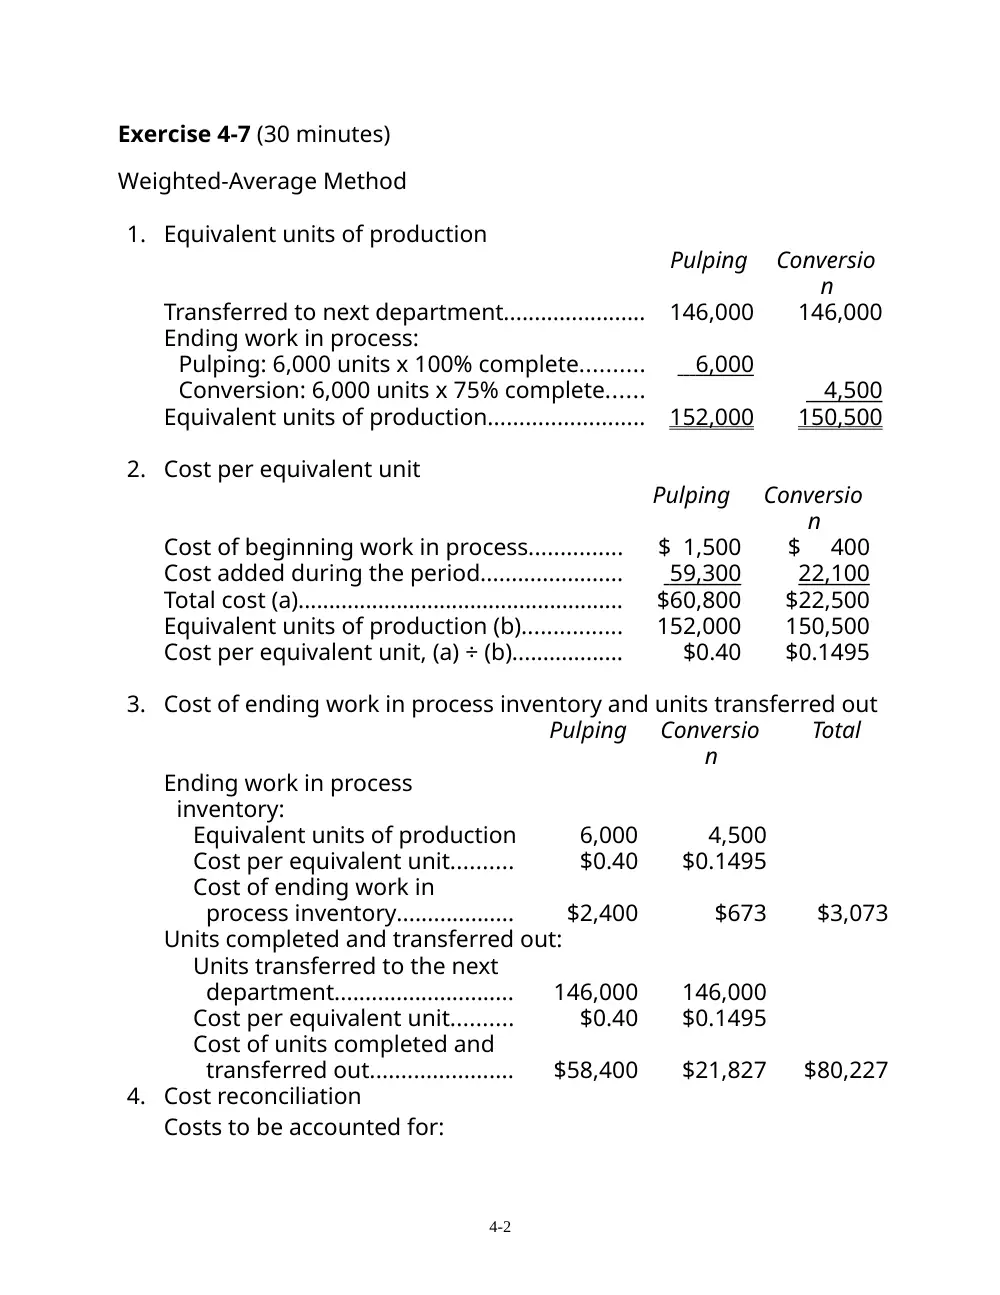
Exercise 4-7 (30 minutes)
Weighted-Average Method
1. Equivalent units of production
Pulping
Conversio
n
Transferred to next department.......................
146,000
146,000
Ending work in process:
Pulping: 6,000 units x 100% complete..........
6,000
Conversion: 6,000 units x 75% complete......
4,500
Equivalent units of production.........................
152,000
150,500
2. Cost per equivalent unit
Pulping
Conversio
n
Cost of beginning work in process...............
$ 1,500
$ 400
Cost added during the period.......................
59,300
22,100
Total cost (a).....................................................
$60,800
$22,500
Equivalent units of production (b)................
152,000
150,500
Cost per equivalent unit, (a) ÷ (b)..................
$0.40
$0.1495
3. Cost of ending work in process inventory and units transferred out
Pulping
Conversio
n
Total
Ending work in process
inventory:
Equivalent units of production
6,000
4,500
Cost per equivalent unit..........
$0.40
$0.1495
Cost of ending work in
process inventory...................
$2,400
$673
$3,073
Units completed and transferred out:
Units transferred to the next
department.............................
146,000
146,000
Cost per equivalent unit..........
$0.40
$0.1495
Cost of units completed and
transferred out.......................
$58,400
$21,827
$80,227
4. Cost reconciliation
Costs to be accounted for:
4-2
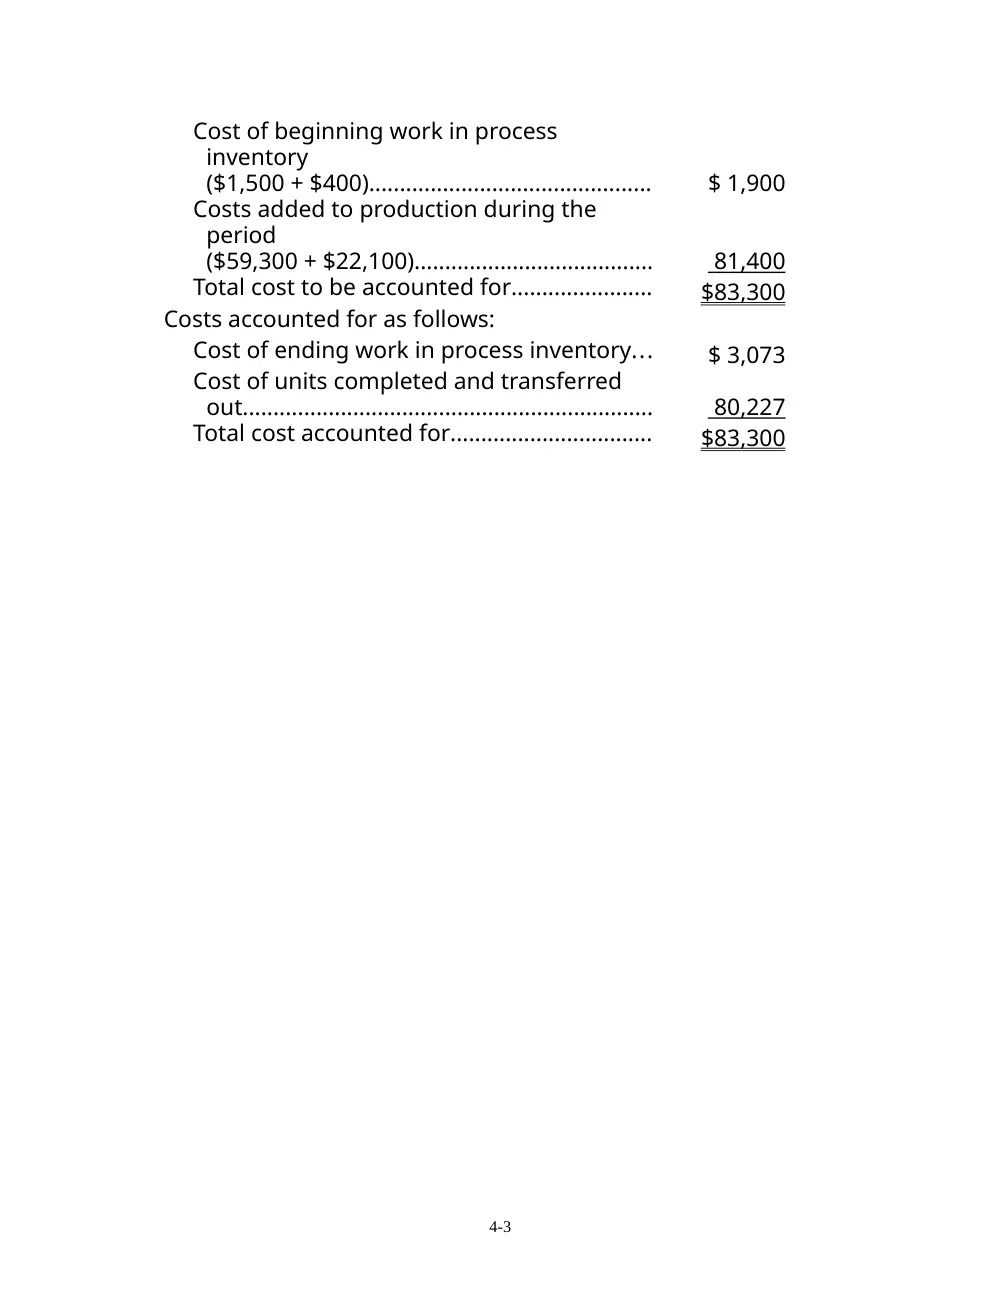
Cost of beginning work in process
inventory
($1,500 + $400)..............................................
$ 1,900
Costs added to production during the
period
($59,300 + $22,100).......................................
81,400
Total cost to be accounted for.......................
$83,300
Costs accounted for as follows:
Cost of ending work in process inventory...
$ 3,073
Cost of units completed and transferred
out...................................................................
80,227
Total cost accounted for.................................
$83,300
4-3
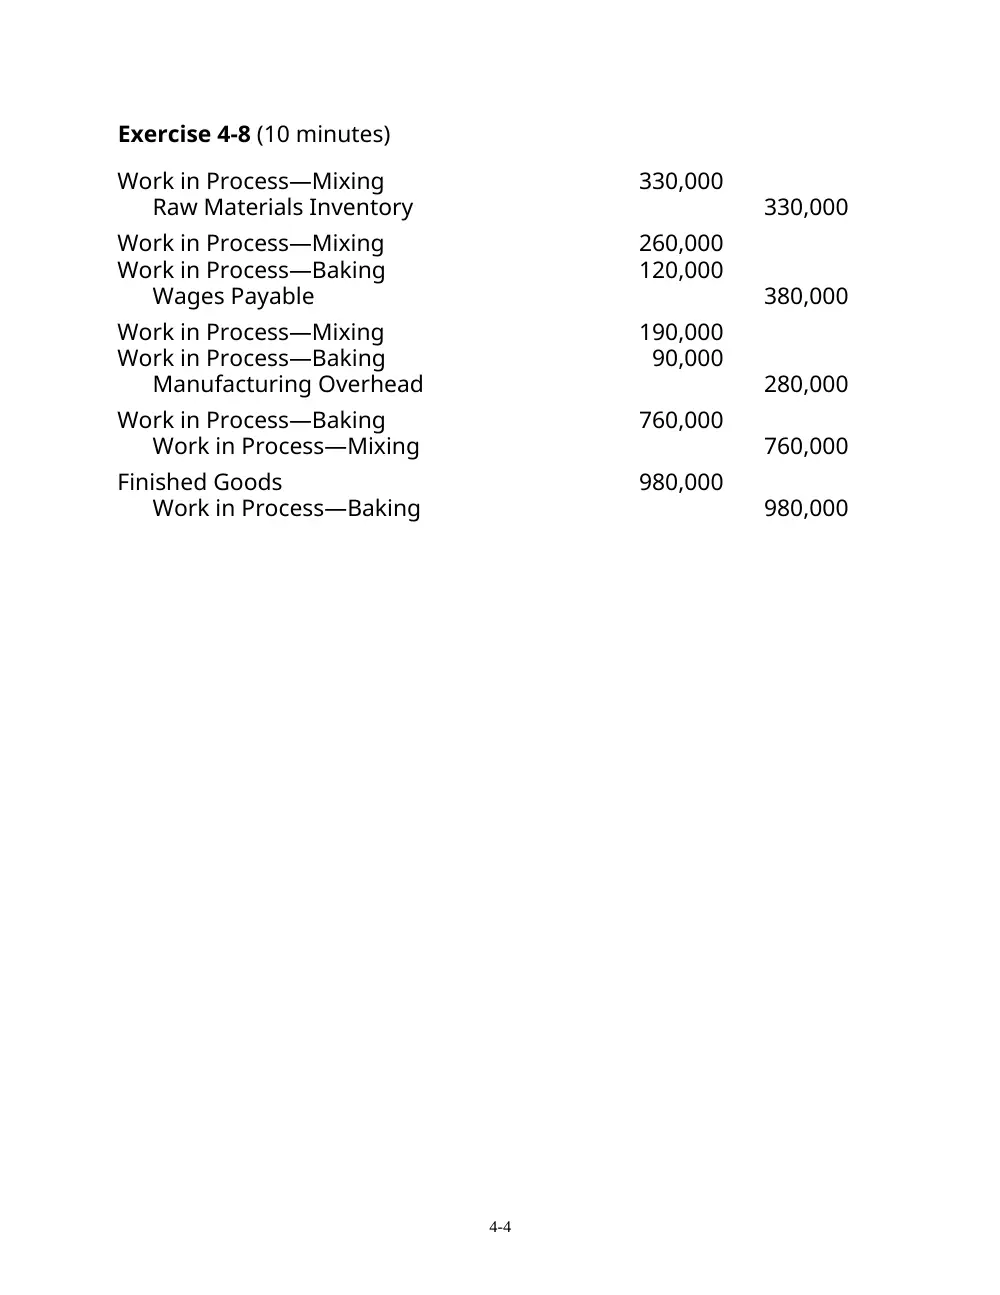
Exercise 4-8 (10 minutes)
Work in Process—Mixing
330,000
Raw Materials Inventory
330,000
Work in Process—Mixing
260,000
Work in Process—Baking
120,000
Wages Payable
380,000
Work in Process—Mixing
190,000
Work in Process—Baking
90,000
Manufacturing Overhead
280,000
Work in Process—Baking
760,000
Work in Process—Mixing
760,000
Finished Goods
980,000
Work in Process—Baking
980,000
4-4
Problem 4-14 (45 minutes)
Weighted-Average Method
1. Equivalent Units of Production
Material
s
Conversio
n
Transferred to next department.......................
450,000
450,000
Ending work in process:
Materials: 80,000 units x 75% complete........
60,000
Conversion: 80,000 units x 25% complete....
20,00
0
Equivalent units of production.........................
510,000
470,000
2. Cost per Equivalent Unit
Materials
Conversio
n
Cost of beginning work in process...............
$ 36,550
$ 13,500
Cost added during the period.......................
391,850
287,300
Total cost (a).....................................................
$428,400
$300,800
Equivalent units of production (b)................
510,000
470,000
Cost per equivalent unit, (a) ÷ (b)..................
$0.84
$0.64
3. Applying Costs to Units
Materials
Conversio
n
Total
Ending work in process
inventory:
Equivalent units of production
..............................................
60,000
20,000
Cost per equivalent unit......
$0.84
$0.64
Cost of ending work in
process inventory...............
$50,400
$12,800
$63,200
Units completed and transferred out:
Units transferred to the next
department.........................
450,000
450,000
Cost per equivalent unit......
$0.84
$0.64
Cost of units completed and
transferred out...................
$378,000
$288,000
$666,000
4-5
Problem 4-14 (continued)
4
.
Cost Reconciliation
Costs to be accounted for:
Cost of beginning work in process
inventory
($36,550 + $13,500).......................................
$ 50,050
Costs added to production during the
period
($391,850 + $287,300)..................................
679,150
Total cost to be accounted for.......................
$729,200
Costs accounted for as follows:
Cost of ending work in process inventory...
$ 63,200
Cost of units completed and transferred
out...................................................................
666,000
Total cost accounted for.................................
$729,200
Problem 4-15 (45 minutes)
Weighted-Average Method
1. Equivalent units of production
Material
s
Conversio
n
Transferred to next department*.....................
270,000
270,000
Ending work in process:
Materials: 45,000 units x 100% complete.....
45,000
Conversion: 45,000 units x 60% complete....
27,000
Equivalent units of production.........................
315,000
297,000
*Units transferred to the next department = Units in beginning work
in process + Units started into production − Units in ending work in
process = 35,000 + 280,000
45,000 = 270,000
−
2. Cost per equivalent unit
Materials
Conversio
n
Cost of beginning work in process...............
$ 43,400
$ 20,300
Cost added during the period.......................
397,600
187,600
4-6
Total cost (a).....................................................
$441,000
$207,900
Equivalent units of production (b)................
315,000
297,000
Cost per equivalent unit, (a) ÷ (b)..................
$1.40
$0.70
3. Cost of ending work in process inventory and units transferred out
Materials
Conversio
n
Total
4-7
Ending work in process
inventory:
Equivalent units of production
45,000
27,000
Cost per equivalent unit..........
$1.40
$0.70
Cost of ending work in
process inventory...................
$63,000
$18,900
$81,900
Units completed and transferred out:
Units transferred to the next
department.............................
270,000
270,000
Cost per equivalent unit..........
$1.40
$0.70
Cost of units completed and
transferred out.......................
$378,000
$189,000
$567,000
4-8
Problem 4-16 (45 minutes)
Weighted-Average Method
1. a. Work in Process—Blending
147,600
Work in Process—Bottling
45,000
Raw Materials
192,600
b. Work in Process—Blending
73,200
Work in Process—Bottling
17,000
Salaries and Wages Payable
90,200
c. Manufacturing Overhead
596,000
Accounts Payable
596,000
d. Work in Process—Blending
481,000
Manufacturing Overhead
481,000
Work in Process—Bottling
108,000
Manufacturing Overhead
108,000
e. Work in Process—Bottling
722,000
Work in Process—Blending
722,000
f. Finished Goods
920,000
Work in Process—Bottling
920,000
g. Accounts Receivable
1,400,000
Sales
1,400,000
Cost of Goods Sold
890,000
Finished Goods
890,000
4-9
Problem 4-16 (continued)
2.
Accounts Receivable
Raw Materials
(g)
1,400,000
Bal.
198,600
(a)
192,600
Bal.
6,000
Work in Process
Blending Department
Work in Process
Bottling Department
Bal.
32,800
(e)
722,000
Bal.
49,000
(f)
920,000
(a)
147,600
(a)
45,000
(b)
73,200
(b)
17,000
(d)
481,000
(d)
108,000
Bal.
12,600
(e)
722,000
Bal.
21,000
Finished Goods
Manufacturing Overhead
Bal.
20,000
(g)
890,000
(c)
596,000
(d)
589,000
(f)
920,000
Bal.
7,000
Bal.
50,000
Accounts Payable
Salaries and Wages Payable
(c)
596,000
(b)
90,200
Sales
Cost of Goods Sold
(g)
1,400,000
(g)
890,000
Problem 4-17 (60 minutes)
Weighted-Average Method
1. Computation of equivalent units in ending inventory:
Mixing
Materials
Conversion
Units transferred to the next department.....
60.0
60.0
60.0
Ending work in process:
Mixing: 1 unit × 100% complete................
1.0
Materials: 1 unit × 20% complete..............
0.2
Conversion: 1 unit × 10% complete...........
0.1
4-10
Equivalent units of production........................
61.0
60.2
60.1
2. Costs per equivalent unit:
Mixing
Materials
Conversion
Cost of beginning work in process inventory
$ 1,640
$ 26
$ 105
Cost added during the period.........................
94,740
8,402
61,197
Total cost............................................................
$96,380
$8,428
$61,302
Equivalent units of production........................
61.0
60.2
60.1
Cost per equivalent unit...................................
$1,580
$140
$1,020
4-11
Problem 4-17 (continued)
3. Costs of ending work in process inventory and units transferred out:
Mixing
Materials
Conversion
Ending work in process inventory:
Equivalent units of production..................
1.0
0.2
0.1
Cost per equivalent unit.............................
$1,580
$140
$1,020
Cost of ending work in process inventory
$1,580
$28
$102
Units completed and transferred out:
Units transferred to the next department
60.0
60.0
60.0
Cost per equivalent unit.............................
$1,580
$140
$1,020
Cost of units transferred out......................
$94,800
$8,400
$61,200
4. Cost reconciliation:
Cost to be accounted for:
Cost of beginning work in process
inventory
($1,640 + $26 + $105)...................................
$ 1,771
Cost added to production during the
period
($94,740 + $8,402 + $61,197).......................
164,339
Total cost to be accounted for.......................
$166,110
Costs accounted for as follows:
Cost of ending work in process inventory...
$ 1,710
Cost of units transferred out.........................
164,400
Total cost accounted for.................................
$166,110
4-12